The grocery retail market in New Zealand is worth billions of dollars each year and is one of the most concentrated supermarket sectors in the world. The industry is dominated by two large groups: Foodstuffs and Woolworths New Zealand. Together, these firms account for around 80–90 per cent of grocery sales, with Foodstuffs operating brands such as Pak’nSave, New World and Four Square, while Woolworths operates the Woolworths supermarket chain.
The market displays many of the characteristics of an oligopoly. The two dominant firms compete through store location, loyalty schemes, advertising and product range, and to some extent through pricing. At the same time, they benefit from substantial economies of scale, extensive distribution networks and strong relationships with suppliers. These factors mean that there are significant barriers to entry in the market and this can prevent new firms from entering the market and surviving.
Competition concerns
Concern about competition in the sector has led to investigations by New Zealand’s Commerce Commission. The Commission concluded that although there was competition in the market, it was less than optimal and both firms were earning higher profits than they would have been able to earn had they been in operating in a more competitive market.
 It identified various barriers to entry that limited competition, including access to suitable retail sites, ownership of distribution networks and the difficulty of establishing large-scale supply chains in a country with a relatively small population.
Despite the market being dominated by these two big firms, there are also many smaller retailers operating within the market, including independent grocery stores, convenience stores and specialist food retailers. However, they lack the scale that is needed to challenge the dominance of Foodstuffs and Woolworths at a national level.
Potential international entrants, such as Aldi and Lidl, have often been suggested as possible competitors, but the costs of establishing a nationwide network of stores and distribution facilities in New Zealand are significant. There have been examples of large and dominant supermarkets in one country attempting to enter the market in other countries but failing to survive or deciding to exit the market early. For example, Tesco entered the Chinese market in 2004 but, despite its efforts, exited the market in 2020.
Response by the New Zealand government
 In response to concerns about competition, the New Zealand government has introduced a series of measures designed to make market entry easier. These include restrictions on anti-competitive land covenants, the introduction of a Grocery Commissioner and changes intended to improve access to wholesale grocery supply.
But, despite these measures, recent reports suggest that the overall market structure has changed little, with the two major firms continuing to dominate grocery retailing.
The public interest
Supporters of the current market structure argue that large supermarket chains deliver lower costs through economies of scale and provide consumers with extensive product choice.
Critics counter that limited competition leads to higher prices, reduced innovation and weaker bargaining power for suppliers.
The debate illustrates the difficulties faced by policymakers when attempting to balance efficiency against the promotion of competition.
Whether greater competition will emerge in the future remains uncertain. Much will depend on whether existing reforms can encourage new entrants or whether the structural advantages enjoyed by Foodstuffs and Woolworths continue to deter potential rivals.
Articles
- ‘Substantive, potentially systemic’ supermarket concerns raised by Commerce Commission
RNZ News, Susan Edmunds (7/7/26)
- Supermarkets aren’t the problem. This issue is a far bigger deal
Money Stuff, Rupert Carlyon (23/9/26)
- This may be as good as it gets: NZ and Australia face a complicated puzzle when it comes to supermarket prices
The Conversation, Richard Meade (23/4/25)
- Every party has pitched its own supermarket fix. What if we combined the best ideas?
The Conversation, Jonathan Baker (21/9/26)
- NZ regulator eyes ‘problematic’ supermarket supplier fees
Inside FMCG, Sean Cao (7/7/26)
- Australia vs NZ: Supermarket competition compared
Consumer NZ, Vanessa Pratley (27/3/25)
- Grocery Commissioner puts supermarkets on notice
RNZ News, Susan Edmunds (18/3/26)
- High margins, double the normal returns – does NZ’s supermarket duopoly drive prices up?
The Press, Susan Edmunds (22/9/26)
- Everyone wants to break up the supermarkets. How would it actually work?
The Spinoff, Joel MacManus (22/9/26)
Questions
- What are the characteristics of the New Zealand supermarket industry that create barriers to entry for new firms?
- To what extent is the New Zealand grocery market consistent with the characteristics of an oligopoly?
- Evaluate the likely effectiveness of government measures designed to increase competition in the supermarket sector.
- Australia too has two main supermarket chains: Coles and Woolworths. However, Aldi has entered the Australian market and in some parts of the country had provided significant competition to the two major chians. Why may Aldi have more difficulty in entering the New Zealnd market
- Investigate the grocery retail market in another country (not the UK). Who are the major competitors and what is their market share? What barriers to entry exist? Has the competition authority expressed concerns about the market and if so, what are they?
Artificial intelligence (AI) has become a key technology in the 21st Century. Businesses use AI systems to analyse data, automate routine tasks, improve customer service, write software, create content and even assist with decision-making. As AI improves and becomes even more capable, governments, economists, businesses and society are debating its effects on productivity, employment and economic growth – and also its potentially extreme dangers.
Some commentators compare AI to earlier technological revolutions such as the steam engine, electricity and the Internet. They argue that AI will continue to increase productivity, create new industries and improve living standards. Others worry that AI may eliminate a large numbers of jobs, increase inequality, concentrate economic power in a few firms and, in the most extreme scenarios, pose a threat to humanity itself.
These debates raise important questions including how society should evaluate the potential risks of a technology whose benefits may be enormous but whose long-term consequences remain uncertain.
AI and the labour market
 Historically, technological change has had both positive and negative effects on employment. Automation reduced the demand for many agricultural workers, while creating jobs in manufacturing. Computers automated clerical tasks but generated entirely new industries in software, telecommunications and digital services.
AI appears likely to follow a similar pattern. According to the World Economic Forum, advances in AI, robotics and information-processing technologies are expected to transform labour markets significantly during the second half of the 2020s, creating demand for new skills while reducing demand for others. The fastest-growing skills are expected to include AI and big data, technological literacy and cybersecurity.
The potential benefits
AI may benefit labour markets in several ways:
- Higher productivity: Workers can complete tasks more quickly with AI assistance.
- New occupations: Demand has emerged for AI engineers, prompt specialists, data scientists and AI governance professionals.
- Better decision-making: Firms can use AI to improve forecasting, inventory management and customer service.
- Complementing human skills: AI may perform repetitive tasks, allowing employees to focus on creativity, problem-solving and interpersonal activities.
- Economic growth: Higher productivity can increase profits, wages and living standards over time.
Many economists argue that AI will not simply replace workers but will change the tasks they perform. Research from the OECD suggests that even highly AI-exposed occupations continue to require management, communication, collaboration and social skills that technologies struggle to replicate.
The potential costs
 At the same time, AI may create significant labour-market challenges. Many white-collar occupations previously considered relatively safe from automation are becoming vulnerable. Generative AI systems can draft reports, analyse legal documents, write computer code and create marketing content. This means that some professional and administrative roles may face considerable disruption.
The World Economic Forum reports that business leaders have differing expectations about the effects of AI. In a 2026 survey (see link below), around 54 per cent expected AI to displace existing jobs, while only 24 per cent expected it to create new jobs within their organisations. Economists have identified several potential problems:
- Structural unemployment: workers in industries that are in decline may struggle to find employment requiring their existing skills.
- Increased income inequality: there may be a growing income disparity between highly skilled and less-skilled workers.
- Growing market power: the largest technology firms that own the most advanced AI systems may see their market power grow further creating dominance in certain areas.
- Regional inequalities: AI-related investment may become concentrated in particular cities and countries, exacerbating regional inequalities within and between countries.
- Pressure on governments: to address issues of structural unemployment and increasing inequality, governments may be forced to expand retraining and social-support programmes.
AI and catastrophic risk
 Most economic discussion around AI focuses on employment and productivity. However, some researchers argue that the most significant risks from AI may be much broader.
Economists distinguish between ordinary risks and catastrophic risks. Catastrophic risks involve events with a very low probability of occurring but potentially enormous consequences. Examples include nuclear accidents, pandemics and certain climate-related disasters.
AI raises similar concerns. Advanced AI systems could potentially be used to conduct cyberattacks, spread misinformation, disrupt critical infrastructure or support the development of dangerous technologies. Some researchers have even suggested that highly advanced AI systems could pose an existential risk to humanity if they become sufficiently powerful and are not properly controlled.
This became a widely discussed topic in the media in September 2026 following the resignation of an employee, Jacob Coxon, from AI firm, Anthropic. He said that people working on AI were ‘genuinely frightened’ about how quickly AI was advancing and what it might mean for the future of humanity. He said:
I believe that if we don’t slow down at the current rate of progress, there is a strong chance that we could all die in the immediate future.
Other researchers have raised similar concerns and there have since been calls from some of the biggest AI companies for regulation of AI to prevent this.
The policy debate and CBA
 All of this creates a challenge for cost-benefit analysis. Suppose AI generates trillions of pounds of economic benefits. But, if there is also a very small probability of catastrophic harm, how should policymakers weigh up the two?
Traditional cost-benefit analysis values risk by multiplying the size of a potential outcome by its probability. However, this approach becomes problematic when both the probability and the consequences are highly uncertain. The risks may be extremely difficult to estimate, while the potential costs could be vast and affect future generations. For this reason, governments and firms increasingly use scenario analysis, stress testing and AI safety assessments to evaluate potential risks. These approaches attempt to prepare for extreme outcomes rather than relying solely on probability calculations.
Supporters of AI argue that technological progress has historically improved living standards and that restricting AI too heavily could reduce innovation and economic growth. Critics argue that uncertainty about potentially catastrophic outcomes justifies a more cautious approach.
The debate therefore extends beyond labour economics to the wider issue of managing catastrophic risk. As with nuclear power or climate change, policymakers must decide how much risk society is willing to accept in exchange for potentially large economic benefits.
Articles
- Why are there concerns AI could threaten humanity, and how real are they?
BBC News, Liv McMahon (17/9/26)
- Two dire warnings, one from Terence Tao, the other from someone who just quit Anthropic
Marcus on AI, Gary Marcus (9/9/26)
- AI insiders fear extinction. Security experts see a familiar fight
Scientific American, Peter Hall (11/9/26)
- US rejects pleas from OpenAI, Anthropic for global AI standards
BBC News, Kali Hays (24/9/26)
- How would AI actually kill all humans? Here are the top 5 scenarios
The Conversation, Toby Walsh (22/9/26)
- Who’s Who In The Fight Over Whether AI Will Kill Us
Forbes, Andréa Morris (24/9/26)
- Why this AI doomsday warning from former Anthropic researcher broke through
The Guardian, Blake Montgomery (15/9/26)
 As AI behavior raises concerns, ex-researcher Jacob Coxon warns what may lie ahead
PBS News
- ‘A setup’: Elon Musk fuels wild theory about Anthropic whistleblower Jacob Coxon
ABC News, Harrison Christian (11/9/26)
- Sam Altman, Dario Amodei urge UN Security Council to adopt international AI standards
CNN, Hadas Gold (24/9/26)
- Not everyone thinks AI will kill us all
CNN, Hadas Gold and Clare Duffy (24/9/26)
- The turbulent AI era is here. The choices we make now are critical.
Gates Notes, Bill Gates (26/8/26)
Reports
Questions
- How might AI increase productivity while also causing unemployment in some sectors? Which sectors are likely to be affected the most?
- Why is it difficult to estimate the costs and benefits of advanced AI?
- Assume that a disaster is estimated to cost society £1000 billion (£1 000 000 000 000). The chances of the disaster occurring are said to be minute, however. Estimates vary from a probability of one in a million to one in a billion. What estimate of this cost would you include in a cost–benefit analysis?
- Why are many low-income countries apparently prepared to accept riskier projects than are high-income ones?
- Discuss whether the greatest economic challenge posed by AI is (a) job displacement; (b) increased inequality; (c) market concentration and the power of large technology firms; or (d) catastrophic long-term risks.
- Read the article by Bill Gates, The turbulent AI era is here. The choices we make now are critical. According to him, what steps should the world take to ensure that ‘AI will be a force for good and leave everyone better off’?
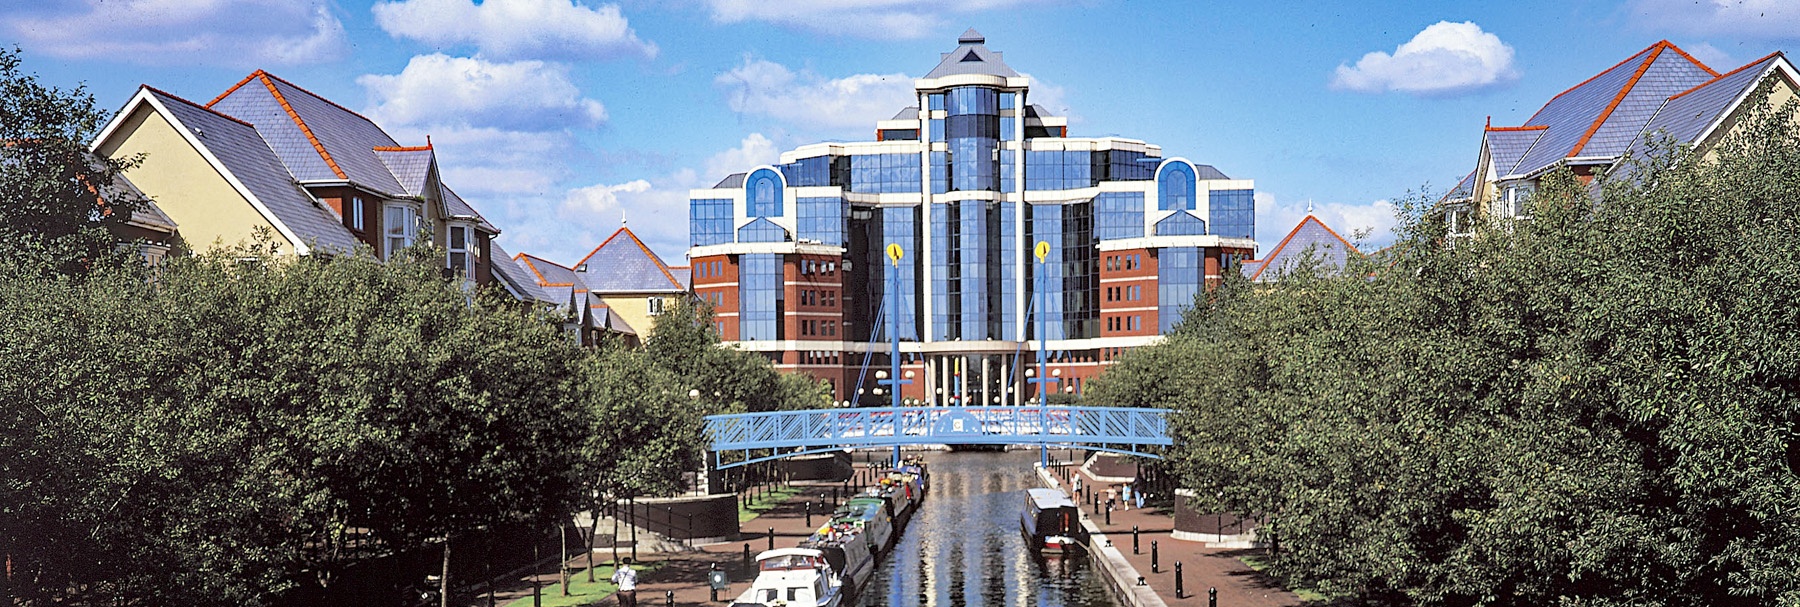
Andy Burnham is set to become UK Prime Minister on 20 July if no-one else stands to replace Keir Starmer. In a speech on 29 June, he outlined his economic vision. Central to this is devolution, where a greater number of economic decisions would be taken locally rather than by central government. This approach has been dubbed ‘Manchesterism’, in reference to his time as Mayor of Greater Manchester from 2017 to earlier this year. Under his mayoralty, Greater Manchester (GM) achieved faster economic growth than other regions or cities in the UK. From 2017 to 2023, GM’s gross value added grew by an average of 6.6% per annum and the city of Manchester’s by 8.4% – the highest of any city in the UK. The UK average was 4.9% and London’s was 4.6%.
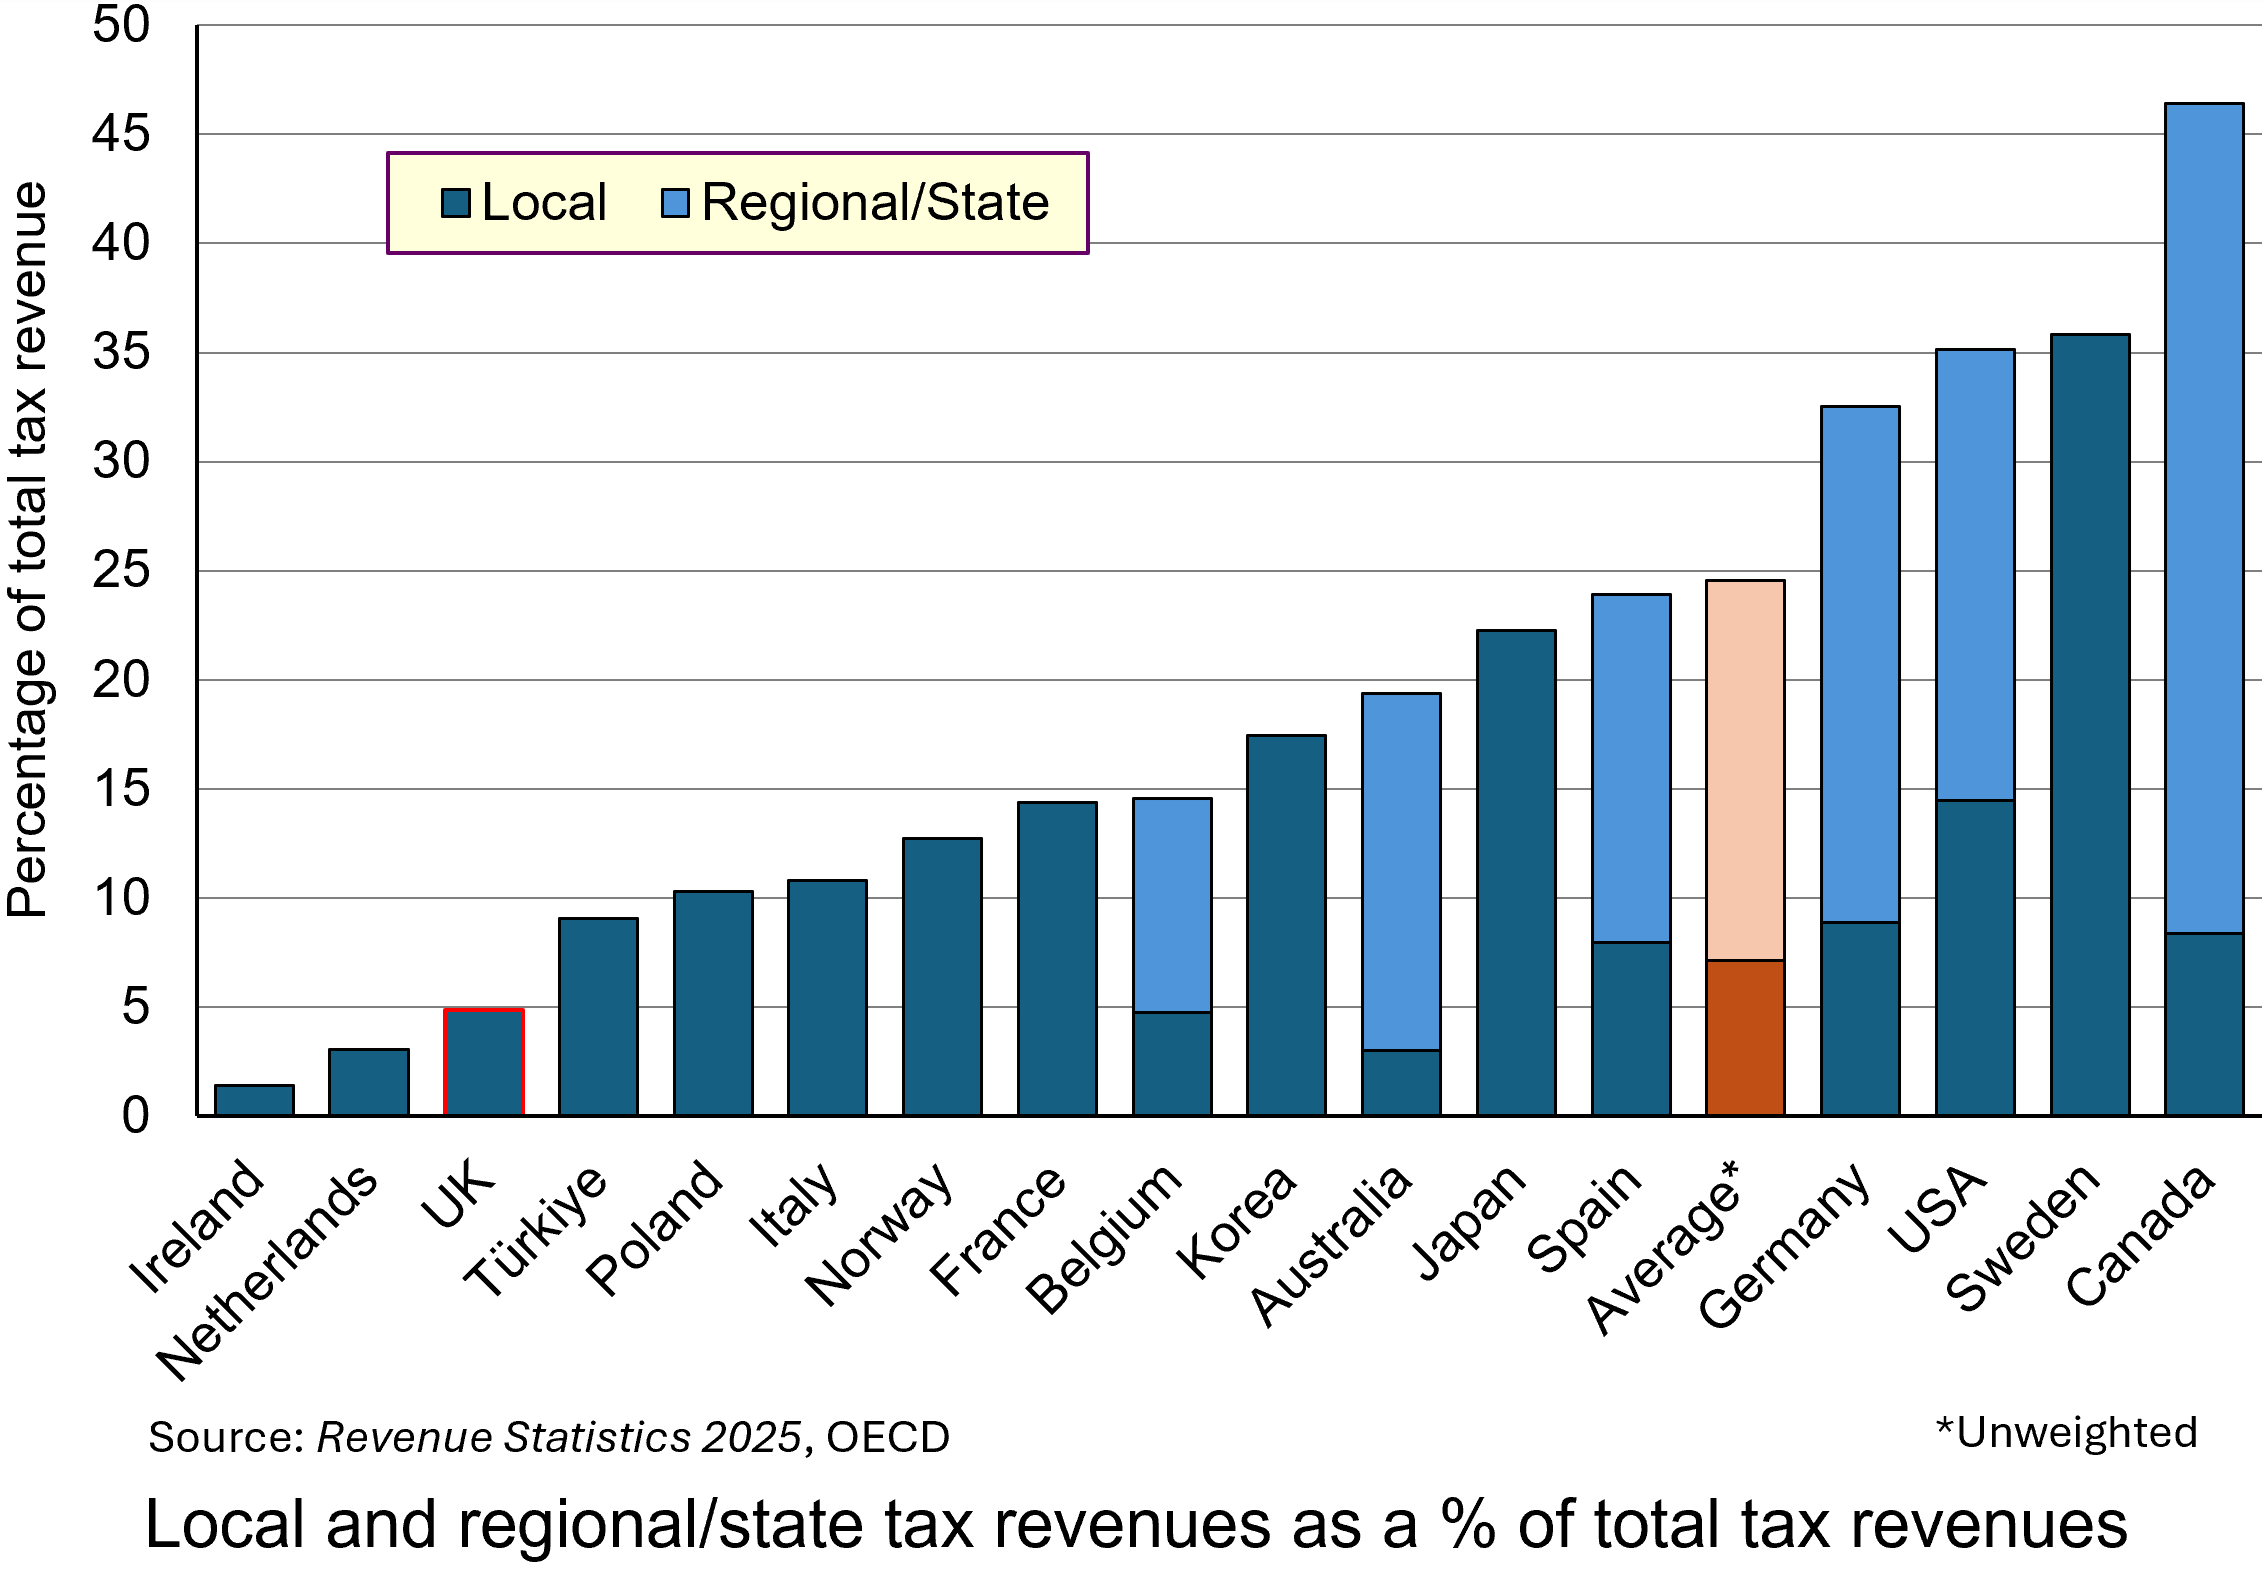 The UK, especially England, is one of the least devolved of the OECD countries. One aspect of this is taxation. The chart shows local taxes and, in the case of federal countries, state/regional/provincial taxes too. (Click here for a PowerPoint.)
Only 4.9% of UK tax revenue is in the form of local taxes (council tax and 50% of business rates) and the amount that can be raised in council tax is capped by the central government. The remainder of UK tax revenue goes to central government in the form of income taxes, social security taxes (national insurance), VAT, excise duties, etc. This compares with an average of 7.1% local taxes and 24.5% local plus regional taxes across the 17 OECD countries shown in the chart.
Andy Burnham plans to shift some of the spending and tax-raising powers from Whitehall to metro mayors and local councils. The aim is to stimulate productivity and economic growth at a regional and local level by tailoring support and incentives to local needs and strengths. Local leaders will be best positioned to understand these needs and strengths and will be able to customise spending and support appropriately.
 Examples of the types of greater autonomy over decision making would include:
- Control over adult education budgets to allow them to be tailored to provide training and apprenticeships to meet the skills requirements of existing and emerging industries in the area;
- Forming partnerships with local universities to support research and development that complements regional economic growth;
- Providing greater funding for and control over local transport infrastructure, including roads, buses, trams, trains, etc., with local consultation to make them fit for the local population and businesses;
- Tailoring business incentives to local needs and to the needs of the businesses themselves so as to attract an increase in investment;
- Greatly expanding council house building, which has virtually dried up in recent years, with mayors and/or local authorities empowered to develop local housing strategies, including affordable housing programmes, and to direct housing investment funding to particular housing developments in areas of greatest need.
Andy Burnham has pledged to stick to the government’s two existing fiscal rules:
a) The Stability Rule (Fiscal Mandate): the current (day-to-day) budget must be in balance or surplus. In other words the provision of salaries, public services, state pensions, welfare, etc. must be covered by government revenues (largely taxation). The government should borrow only to fund long-term investment.
b) The Debt Rule (Stock Mandate): each year, public-sector net financial liabilities (PSNFL) must be forecast by the OBR to be falling as a share of GDP compared to the previous year in three years’ time. This acts as a break on the amount of borrowing for long-term investment.
It is likely, therefore, that there will be little extra government money for investment. Rather, the policy involves a redistribution of public-sector investment from central government to mayoral/local authorities.
 In theory, such a policy of devolution need not see a redistribution from richer to poorer regions, but that might be part of the policy when the details are published. The UK has a bigger gap in productivity (GDP per worker) between its capital city and other large cities than in do other countries. Birmingham, Sheffield, Leeds, Newcastle, etc., as well as Cardiff, Glasgow, Edinburgh and Belfast, lag further behind London in output per head and economic growth than do other European countries lag behind their capital city. Thus the gap between Paris and Lyon, Toulouse and Marseille is narrower; as is that between Belin and Munich, Hamburg and Frankfurt. It is a similar picture in Spain and Italy. In the USA, some cities, such as San Francisco, outperform Washington DC and New York. A redistribution of government funding from London to the regions could see their incomes rise faster without having too much impact on London, which would still continue to attract large amounts of private investment.
Overall, there would be little increase in government funding. ‘Manchesterism’ is not, therefore, a demand-side policy. It is a supply-side policy – directing funds to areas where, combined with local incentives and local knowledge, the funding could yield greater returns and thereby increase potential GDP.
But this is not to say that there is no effect on aggregate demand. The hope is that devolution along the lines outlined by Andy Burnham will attract increased private investment, thereby increasing actual GDP as well as further increasing potential GDP.
We wait to see the details over the coming weeks.
Articles
- Will Andy Burnham’s devolution plan raise economic growth?
BBC Verify, Ben Chu (29/6/26)
- Burnham’s ‘Manchesterism’ could change the UK, but is not yet a full economic plan
BBC News, Faisal Islam (29/6/26)
- Burnham’s ‘Manchesterism’ got him to No 10 – but will it work for the UK?
BBC News, Faisal Islam (17/7/26)
- Burnham says there is some room for movement on tax
BBC News, Kate Wannel and Joshua Nevett (3/7/26)
- England’s mayors should be given sweeping new powers, says devolution expert
The Guardian, Kiran Stacey (2/7/26)
- What is Andy Burnham’s economic and political blueprint for Britain?
The Guardian, Richard Partington and Jessica Elgot (29/6/26)
- Why Andy Burnham’s radical plan relies on the Treasury being a friend of devolution
The Conversation, Dave Richards and Sam Warner (26/6/26)
- How Andy Burnham may try to give the UK economy a boost in his ‘10‑year plan’
The Conversation, Steve Schifferes (29/6/26)
- Could Andy Burnham let mayors raise more taxes?
House of Commons Research Briefing, Mark Sandford (2/7/26)
- Andy Burnham sets out policy plans in first major speech in PM leadership bid: Legal comments
Browne Jacobson, Dan Robinson (29/6/26)
- What does Andy Burnham think ‘Good Growth’ is?
Centre for Cities, Jess Tulasiewicz (30/6/26)
- Manchester’s digital transformation could be a blueprint for other parts of the UK
The Conversation, Richard Whittle (21/7/26)
Videos
Data
Questions
- Use an aggregate demand and supply diagram (simple or dynamic) to illustrate the effects on real GDP of a successful devolution strategy.
- Find out the details of the last Conservative government’s ‘levelling up’ policy. Was it similar in aims to that of ‘Manchesterism’?
- How could a policy of devolution as outlined by Andy Burnham affect income distribution within regions?
- Find out about the approach to regional policy in the EU. Is it similar to that being advocated by Andy Burnham?
- What is meant by ‘regional multipliers’? Why might they differ from the national multiplier?
 When we think about suppliers and retailers working together, we usually imagine negotiations over things like the price a retailer pays for products, the quantities ordered, or delivery schedules. However, some suppliers do much more than simply supplying products. In fact, suppliers to many supermarkets also advise them on which brands to stock, how much shelf space each brand should get, and which products to promote. In this role, known as a ‘category captain’, a supplier can influence not only its own products but also those of its competitors within a specific category of products.
For example, if Red Bull were acting as a category captain in the energy drinks category for a supermarket like Tesco, it could also advise on where its competitor, Monster Energy, appears on the shelves, or even whether it appears at all!
Sounds problematic? Arrangements like these are an example of vertical relationships between suppliers and retailers, something economists often study. Like other vertical arrangements, such as exclusive dealing, they can have both benefits and drawbacks. For example, while a category captain can result in efficiency gains, allow for a more organised category of products and improve consumer choice, it also raises questions when the supplier giving the advice also competes with the products it is advising on.
 That is exactly what the European Commission (EC), the EU’s competition authority, began examining in November 2025, when it opened an investigation into potential anticompetitive conduct by Red Bull.
One of the key concerns is whether Red Bull used its role as a category captain to disadvantage competing energy drink brands.
Category management is common … but novel for enforcement
The practice of appointing a category captain is not new. Many large supermarkets appoint category captains from major consumer goods suppliers. For example, firms such as Kraft Foods and Procter & Gamble have long taken on category management roles in a range of consumer-packaged goods categories.
However, despite how common these arrangements are in retail, this is the first time the EC has formally investigated whether a supplier has misused its category management role to limit or disadvantage competing products, and it has said it will treat the case as a priority.
How Red Bull could be disadvantaging competitors
 According to the Commission, Red Bull appears to hold a dominant position in the wholesale supply of branded energy drinks, at least in The Netherlands. In competition policy, a firm which holds a dominant position has a special responsibility to ensure that its actions do not unfairly restrict competition. Regulators are investigating whether the company abused this position by offering financial or non-financial incentives and/or leveraging its role as a category captain to disadvantage competing energy drinks sold in larger can sizes.
At an extreme, a category captain could advise a supermarket to stop selling a competitor’s product entirely, effectively excluding the brand from the shelves and potentially reducing consumer choice.
But there are also more subtle ways Red Bull could disadvantage its competitors. Insights from behavioural economics suggest that the placement of products on shelves can strongly influence what consumers notice and buy. By reducing the visibility of rival energy drinks, for example, products in less prominent locations are less likely to be purchased and are therefore disadvantaged.
These practices matter for consumers as well as competitors. By limiting which products are stocked or how prominently they are displayed, dominant suppliers could reduce choice and potentially keep prices higher.
Growing scrutiny of category management?
 Competition authorities seem to be paying closer attention to how suppliers influence the management of product categories in retail stores. In April 2025, the Belgian Competition Authority fined three large pharmaceutical companies more than €11 million for co-ordinating the placement of over-the-counter medicines in pharmacies. The companies had created shelf layouts that favoured their own products, disadvantaged competing brands, and monitored whether pharmacies followed the plans.
Thus far there have not been many European cases related to category management.
Why the Red Bull case matters
The Red Bull investigation is the first EC case focusing specifically on the potential misuse of category management by a dominant supplier. There is currently little guidance on how these arrangements should be assessed under competition law, meaning the case could set an important precedent.
If the Commission concludes that category management was used strategically to disadvantage competitors, Red Bull could be found to have abused its dominant position under EU competition rules. Such a decision could reshape supplier–retailer relationships across Europe.
Articles
Questions
- Beyond prices, how might dominant suppliers influencing shelf space affect competition and consumer choice?
- How might category captain arrangements affect barriers to entry?
- What are the potential efficiencies of supplier-led category management, and what are the possible anti-competitive effects?
- What guidelines or safeguards could regulators provide to ensure category captains deliver the potential efficiencies without harming competition?
 A previous post detailed how Netflix and Paramount Skydance were competing to acquire part or all of Warner Bros. Discovery (WBD). In December 2025, Netflix announced that it had agreed a deal to buy WBD’s studio and streaming service business. However, Paramount has still pursued a hostile takeover of WBD.
In mid-February 2026, it emerged that WBD had reopened talks with Paramount. Paramount was given a week to make its final offer. Then, under the agreed deal, Netflix would have the right to adjust its bid. Things have developed quickly since then.
Paramount raised its offer price by $1 per share making the deal worth a total of $111bn. WBD stated that this was superior to Netflix’s offer and Netflix declined to increase its bid. Netflix executives stated that:
This transaction was always a ‘nice to have’ at the right price, not a ‘must have’ at any price.1
Paramount will also pay Netflix the $2.8bn fee WBD owes Netflix for terminating the deal.
Whilst it appears Paramount has won the race to acquire WBD, the deal still needs regulatory clearance from competition authorities in the USA and Europe. Paramount CEO, David Ellison, stated that the proposal offered WBD shareholders ‘superior value, certainty and speed to closing.’2
Should the deal go through, the merged company would be in a powerful position as one of the few remaining Hollywood film and television studios.
References
- Paramount set for $111bn Warner Bros takeover after Netflix drops bid
BBC News, Danielle Kaye and Nardine Saad (26/2/26)
- Ibid
Articles
Questions
- What are the similarities and differences between Netflix’ and YouTube’s business models? How close substitutes do you think they are?
- Do you think cinemas are a closer or more distant substitute to Netflix than YouTube?
- Which of the possible deals, do you think, raised the most competition concerns? What might be a possible remedy that could alleviate these concerns?
- Was WBD’s decision to accept the Paramount takeover purely determined by the size of Paramount’s bid?
- What is the significance of legacy assets to the acquisition of WBD?
