Artificial intelligence (AI) has become a key technology in the 21st Century. Businesses use AI systems to analyse data, automate routine tasks, improve customer service, write software, create content and even assist with decision-making. As AI improves and becomes even more capable, governments, economists, businesses and society are debating its effects on productivity, employment and economic growth – and also its potentially extreme dangers.
Some commentators compare AI to earlier technological revolutions such as the steam engine, electricity and the Internet. They argue that AI will continue to increase productivity, create new industries and improve living standards. Others worry that AI may eliminate a large numbers of jobs, increase inequality, concentrate economic power in a few firms and, in the most extreme scenarios, pose a threat to humanity itself.
These debates raise important questions including how society should evaluate the potential risks of a technology whose benefits may be enormous but whose long-term consequences remain uncertain.
AI and the labour market
 Historically, technological change has had both positive and negative effects on employment. Automation reduced the demand for many agricultural workers, while creating jobs in manufacturing. Computers automated clerical tasks but generated entirely new industries in software, telecommunications and digital services.
AI appears likely to follow a similar pattern. According to the World Economic Forum, advances in AI, robotics and information-processing technologies are expected to transform labour markets significantly during the second half of the 2020s, creating demand for new skills while reducing demand for others. The fastest-growing skills are expected to include AI and big data, technological literacy and cybersecurity.
The potential benefits
AI may benefit labour markets in several ways:
- Higher productivity: Workers can complete tasks more quickly with AI assistance.
- New occupations: Demand has emerged for AI engineers, prompt specialists, data scientists and AI governance professionals.
- Better decision-making: Firms can use AI to improve forecasting, inventory management and customer service.
- Complementing human skills: AI may perform repetitive tasks, allowing employees to focus on creativity, problem-solving and interpersonal activities.
- Economic growth: Higher productivity can increase profits, wages and living standards over time.
Many economists argue that AI will not simply replace workers but will change the tasks they perform. Research from the OECD suggests that even highly AI-exposed occupations continue to require management, communication, collaboration and social skills that technologies struggle to replicate.
The potential costs
 At the same time, AI may create significant labour-market challenges. Many white-collar occupations previously considered relatively safe from automation are becoming vulnerable. Generative AI systems can draft reports, analyse legal documents, write computer code and create marketing content. This means that some professional and administrative roles may face considerable disruption.
The World Economic Forum reports that business leaders have differing expectations about the effects of AI. In a 2026 survey (see link below), around 54 per cent expected AI to displace existing jobs, while only 24 per cent expected it to create new jobs within their organisations. Economists have identified several potential problems:
- Structural unemployment: workers in industries that are in decline may struggle to find employment requiring their existing skills.
- Increased income inequality: there may be a growing income disparity between highly skilled and less-skilled workers.
- Growing market power: the largest technology firms that own the most advanced AI systems may see their market power grow further creating dominance in certain areas.
- Regional inequalities: AI-related investment may become concentrated in particular cities and countries, exacerbating regional inequalities within and between countries.
- Pressure on governments: to address issues of structural unemployment and increasing inequality, governments may be forced to expand retraining and social-support programmes.
AI and catastrophic risk
 Most economic discussion around AI focuses on employment and productivity. However, some researchers argue that the most significant risks from AI may be much broader.
Economists distinguish between ordinary risks and catastrophic risks. Catastrophic risks involve events with a very low probability of occurring but potentially enormous consequences. Examples include nuclear accidents, pandemics and certain climate-related disasters.
AI raises similar concerns. Advanced AI systems could potentially be used to conduct cyberattacks, spread misinformation, disrupt critical infrastructure or support the development of dangerous technologies. Some researchers have even suggested that highly advanced AI systems could pose an existential risk to humanity if they become sufficiently powerful and are not properly controlled.
This became a widely discussed topic in the media in September 2026 following the resignation of an employee, Jacob Coxon, from AI firm, Anthropic. He said that people working on AI were ‘genuinely frightened’ about how quickly AI was advancing and what it might mean for the future of humanity. He said:
I believe that if we don’t slow down at the current rate of progress, there is a strong chance that we could all die in the immediate future.
Other researchers have raised similar concerns and there have since been calls from some of the biggest AI companies for regulation of AI to prevent this.
The policy debate and CBA
 All of this creates a challenge for cost-benefit analysis. Suppose AI generates trillions of pounds of economic benefits. But, if there is also a very small probability of catastrophic harm, how should policymakers weigh up the two?
Traditional cost-benefit analysis values risk by multiplying the size of a potential outcome by its probability. However, this approach becomes problematic when both the probability and the consequences are highly uncertain. The risks may be extremely difficult to estimate, while the potential costs could be vast and affect future generations. For this reason, governments and firms increasingly use scenario analysis, stress testing and AI safety assessments to evaluate potential risks. These approaches attempt to prepare for extreme outcomes rather than relying solely on probability calculations.
Supporters of AI argue that technological progress has historically improved living standards and that restricting AI too heavily could reduce innovation and economic growth. Critics argue that uncertainty about potentially catastrophic outcomes justifies a more cautious approach.
The debate therefore extends beyond labour economics to the wider issue of managing catastrophic risk. As with nuclear power or climate change, policymakers must decide how much risk society is willing to accept in exchange for potentially large economic benefits.
Articles
- Why are there concerns AI could threaten humanity, and how real are they?
BBC News, Liv McMahon (17/9/26)
- Two dire warnings, one from Terence Tao, the other from someone who just quit Anthropic
Marcus on AI, Gary Marcus (9/9/26)
- AI insiders fear extinction. Security experts see a familiar fight
Scientific American, Peter Hall (11/9/26)
- US rejects pleas from OpenAI, Anthropic for global AI standards
BBC News, Kali Hays (24/9/26)
- How would AI actually kill all humans? Here are the top 5 scenarios
The Conversation, Toby Walsh (22/9/26)
- Who’s Who In The Fight Over Whether AI Will Kill Us
Forbes, Andréa Morris (24/9/26)
- Why this AI doomsday warning from former Anthropic researcher broke through
The Guardian, Blake Montgomery (15/9/26)
 As AI behavior raises concerns, ex-researcher Jacob Coxon warns what may lie ahead
PBS News
- ‘A setup’: Elon Musk fuels wild theory about Anthropic whistleblower Jacob Coxon
ABC News, Harrison Christian (11/9/26)
- Sam Altman, Dario Amodei urge UN Security Council to adopt international AI standards
CNN, Hadas Gold (24/9/26)
- Not everyone thinks AI will kill us all
CNN, Hadas Gold and Clare Duffy (24/9/26)
- The turbulent AI era is here. The choices we make now are critical.
Gates Notes, Bill Gates (26/8/26)
Reports
Questions
- How might AI increase productivity while also causing unemployment in some sectors? Which sectors are likely to be affected the most?
- Why is it difficult to estimate the costs and benefits of advanced AI?
- Assume that a disaster is estimated to cost society £1000 billion (£1 000 000 000 000). The chances of the disaster occurring are said to be minute, however. Estimates vary from a probability of one in a million to one in a billion. What estimate of this cost would you include in a cost–benefit analysis?
- Why are many low-income countries apparently prepared to accept riskier projects than are high-income ones?
- Discuss whether the greatest economic challenge posed by AI is (a) job displacement; (b) increased inequality; (c) market concentration and the power of large technology firms; or (d) catastrophic long-term risks.
- Read the article by Bill Gates, The turbulent AI era is here. The choices we make now are critical. According to him, what steps should the world take to ensure that ‘AI will be a force for good and leave everyone better off’?
 Have you noticed that many products in the supermarket seem to be getting smaller or are poorer quality, or that special offers are not as special as they used to be? When you ring customer services, does it seem that you have to wait longer than you used to? Do you now have to pay for extras that used to be free? These are all ways that producers try to pass on cost increases to consumers without rising prices. There are three broad ways in which producers try to hide inflation.
The first is called ‘shrinkflation’. It is defined as having less product in the same package or a smaller package for the same price. For example, reducing the number of chocolates in a tub, reducing the size of a can of beans, jar of coffee or block of butter, reducing the number of sheets in a toilet roll, or the length of a ride in a fairground or portion sizes in a restaurant or takeaway. A 2023 YouGov poll revealed that 75% of UK adults are either ‘very’ or ‘fairly’ concerned about shrinkflation. A similar poll in 2025 showed that this figure had increased to 80%. The product category with the greatest concerns was snack foods (e.g. crisps, confectionery items, nuts, etc.).1
The second form of hidden inflation is called ‘skimpflation’. This is defined as decreasing the quality of a product or service without lowering the price. Examples include cheaper ingredients in food or confectionery, such as using palm oil instead of butter, or reducing the cocoa content in chocolate or the meat content in sausages and pies, or package holidays reducing the quality of meals, or customer service centres or shops reducing the number of staff so that people have to wait longer on the phone or to be served.
The third is called ‘sneakflation’. This is similar to skimpflation but normally refers to reducing what you get when you pay for a service, such as a flight, by now charging for extras, such as luggage or food. Sometimes shrinkflation or skimpflation are seen as subsets of sneakflation.
 These practices have had a lot of publicity in recent months, with consumers complaining that they are getting less for their money. Many people see them as a sneaky way of passing on cost increases without raising the price. But the changes are often subtle and difficult for shoppers to spot when they are buying an item. Skimpflation especially is difficult to observe at the time of purchase. It’s only when people consume the product that they think that it doesn’t seem as good as it used to be. Even shrinkflation can be hard to spot if the package size remains the same but there is less in it, such as fewer biscuits in a tin or fewer crisps in a packet. People would have to check the weight or volume, while also knowing what it used to be.
If firms are legitimately passing on costs and are up-front about what they are doing, then most consumers would probably understand it even if they did not like it. It’s when firms do it sneakily that many consumers get upset. Also, firms may do it to increase profit margins – in other words, by reducing the size or quality beyond what is necessary to cover the cost increase.
Does the official rate of inflation take such practices into account?
 The answer is that some of the practices are taken into account – especially shrinkflation. The Office for National Statistics (ONS) accounts for shrinkflation by monitoring price changes per unit of weight or volume, rather than just the price. Data collectors track the weight, volume or count of item. When a product’s size is reduced, the ONS records this as a price increase in CPI or CPIH inflation statistics. This is known as a ‘quality adjustment’ process and allows the ONS to isolate price changes from product size changes. As CPI data from the ONS is used by the Bank of England in monitoring its 2% inflation target, it too is incorporating shrinkflation.
ONS quality adjustments are also applied to non-market public services, such as healthcare, education and policing to measure changes in service quality rather than just volume. This allows a more accurate measurement of productivity as it focuses on outcomes and user experience per pound spent rather than just focusing on costs.
Skimpflation is more difficult to monitor. The quality adjustment process may miss some quality changes and hence some skimpflation goes unrecorded. This means that the headline inflation rate might understate the true decline in purchasing power felt by consumers.
How extensive is hidden inflation?
Despite public perception, shrinkflation has a relatively small impact on the headline CPI and CPIH inflation rate in the UK because it is largely confined to certain sectors, such as bread and cereals, personal care products, meat products, and sugar, jams, syrups, chocolate & confectionery. Nevertheless, in these sectors it is particularly prevalent, especially in the packaged foodstuffs and confectionery sector. The latest research by the ONS in 2019 covered the period June 2015 to June 2017 and is shown in the following figure.2
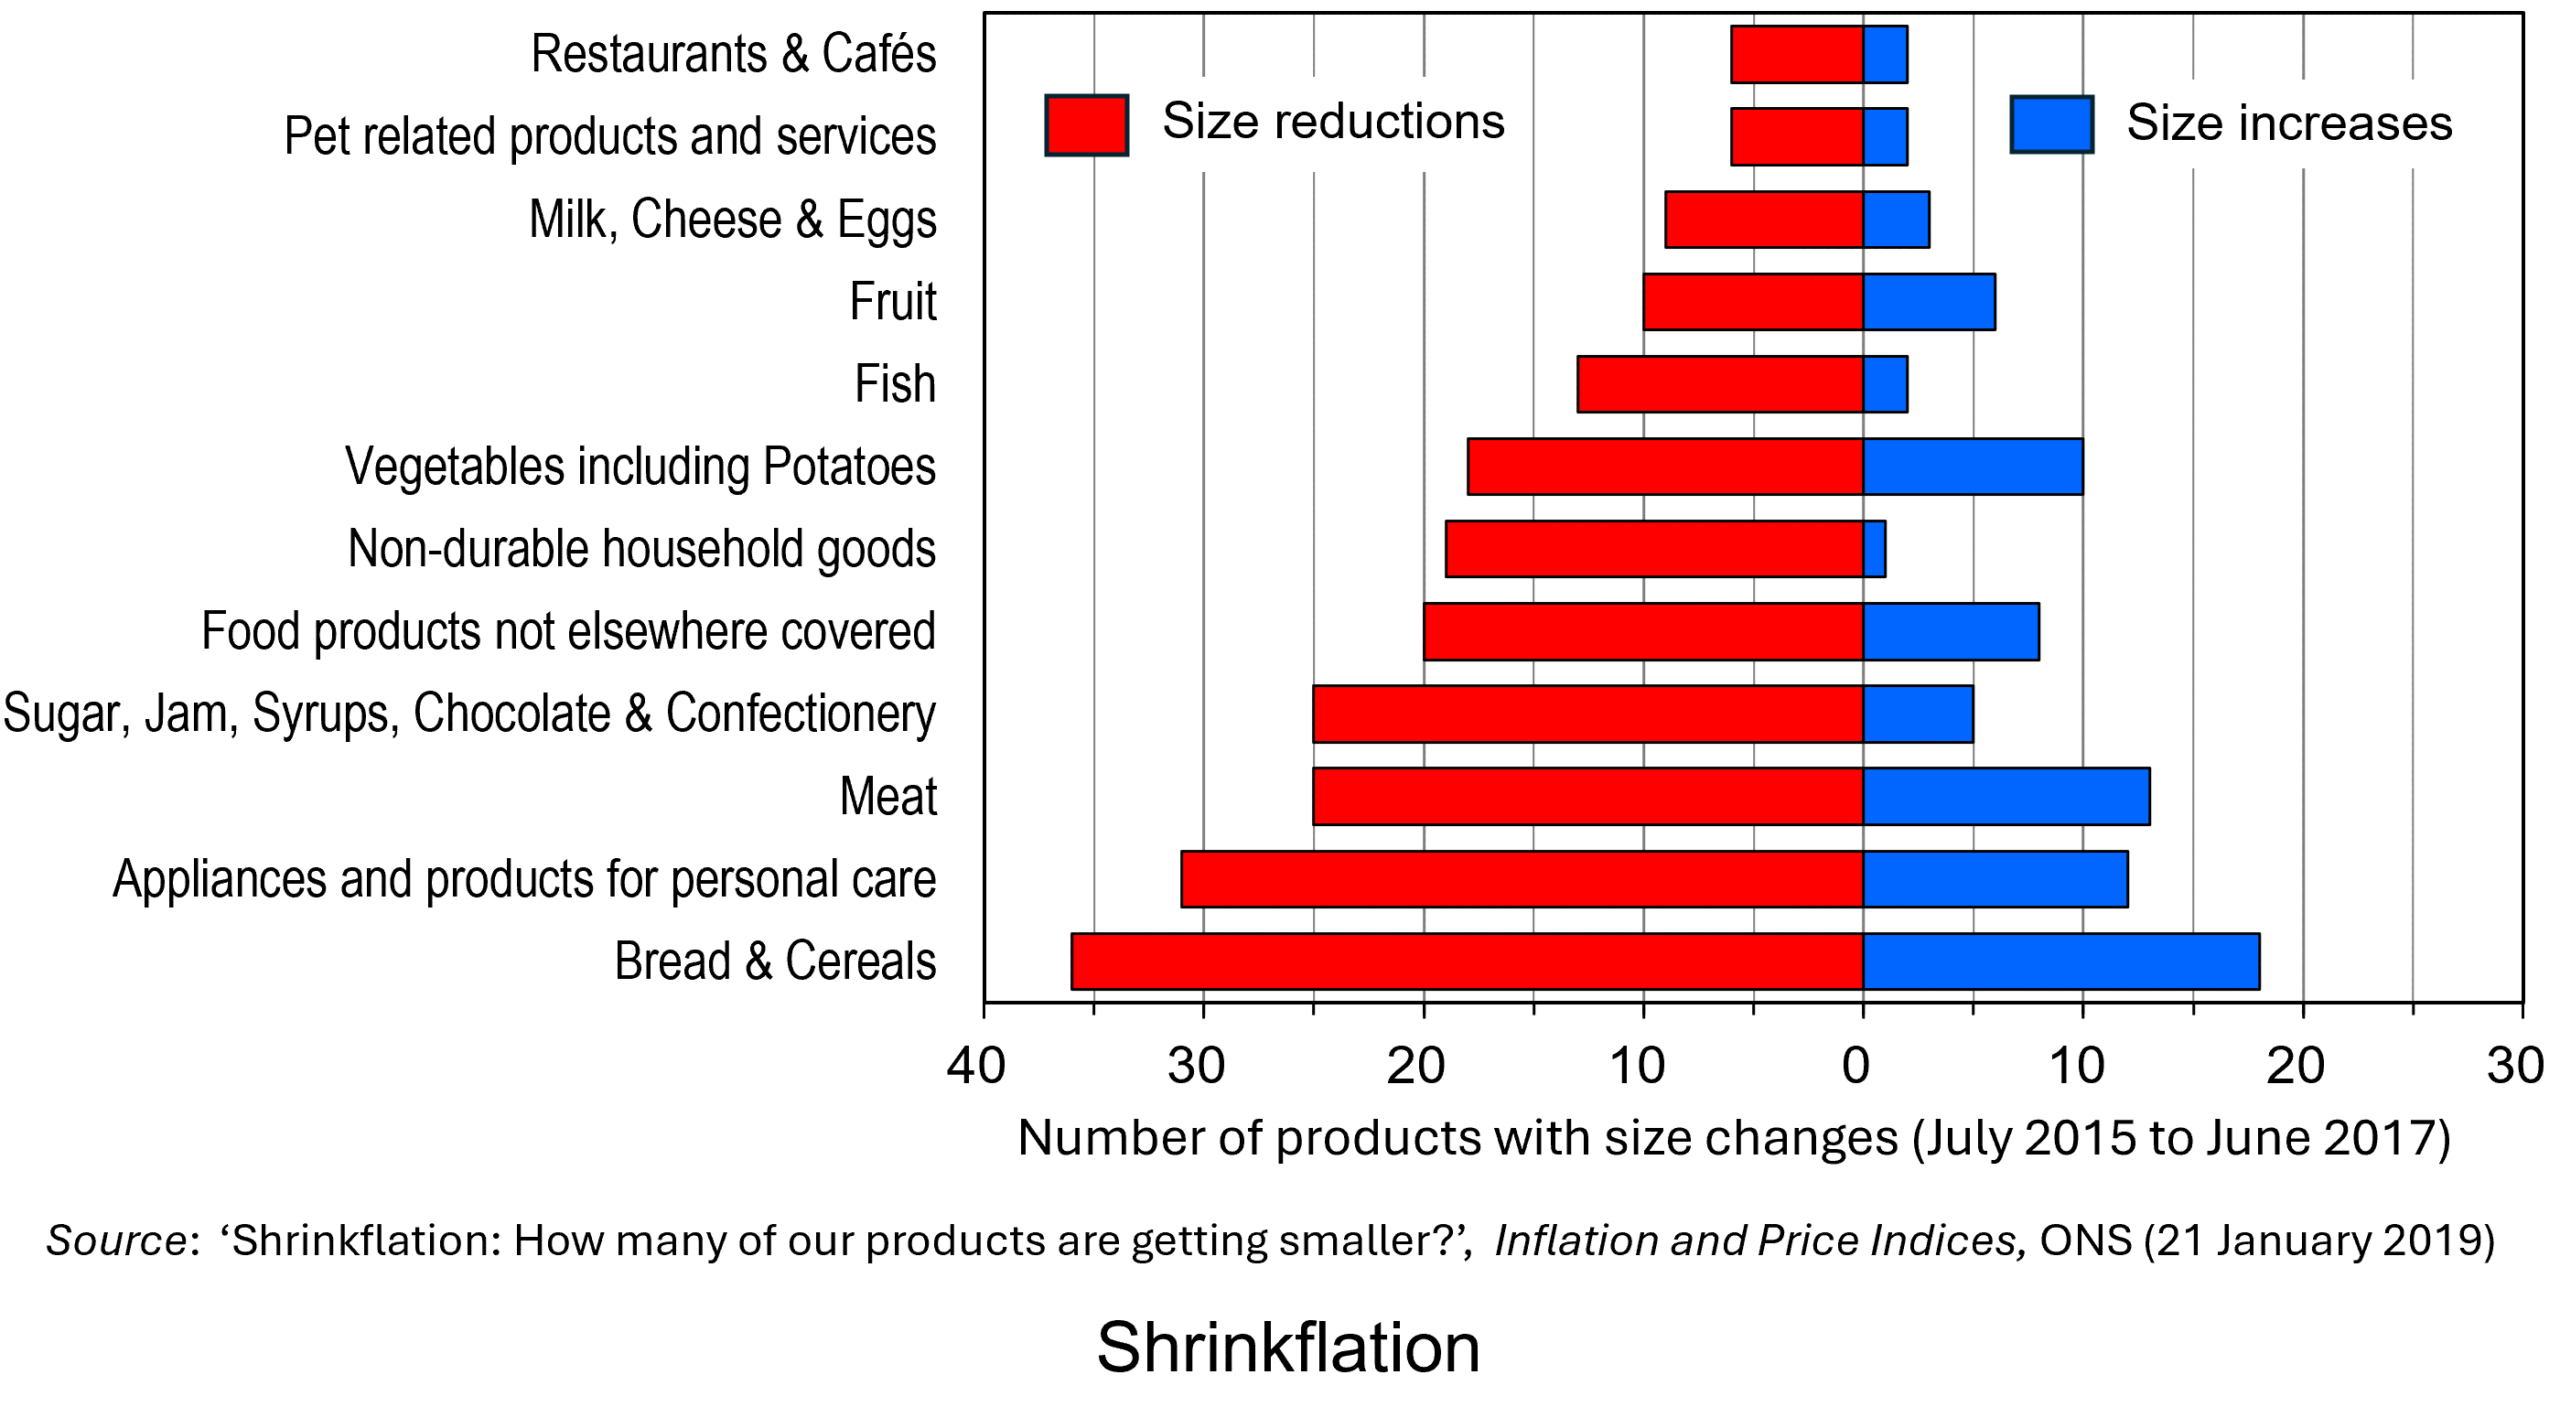
According to research in the USA by Capital One Shopping, some major brands reduced product sizes by over 30% in 2025 without reducing prices, with shrinkflation averaging 14.8% among selected national grocery brands.3 Shrinkflation had been observed by 74% of Americans at their grocery store. Of these, 81% took some kind of action as a result, with 48% abandoning a brand. Nevertheless, across all products, shrinkflation accounts for quite a small percentage of any overall price rises.
A US Government Accountability Office (GAO) report found that shrinkflation accounted for less than 1/10 of a percentage point of the 34.5% increase in overall consumer prices from 2019 to 2024.4 The reason is that the items that were downsized comprised a small percentage of goods and services. Indeed, many goods and services, such as housing, cannot be downsized in the same way that household products can.
Nevertheless, with consumer budgets being squeezed by the inflation that followed the pandemic and the Russian invasion of Ukraine, hidden inflation has become more prevalent in many countries and an increasing concern of consumers.
References
- Shrinkflation concern rises in 2025, but fewer Britons are changing shopping habits
YouGov (15/8/25)
- Shrinkflation: How many of our products are getting smaller?
Office for National Statistics (21/1/19)
- Shrinkflation Statistics
Capital One Shopping (30/12/25)
- What is “Shrinkflation,” And How Has It Affected Grocery Store Items Recently?
U.S. Government Accountability Office (12/8/25)
Videos
Articles
- Shrinkflation: How many of our products are getting smaller?
Office for National Statistics (21/1/19)
- Shrinkflation: Inflation hiding in plain sight
Britannica Money, Doug Ashburn (21/7/25)
- Shrinkflation: the brands charging you more for less
Which?, Ellie Simmonds (28/10/25)
- 7 Surprising Ways Inflation Is Still Rising Even as Prices Slow This Year
SavingAdvice.com, Teri Monroe (3/2/26)
- 22 Real-Life Examples Of Shrinkflation That People Have Spotted In The Last Few Weeks That Are Honestly Infuriating
BuzzFeed, Megan Liscomb (10/12/25)
- Shrinkflation: smaller products hurt some households more than others – and can be bad for business
The Conversation, Erhan Kilincarslan (14/1/26)
- Shoppers brand the UK “a disgrace” as Cadbury Mini Egg prices rise by 105% on pre-pandemic levels
Food Manufacture, Thomas West (6/1/26)
- This article is more than 3 months old Shrinkflation hits everyday staples, piling more pressure on households
The Guardian, Sarah Marsh and Sarah Butler (28/12/25)
- Shrinkflation isn’t slowing down — It’s just getting harder to spot
ConsumerAffairs, Kyle James (13/1/26)
- Shrinkflation – are brands and supermarkets required to inform consumers if a product has been reduced in size or quantity but the packaging looks the same?
CMS Law-Now, Loïc de Hults and Tom Heremans (25/9/25)
- Study reveals shrinking package sizes hide significant food inflation
Phys.org, Aaron Kupec (28/1/26)
Journal Article
Questions
- If shrinkflation, when included in CPI statistics, accounts for such a small percentage of inflation, why are people so concerned about it?
- From a company’s perspective, is it a good idea to engage in (a) shrinkflation; (b) skimpflation?
- Go round you local supermarket and identify examples of shrinkflation and skimpflation.
- How are various EU countries attempting to inform consumers of shrinkflation?
- Why is skimpflation often harder to detect than shrinkflation?
- Give some other examples of sneakflation in the provision of services.
- How could behavioural economists help firms decide whether or how to engage in shrinkflation or skimpflation?
 When I worked as a professional economist at HM Treasury and later the Council of Mortgage Lenders (now part of UK Finance), I would regularly brief on the state of the affordability of housing, with a particular focus on the owner-occupied market. That was back in the late 1990s. Fast forward a quarter of a century and I recognise not only how much I have aged but also how deep-rooted and long-standing the affordability problem is.
It is perhaps not surprising that in her first speech as the new Chancellor of the Exchequer, Rachel Reeves, referenced directly the housing market and the need to address supply-side issues. She has set a target of one and a half million new homes built over the next five years.
It is therefore timely to revisit the trends in house prices across the UK. By applying the distinction between nominal and real values we get a very clear sense of the deteriorating affordability of housing.
Nominal house price patterns
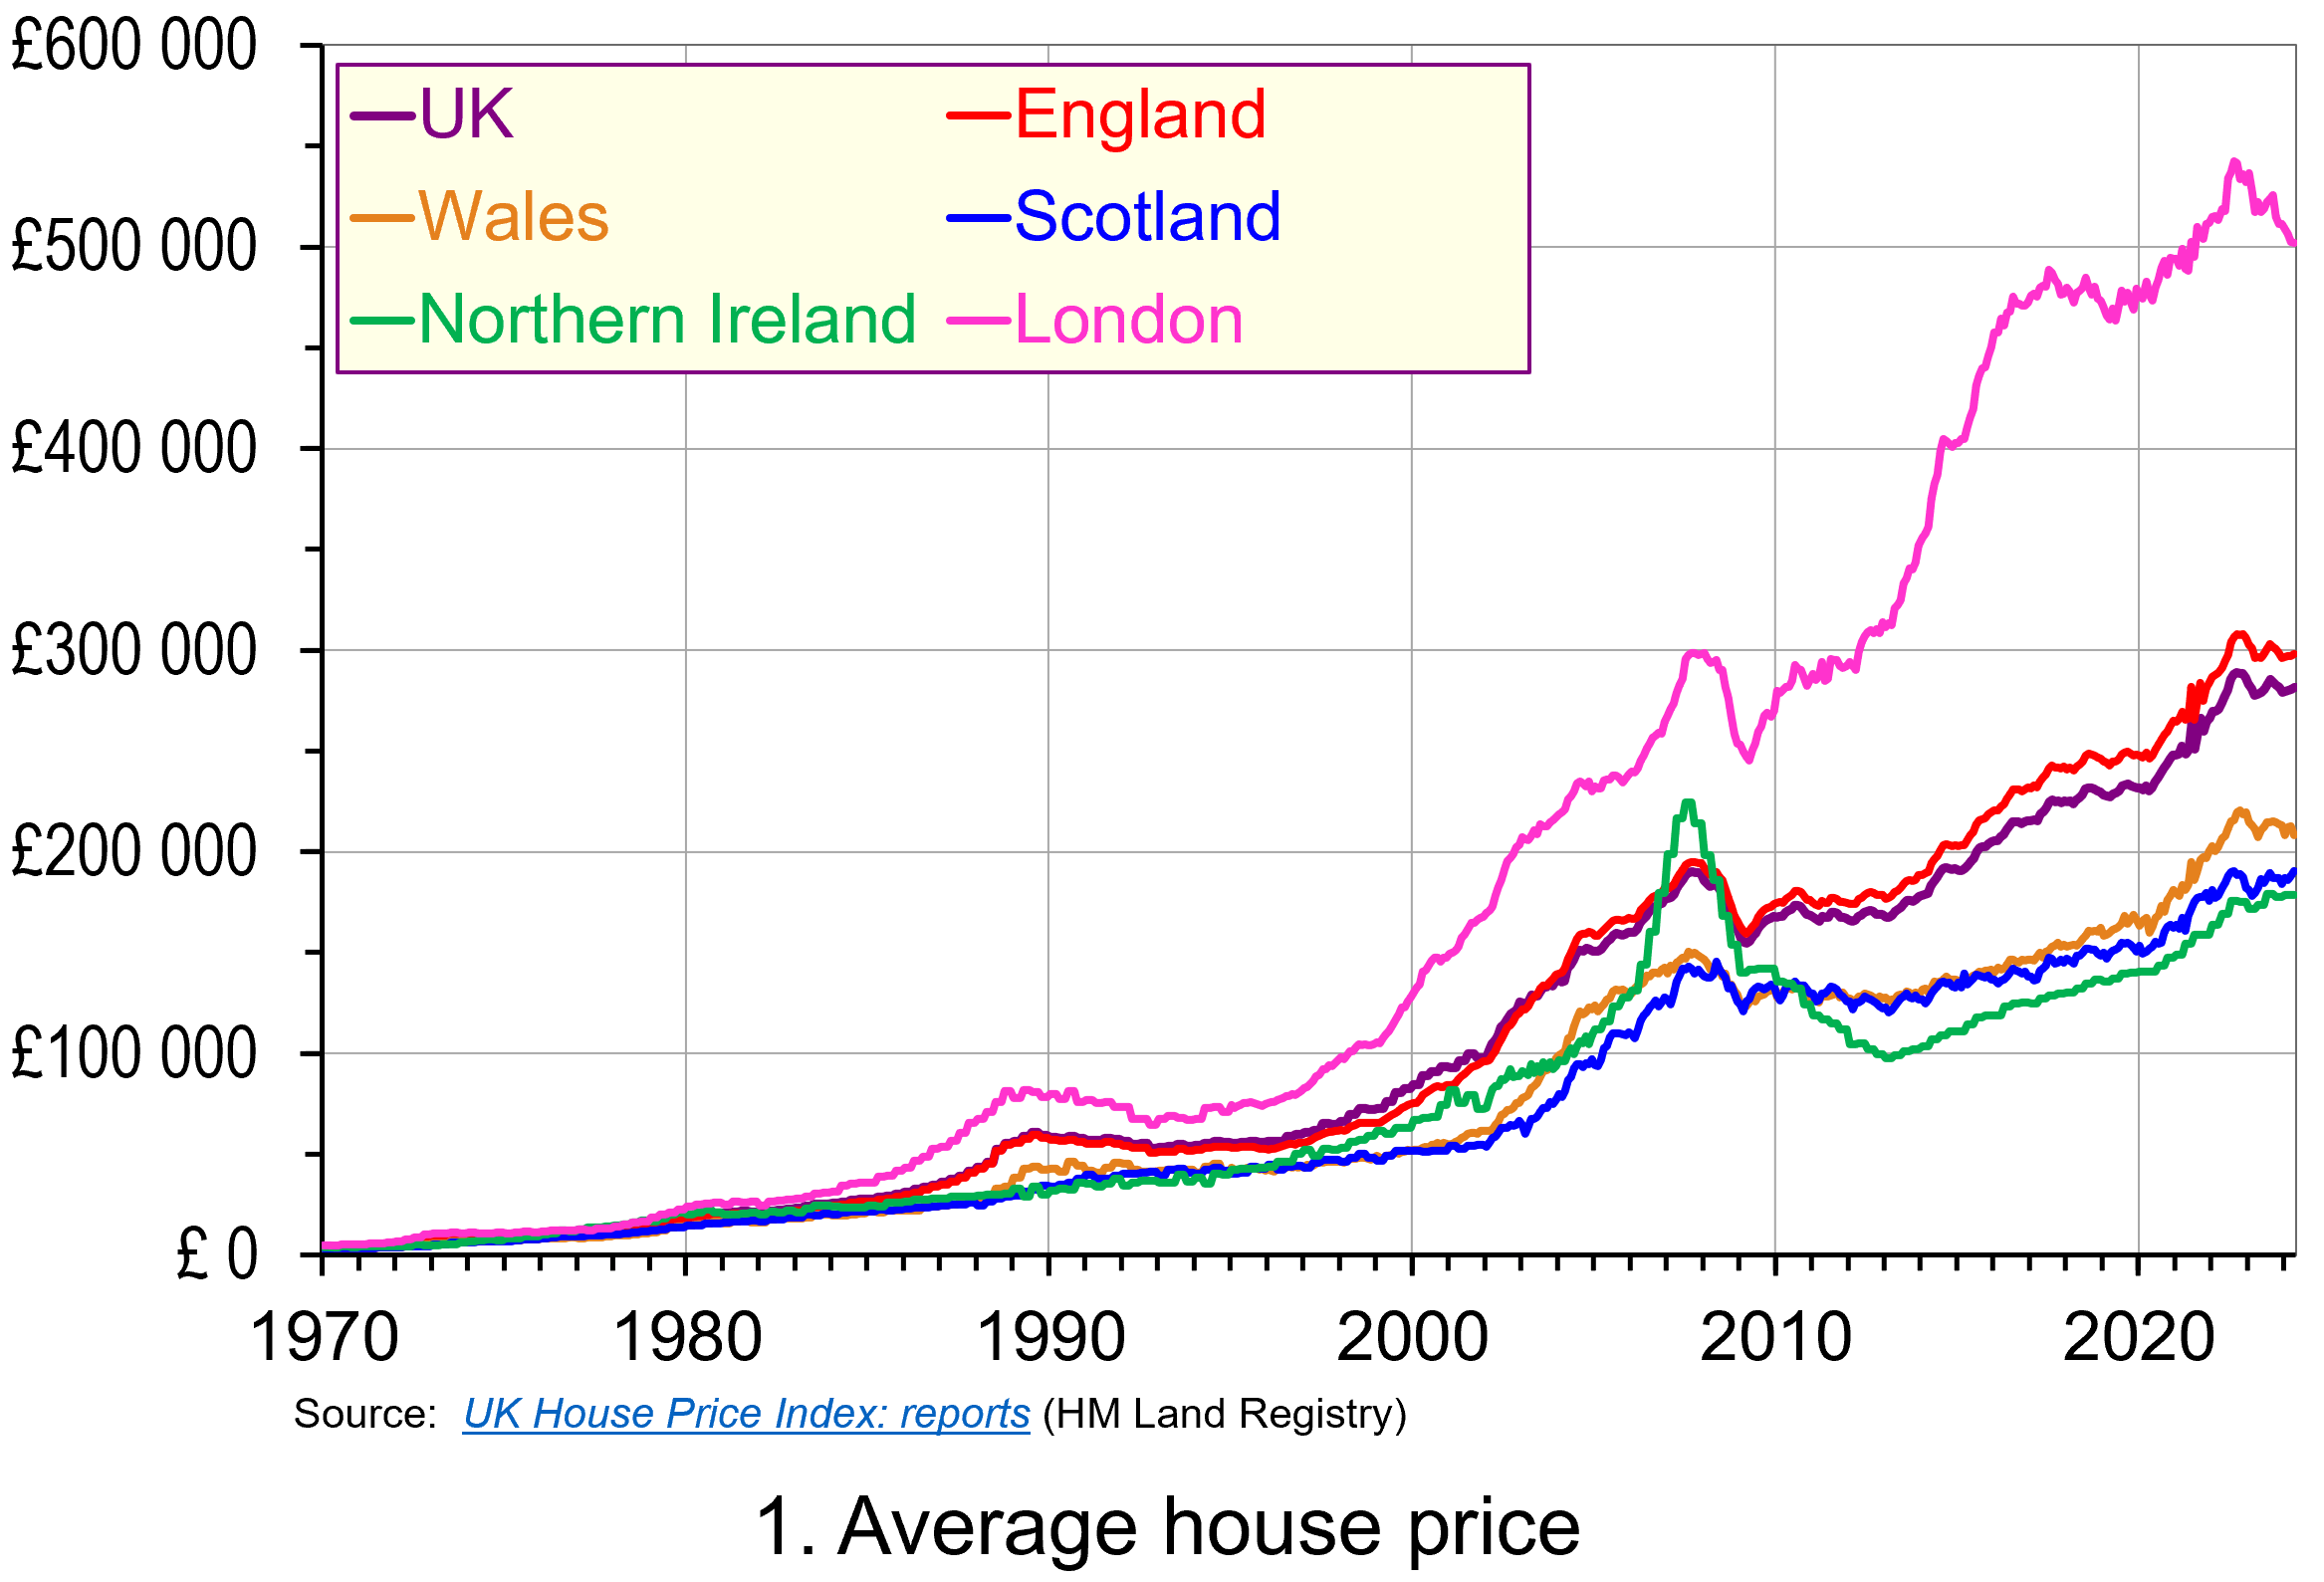 The average UK actual or nominal house price in April 2024 was £281 000. As Chart 1 shows, this masks considerable differences across the UK. In England the average price was £298 000 (105 per cent of the UK average), though this is heavily skewed by London where the average price was £502 000 (178 per cent of the UK average). Meanwhile, in Scotland it was £190 000 (68 per cent of the UK average), in Wales £208 000 (74 per cent of the UK average) and in Northern Ireland it was £178 000 (74 per cent of the UK average). (Click here to download a PowerPoint copy of the chart.)
A simple comparison of the average house price in April 2024 with January 1970 reveals a 72-fold increase in the UK, an 80-fold increase in England, including a 101-fold increase in London, a 65-fold increase in Wales, a 59-fold increase in Scotland and a 45-fold increase in Northern Ireland. Whilst these figures are sensitive to the particular period over which we choose to measure, there is little doubting that upward long-term trend in house prices.
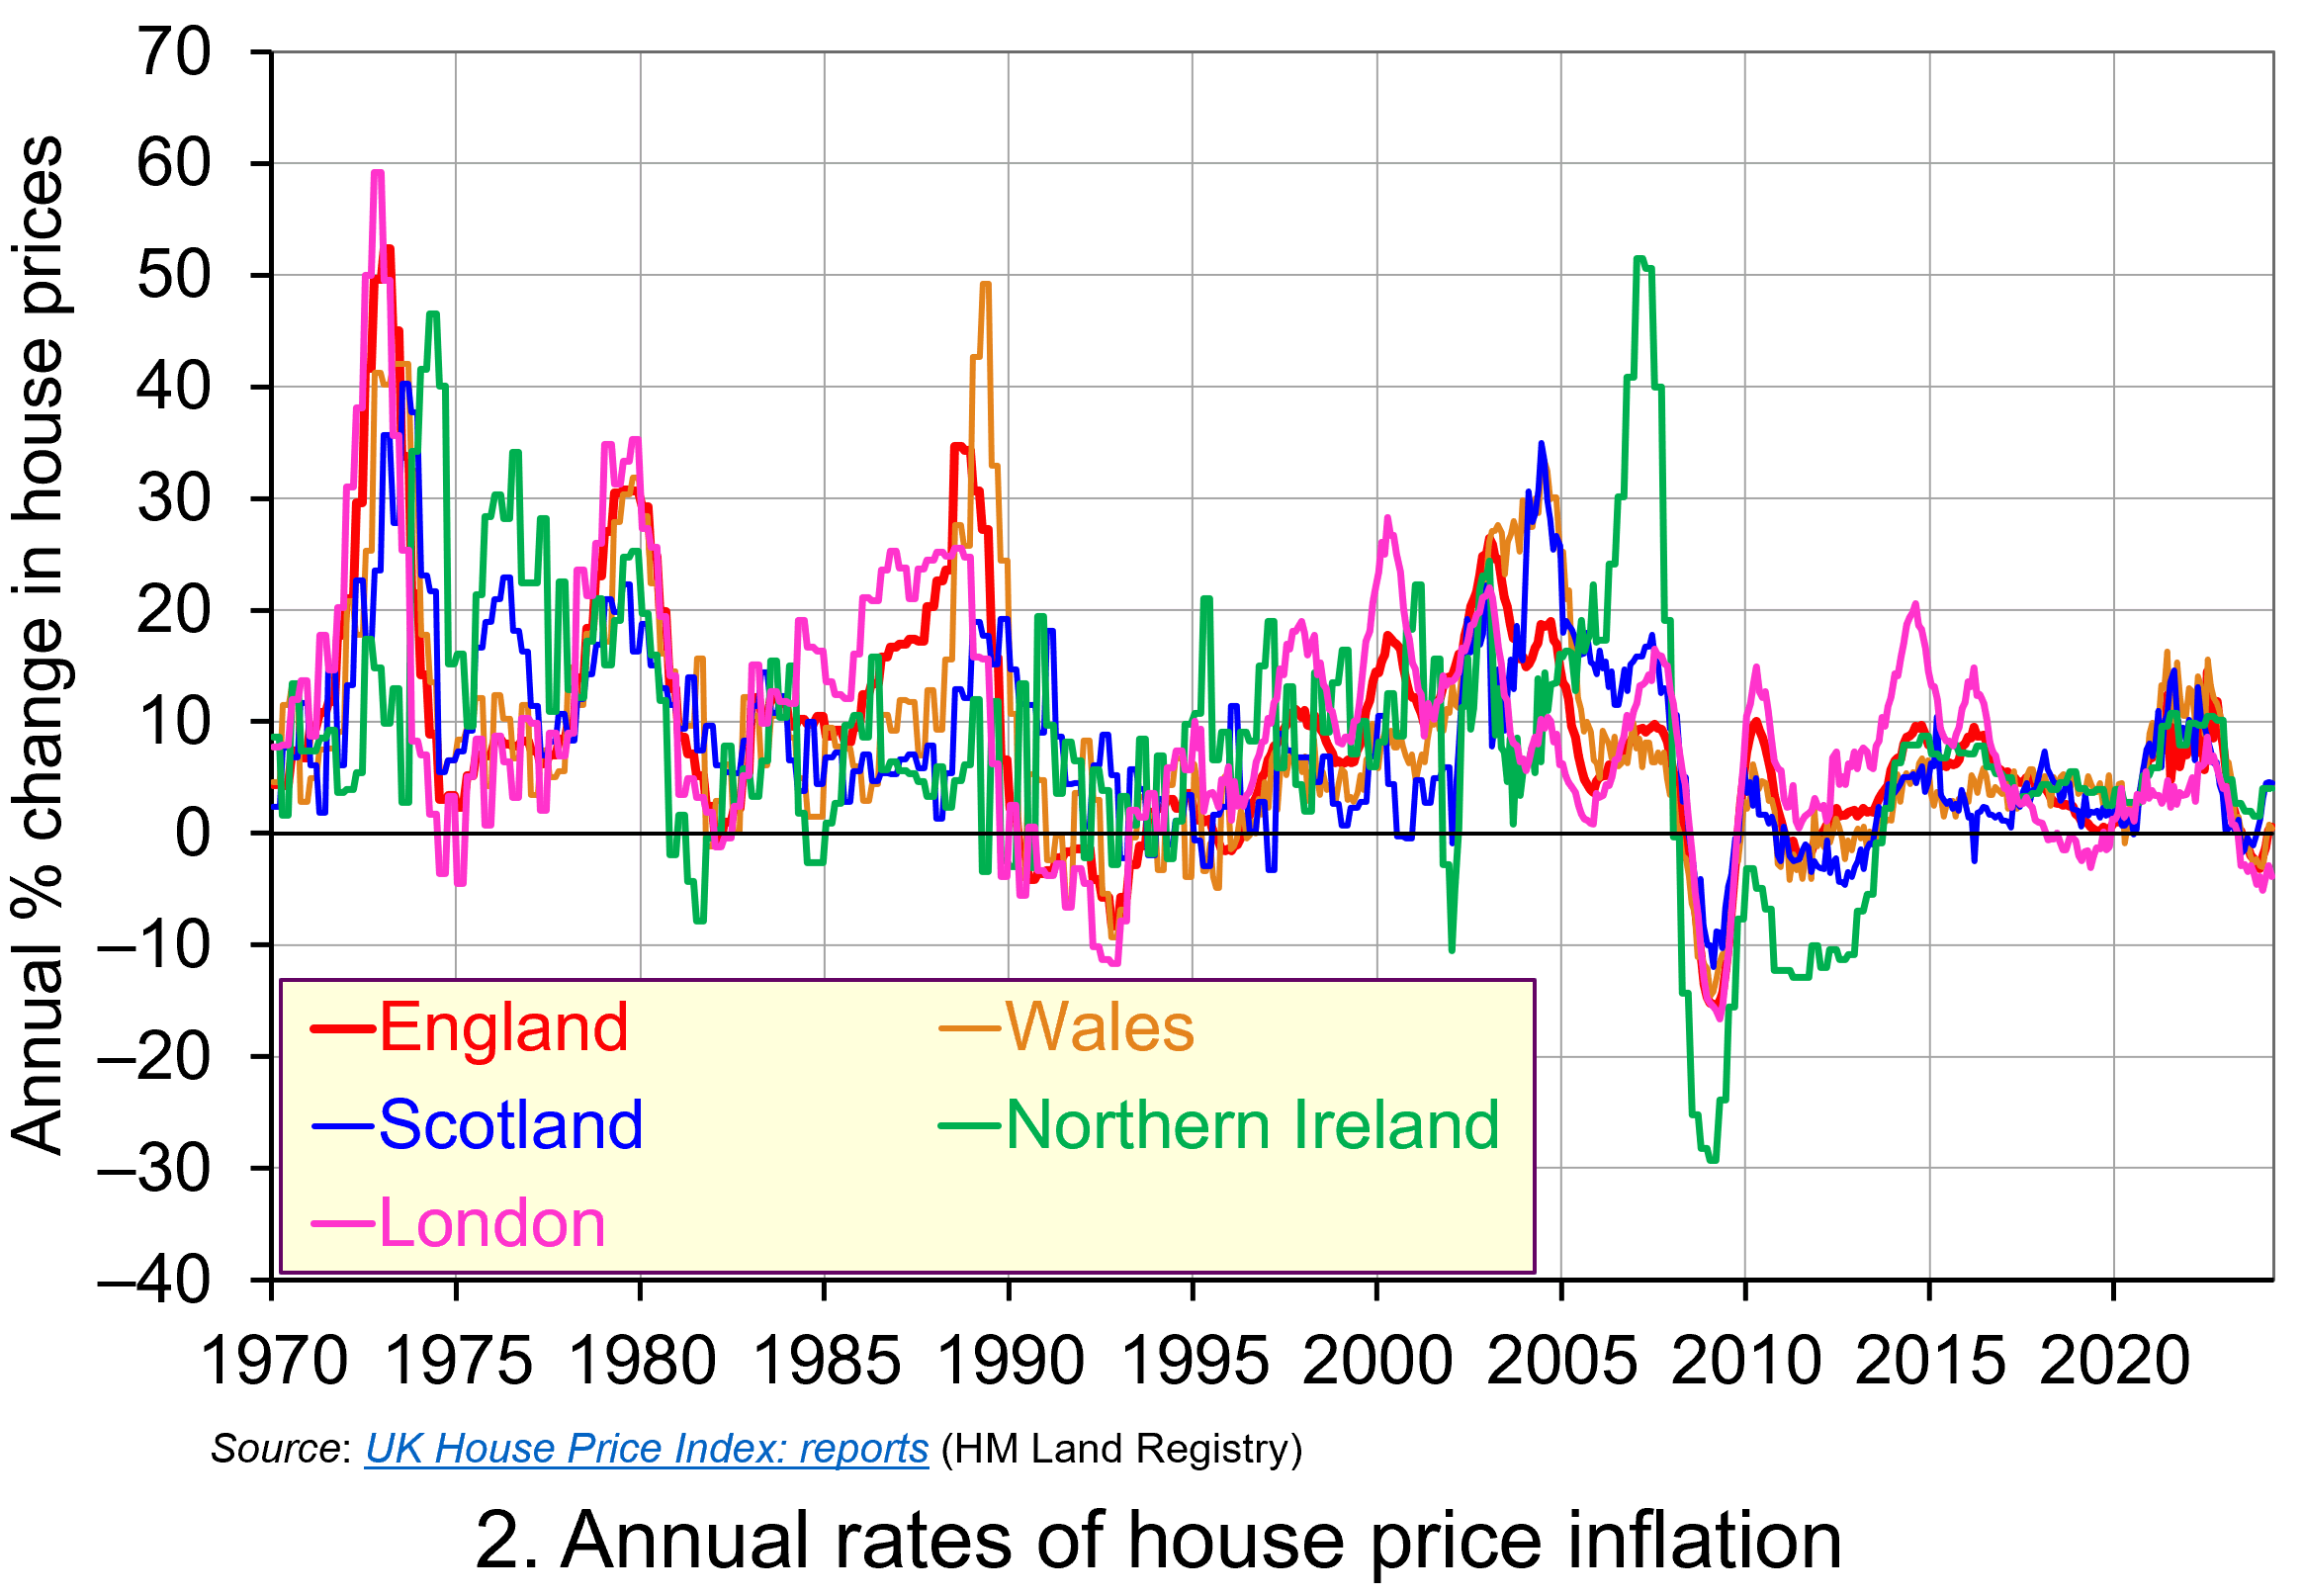 Whilst nominal prices trend upwards over time, the short-term rates of increase are highly volatile. This can be seen from an inspection of Chart 2, which shows the annual rates of increase across the four nations of the UK, as well as for London. This is evidence of frequent imbalances between the flows of property on to the market to sell (instructions to sell) and the number of people looking to buy (instructions to buy). An increase in instructions to buy (housing demand) relative to those to sell (housing supply) puts upward pressure on prices; an increase in the number of instructions to sell (housing supply) relative to those to buy (housing demand) puts downward pressure on prices. (Click here to download a PowerPoint copy of the chart.)
Chart 2 nicely captures the recent slowdown in the housing market. The inflationary shock that began to take hold in 2021 led the Bank of England to raise Bank Rate on 15 occasions – from 0.25 per cent in December 2021 to 5.25 per cent in August 2023 (which remains the rate at the time of writing, but could be cut at the next Bank of England meeting on 1 August 2024). Higher Bank Rate has pushed up mortgage rates, which has contributed to an easing of housing demand. Demand has also been dampened by weak growth in the economy, higher costs of living and fragile consumer confidence. The result has been a sharp fall in the rate of house price inflation, with many parts of the UK experiencing house price deflation. As the chart shows, the rate of deflation has been particularly pronounced and protracted in London, with house prices in January 2024 falling at an annual rate of 5.1 per cent.
Real house price patterns
Despite the volatility in house prices, such as those of recent times, the longer-term trend in house prices is nonetheless upwards. To understand just how rapidly UK house prices have grown over time, we now consider their growth relative to consumer prices. This allows us to analyse the degree to which there has been an increase in real house prices.
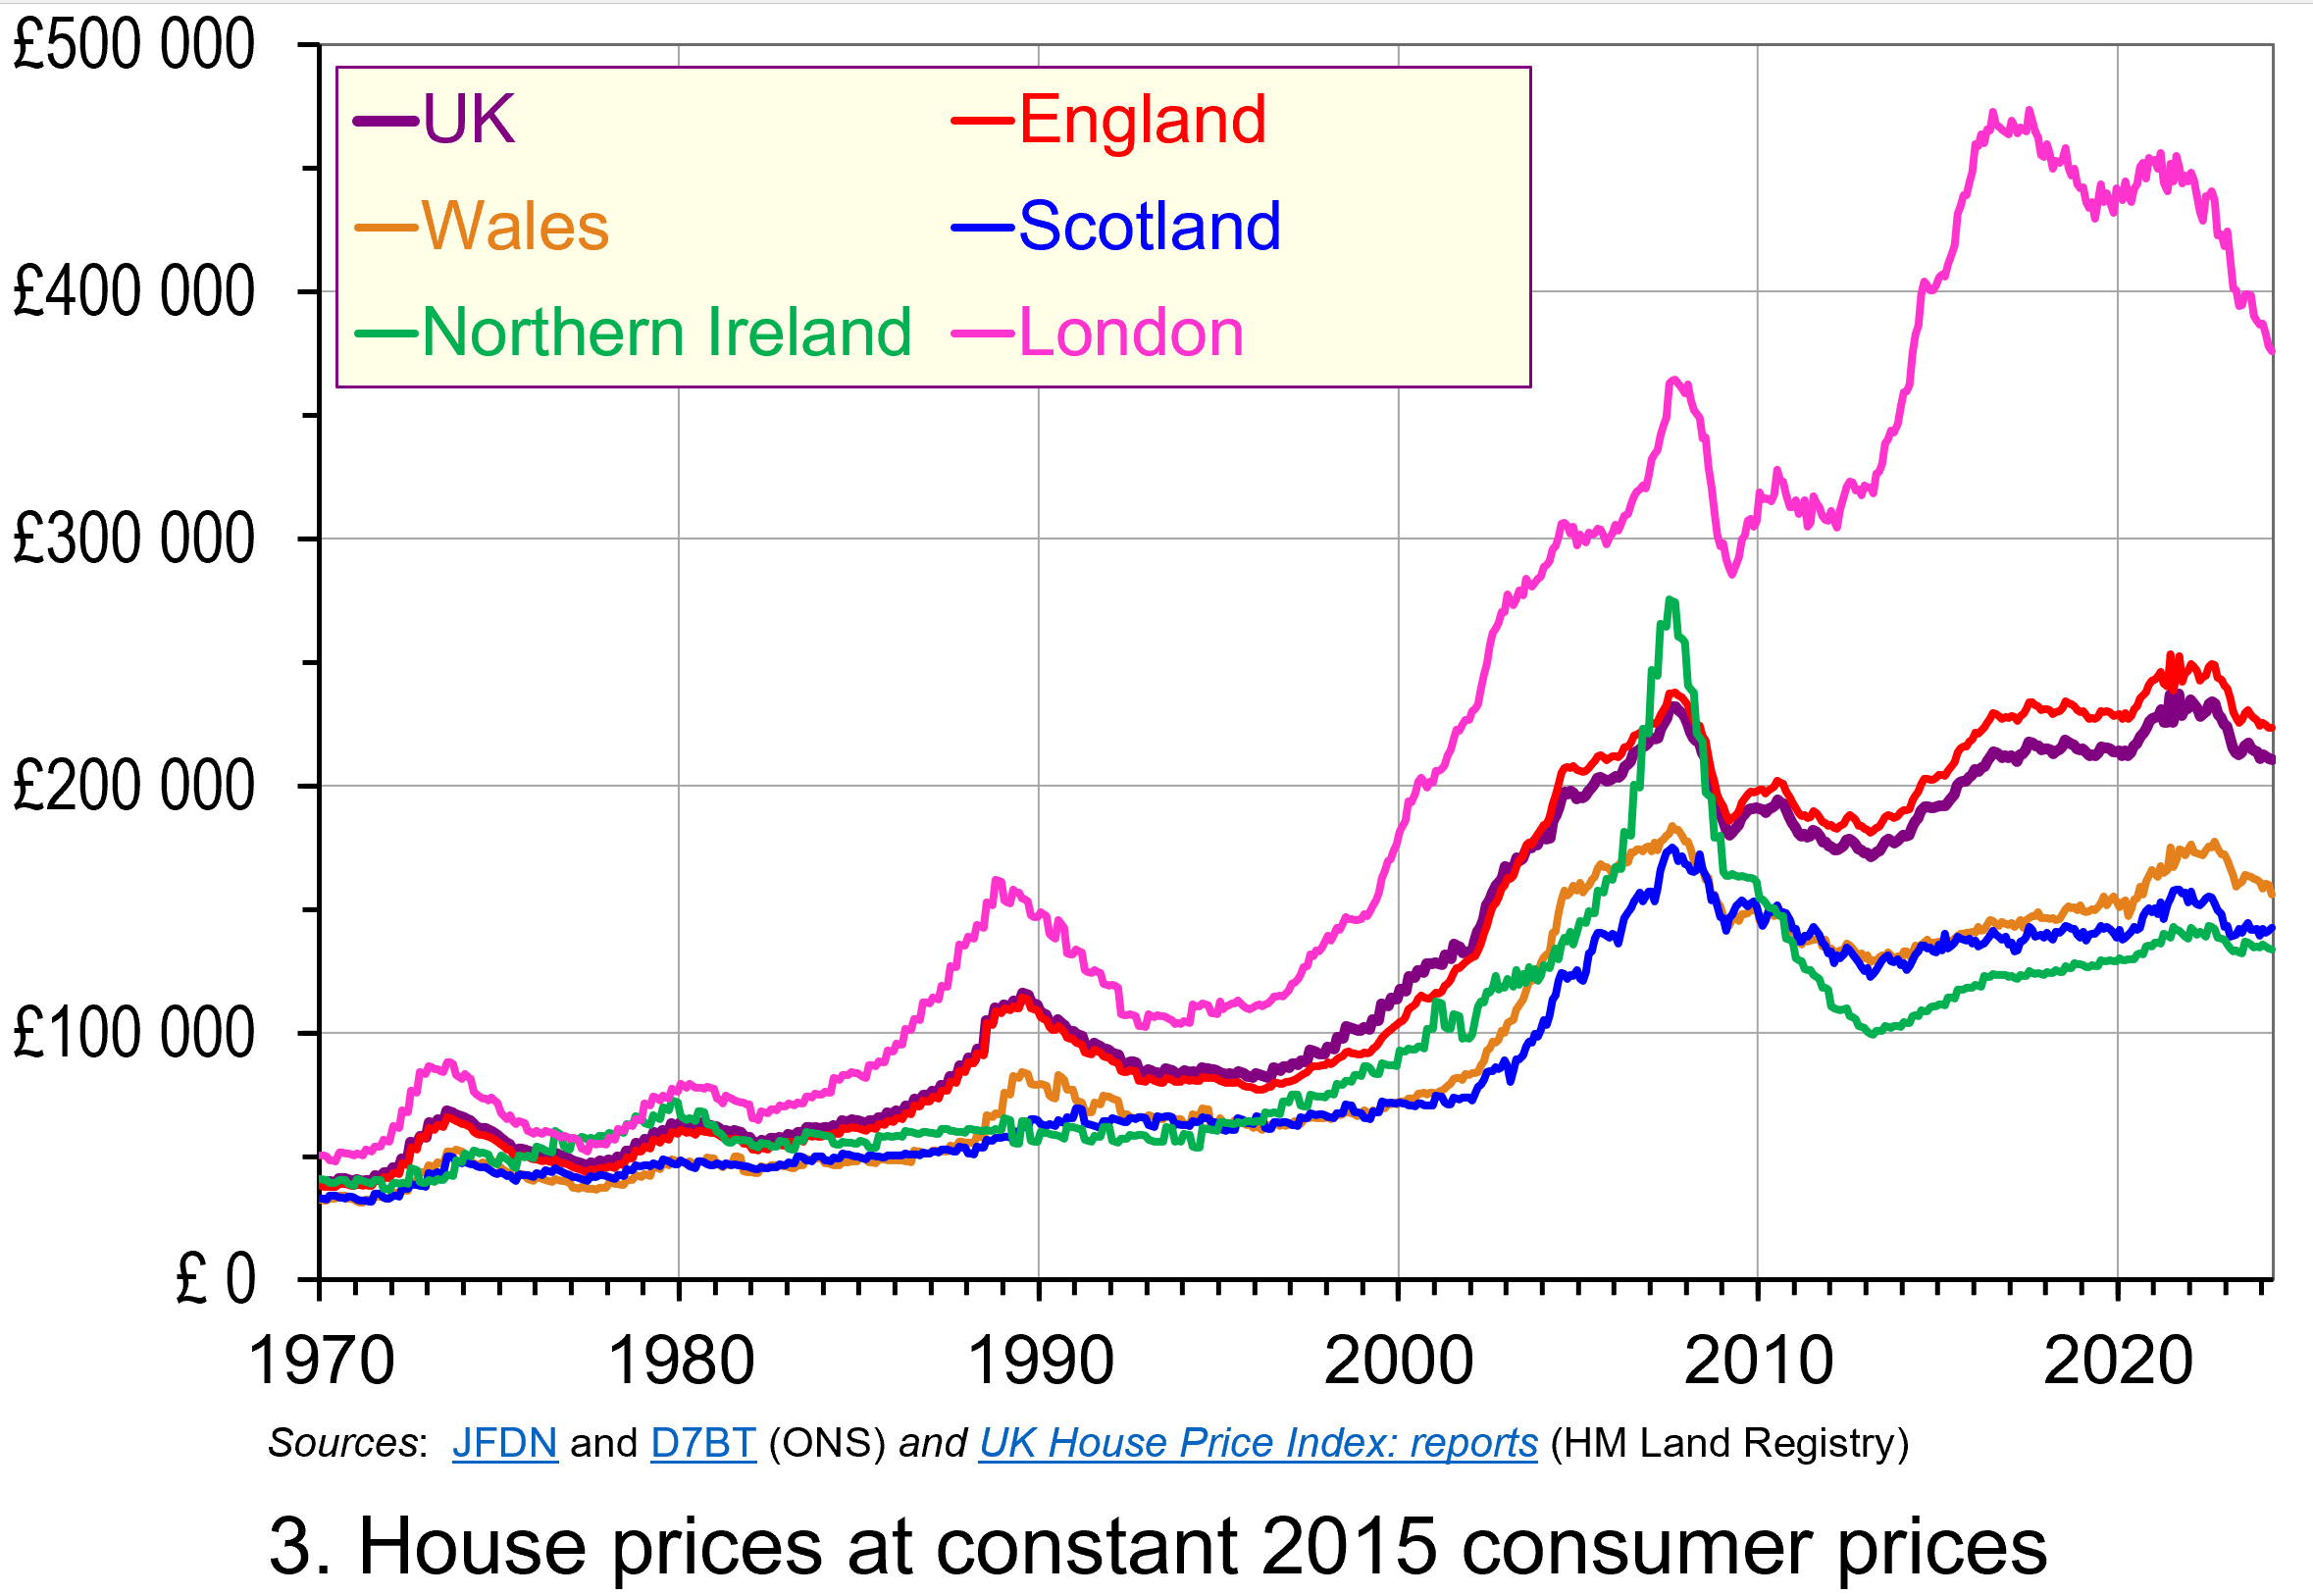 To calculate real or inflation-adjusted house prices, we deflate nominal house prices by the Consumer Prices Index (CPI). Chart 3 shows the resulting real house prices series across the UK as if consumer prices were fixed at 2015 levels.
The key message here is that over the longer-term we cannot fully explain the growth in actual (nominal) house prices by the growth in consumer prices. Rather, we see real increases in house prices. Inflation-adjusted UK house prices were 5.3 times higher in April 2024 compared to January 1970. For England the figure was 5.9 times, Wales 4.8 times, Scotland 4.3 times and for Northern Ireland 3.3 times. In London, inflation-adjusted house prices were 7.4 times higher. (Click here to download a PowerPoint copy of the chart.)
As we saw with nominal house prices, the estimated long-term increase in real house prices is naturally sensitive to the period over which we measure. For example, the average real UK house price in August 2022 was 5.8 times higher than in January 1970, while in London they were 8.7 times higher. But the message is clear – the long-term increase is not merely nominal, reflecting increasing prices generally, but is real, reflecting pressures that are increasing house prices relative to general price levels.
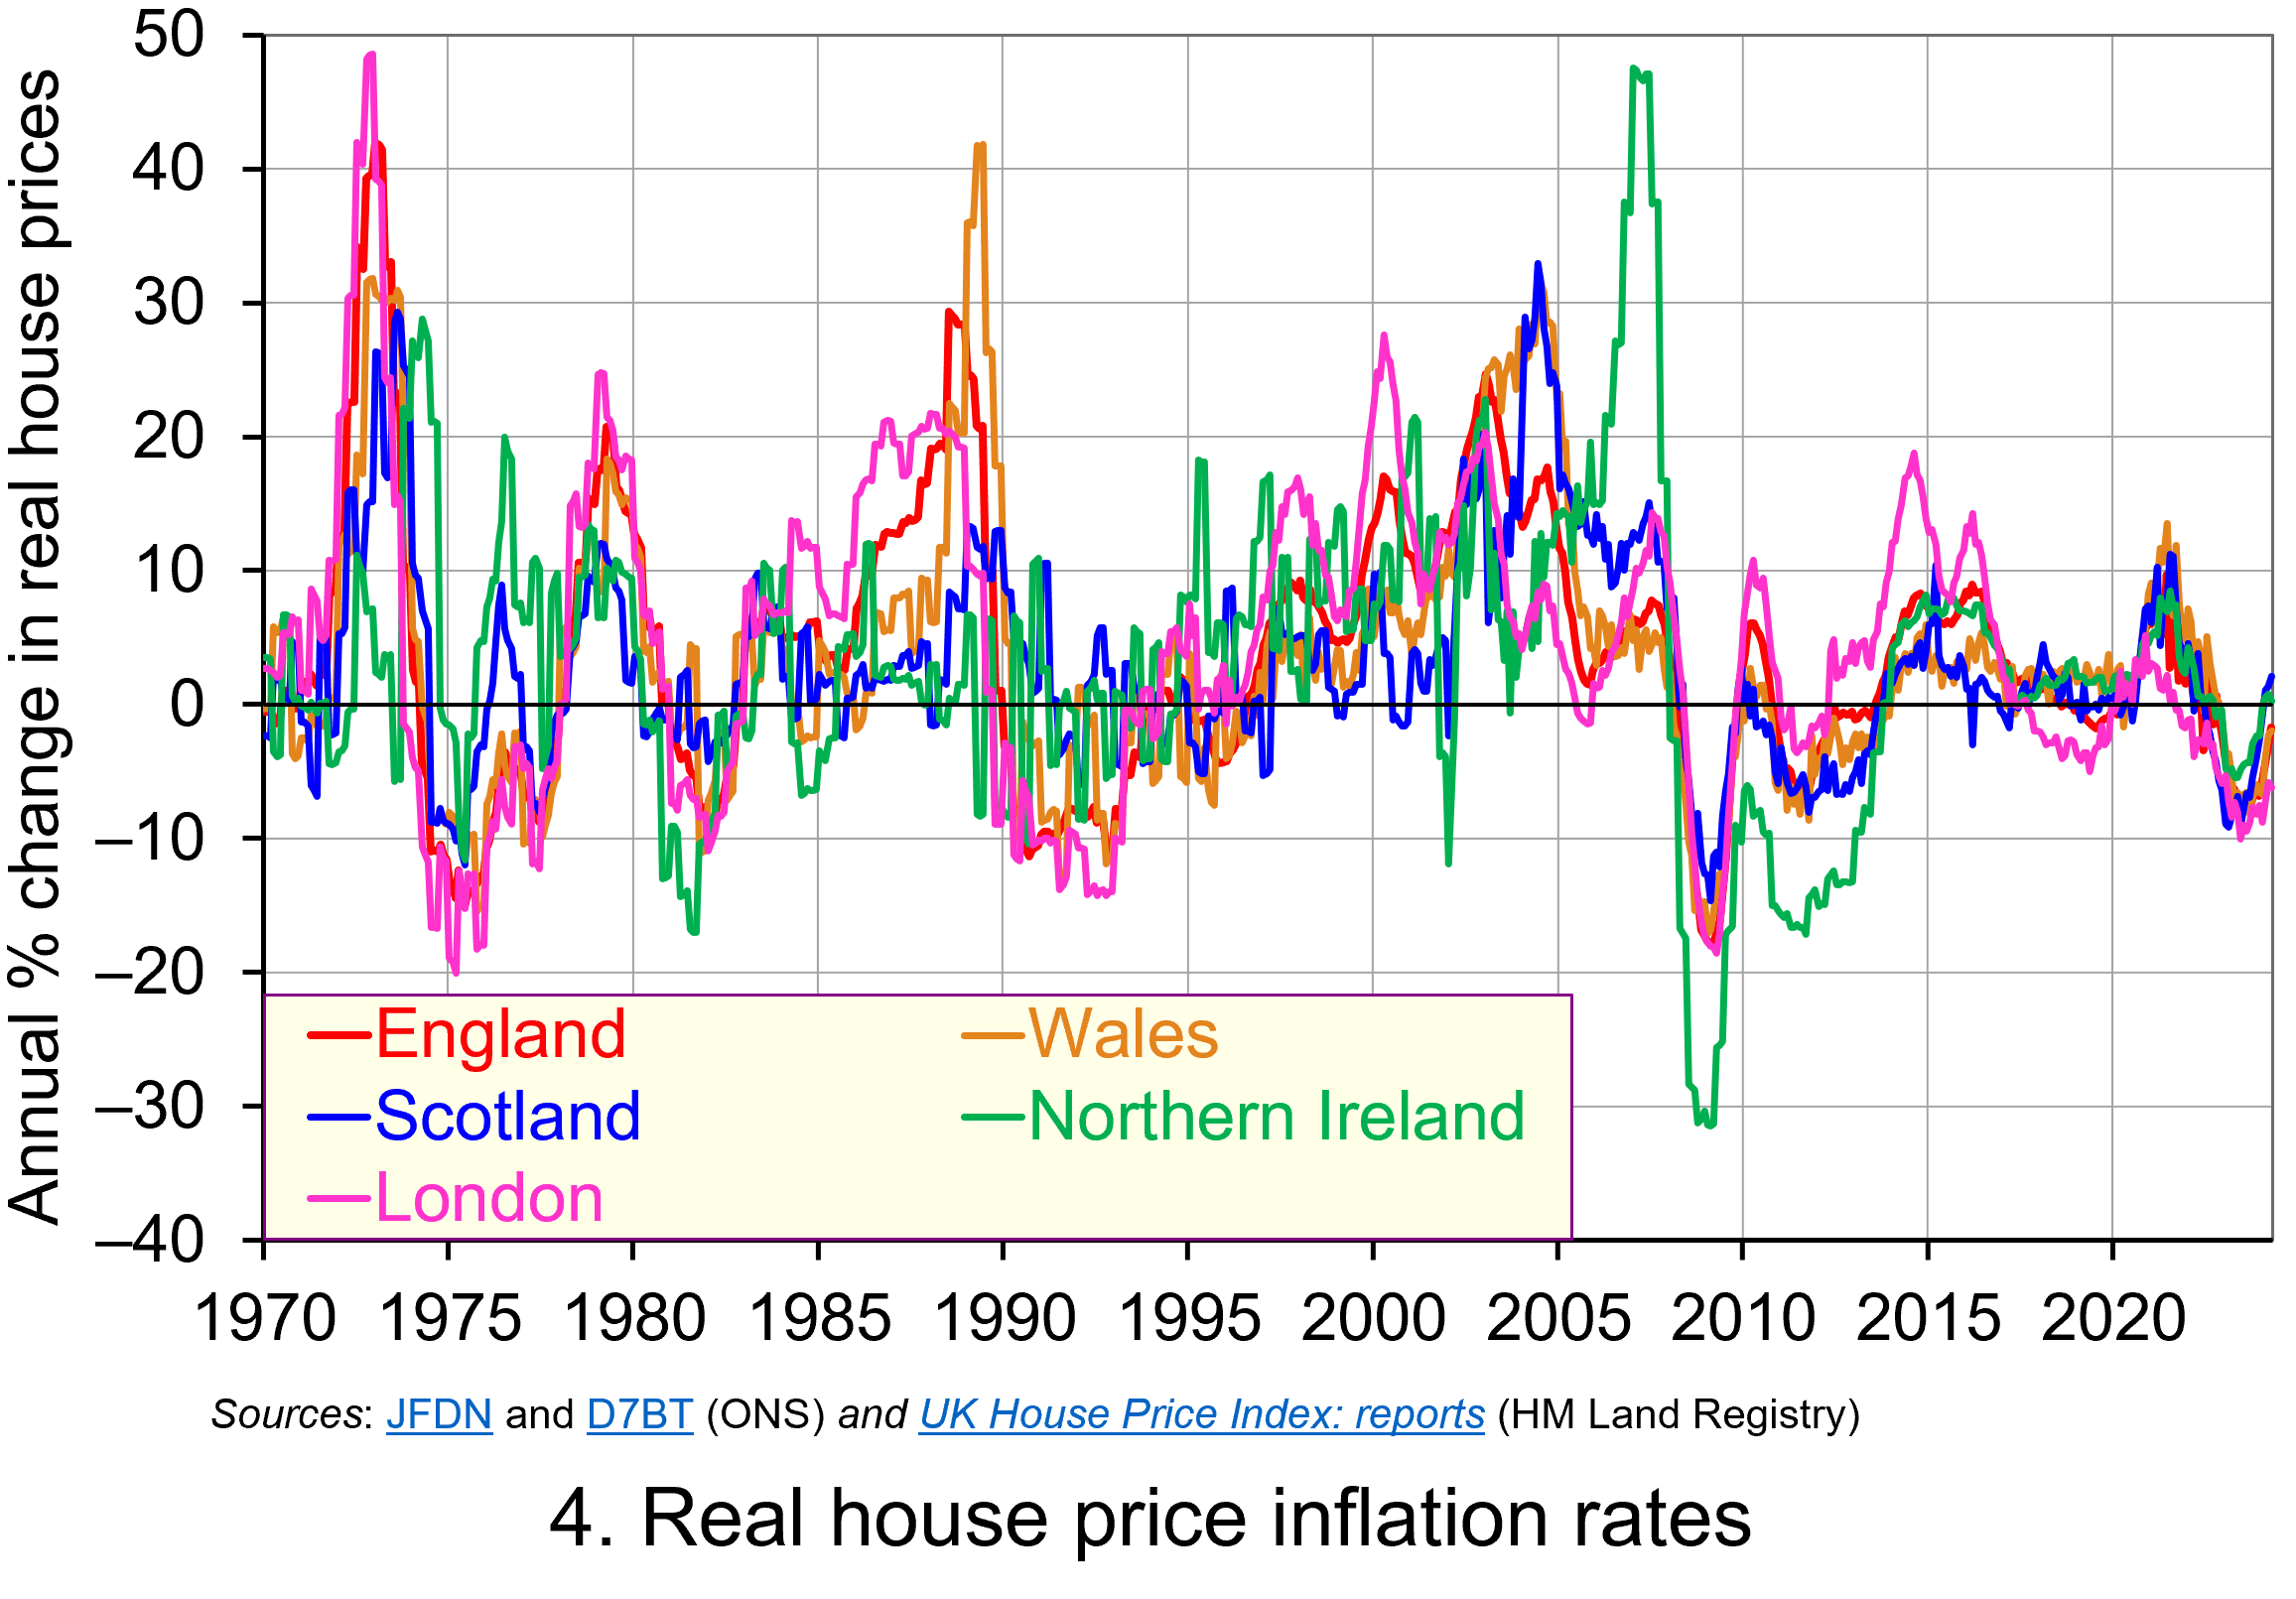 Chart 4 shows how the volatility in house prices continues to be evident when house prices are adjusted for changes in consumer prices. The UK’s annual rate of real house price inflation was as high as 40 per in January 1973; on the other hand, in June 1975 inflation-adjusted house prices were 15 per cent lower than a year earlier. (Click here to download a PowerPoint copy of the chart.)
Over the period from January 1970 to April 2024, the average annual rate of real house price inflation in the UK was 3.2 per cent. Hence house prices have, on average, grown at an annual rate of consumer price inflation plus 3.2 per cent. For the four nations, real house price inflation has averaged 3.8 per cent in England, 3.4 per cent in Wales, 3.0 per cent in Scotland and 2.9 per cent in Northern Ireland. Further, the average rate of real house price inflation in London since January 1970 has been 4.5 per cent. By contrast, that for the East and West Midlands has been 3.7 and 3.5 per cent respectively. The important point here is that the pace with which inflation-adjusted house prices have risen helps to contextualise the extent of the problem of housing affordability – a problem that only worsens over time when real incomes do not keep pace.
House building
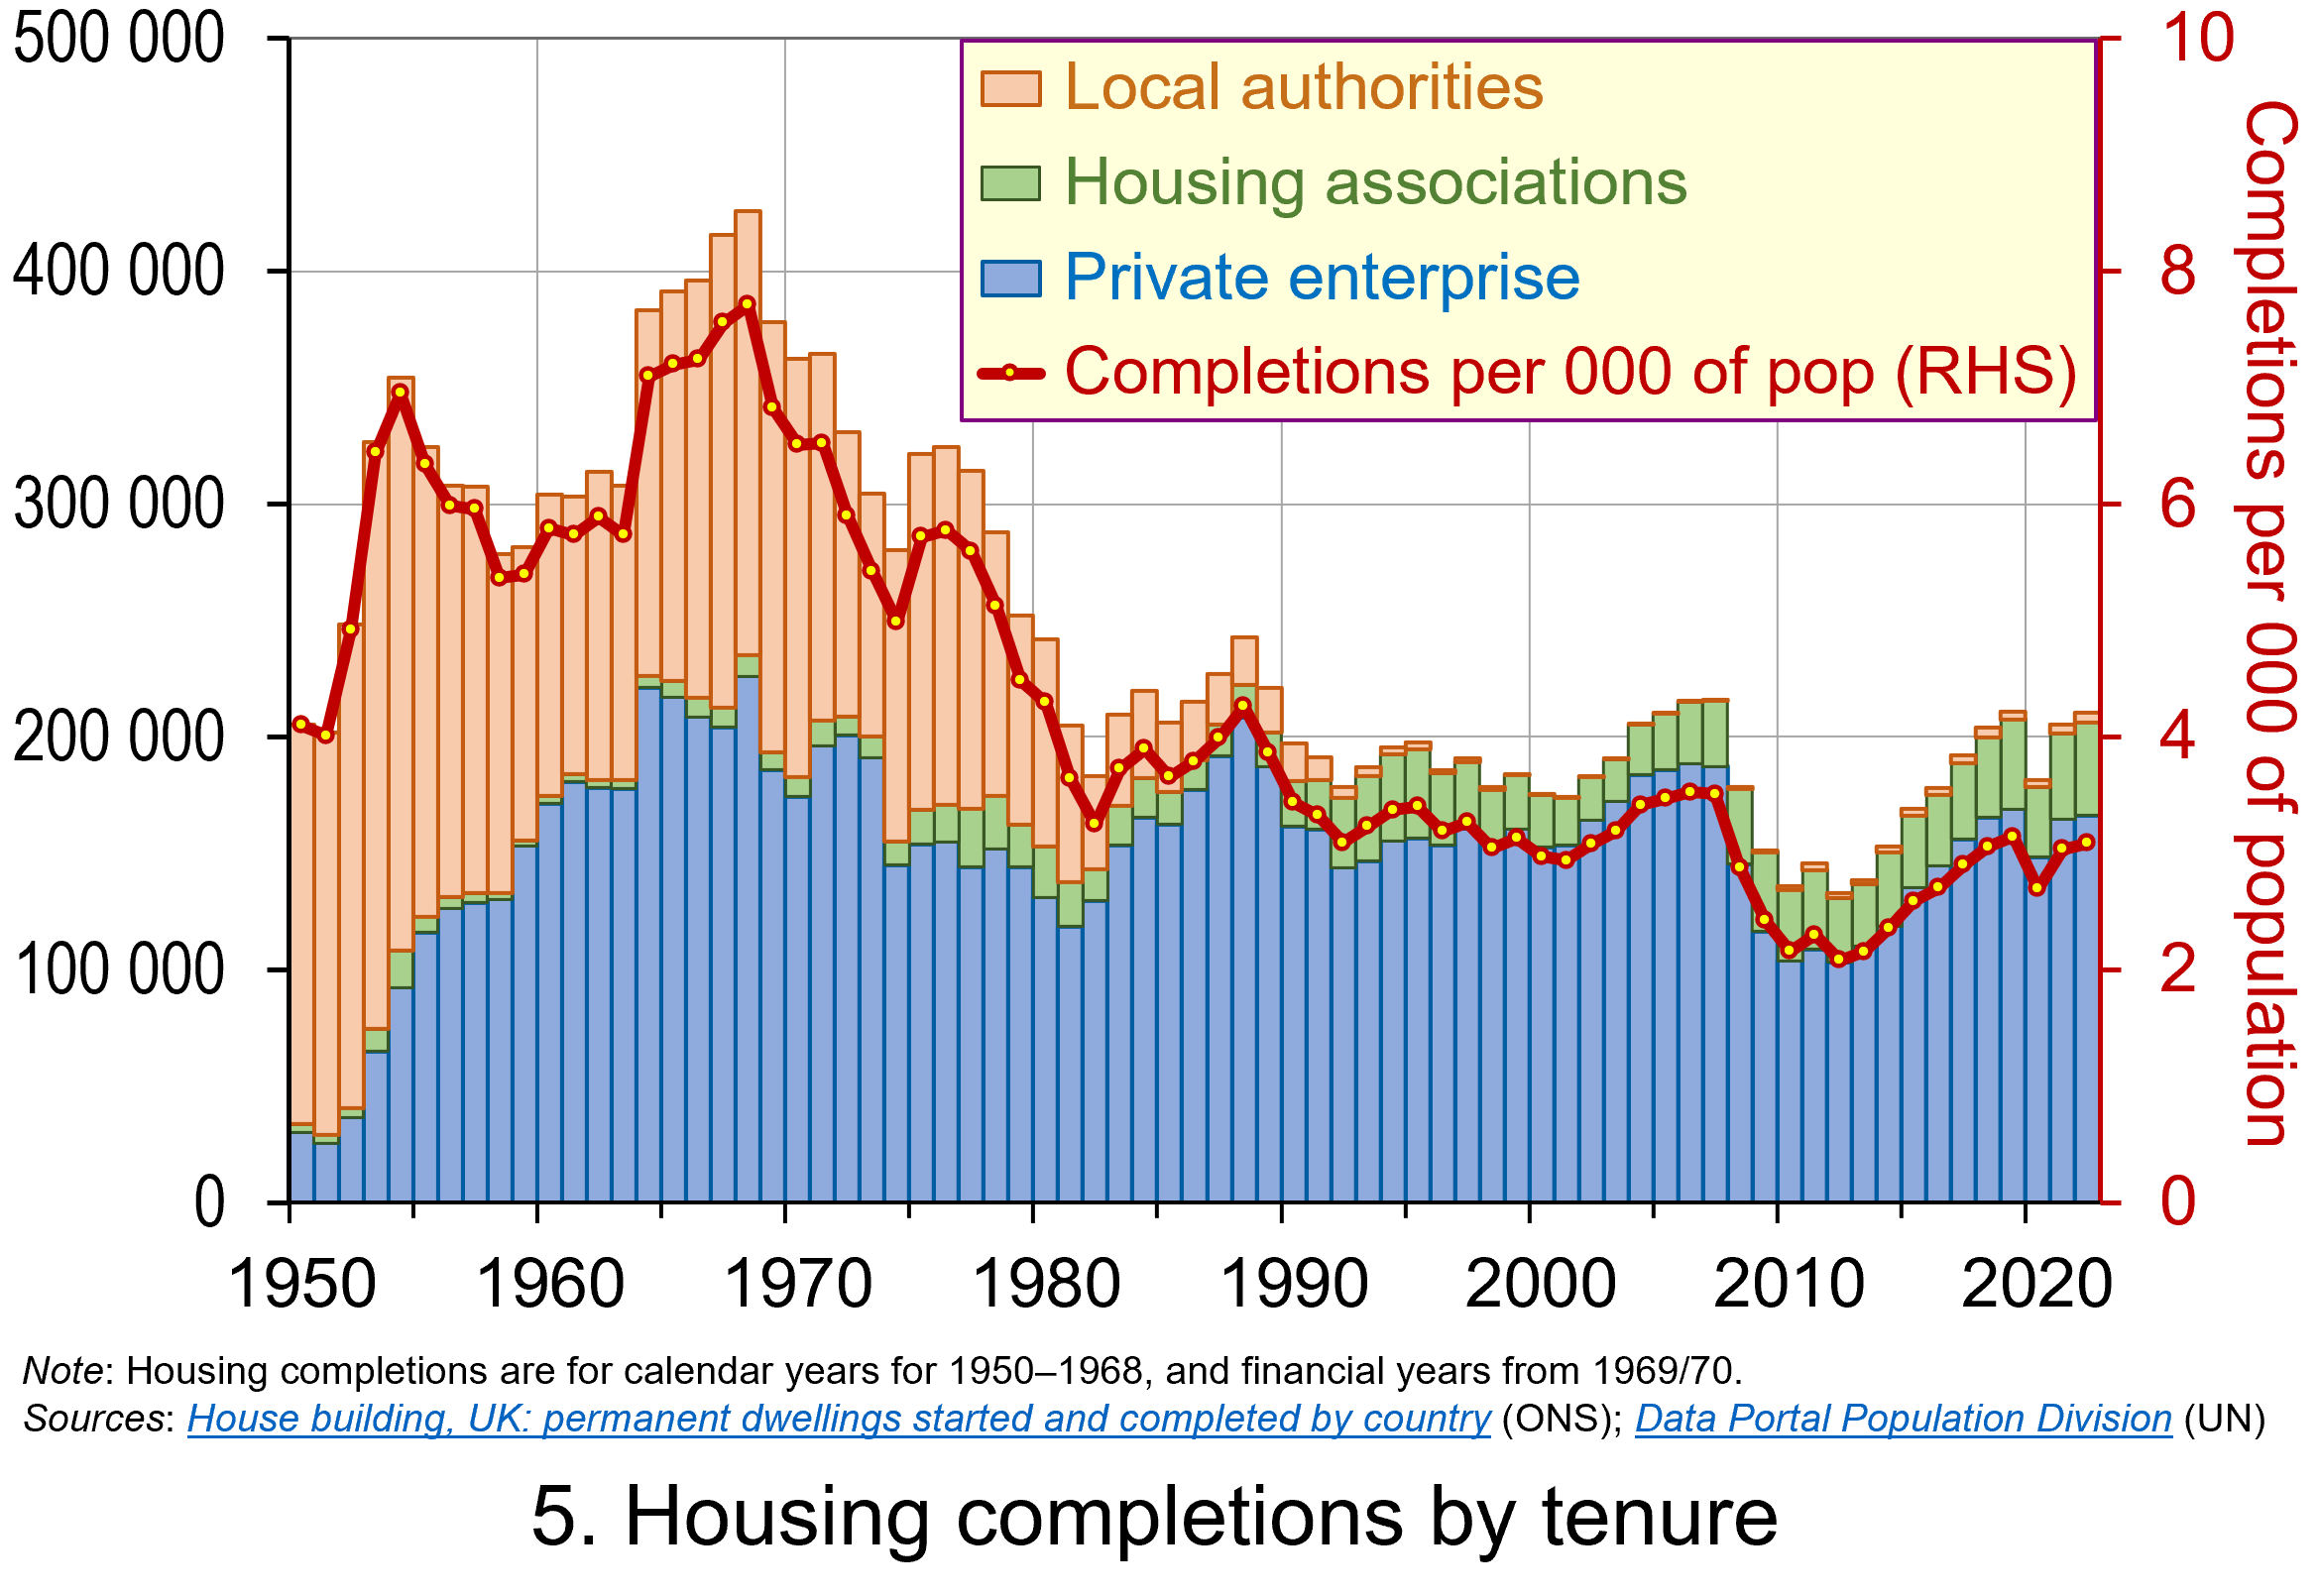 The newly elected Labour government has made the argument that it needs to prioritise planning reform as an engine for economic growth. While this ambition extends beyond housing, the scale of the supply-side problem facing the housing market can be seen in Chart 5. The chart shows the number of housing completions in the UK since 1950 by type of tenure. (Click here to download a PowerPoint copy of the chart.)
The chart shows the extent of the growth in house building in the UK that occurred from the 1950s and into the 1970s. Over these three decades the typical number of new properties completed each year was around 320 000 or 6 per thousand of the population. The peak of house building was in the late 1960s when completions exceeded 400 000 per year or over 7.5 per thousand of the population. It is also noticeable how new local authority housing (‘council houses’) played a much larger role in the overall housing mix.
Since 1980, the average number of housing completions each year has dropped to 191 000 or 3.2 per thousand of the population. If we consider the period since 2000, the number of completions has averaged only 181 000 per year or 2.9 per thousand of the population. While it is important to understand the pressures on housing demand in any assessment of the growth in real house prices, the lack of growth in supply is also a key factor. The fact that less than half the number of properties per thousand people are now being built compared with half a century or so ago is an incredibly stark statistic. It is a major determinant of the deterioration of housing affordability.
However, there are important considerations around the protection of the natural environment that need to be considered too. It will therefore be interesting to see how the reforms to planning develop and what their impact will be on house prices and their affordability.
Articles
- Rachel Reeves requests urgent assessment of spending inheritance
The Guardian, Larry Elliott (8/7/24)
- Reeves to bring back housebuilding targets
BBC News, Faisal Islam and Daniel Thomas (8/7/24)
- UK Chancellor Reeves Vows to Fix Broken Planning System for Housebuilding
Bloomberg UK, Tom Rees, Damian Shepherd, and Joe Mayes (8/7/24)
- What to expect for house prices for the rest of 2024
i News, Callum Mason (10/7/24)
- UK house prices still unaffordable for many people, says Nationwide
The Guardian, Richard Partington (1/7/24)
- House prices still unaffordable for the average earner despite wage rises – Nationwide
Sky News, Sarah Taaffe-Maguire (1/7/24)
- Labour cannot build 1.5m homes without cash for affordable housing, providers say
The Guardian, Jack Simpson (12/7/24)
Statistics
Questions
- Explain the difference between a rise in the rate of house price inflation a rise in the level of house prices.
- Explain the difference between nominal and real house prices.
- If nominal house prices rise can real house price fall? Explain your answer.
- What do you understand by the terms instructions to buy and instructions to sell?
- What factors are likely to affect the levels of instructions to buy and instructions to sell?
- How does the balance between instructions to buy and instructions to sell affect house prices?
- How can we differentiate between different housing markets? Illustrate your answer with examples.
- What metrics could be used to measure the affordability of housing?
- Discuss the argument that the deterioration of housing affordability is the result of market failure.
 In the third of our series on the distinction between nominal and real values we show its importance when analysing retail sales data. In the UK, such data are available from the Office for National Statistics. This blog revisits an earlier one, Nominal and real retail sales figures: interpreting the data, written in October 2023. We find that inflation-adjusted retail sales data reveal some stark patterns in the sector. They help contextualise some of the challenges faced by high streets up and down the UK.
The Retail Sales Index
Retail sales relate to spending on items such as food, clothing, footwear and household goods. They involve sales by retailers directly to final consumers, whether in store or online. Spending on services such as holidays, air fares and train tickets, insurance, banking, hotels and restaurants are not included, as are sales of motor vehicles. The Retail Sales Index for Great Britain is based on a monthly survey of around 5000 retailers across England, Scotland and Wales and is thought to capture around three-quarters of turnover in the retail industry.
Estimates of retail sales are published in index form. There are two indices published by the ONS: a value and volume measure. The value index reflects the total turnover of business, while the volume index adjusts the value index for price changes. Hence, the value estimates are nominal, while the volume estimates are real. The key point here is that the nominal estimates reflect both price and volume changes, whereas the real estimates adjust for price movements to capture only volume changes.
The headline ONS figures for May 2024 showed a rise by 2.9 per cent in the volume of retail sales, following a 1.8 per cent fall in April. In value terms, May saw a 3.3 per cent rise in retail sales following a 2.3 fall in March. Monthly changes can be quite volatile, even after seasonal adjustment, and sensitive to peculiar factors. For example, the poor weather in April 2024 helped to depress retail spending. It is, therefore, sensible to take a longer-term view when looking for clearer patterns in spending behaviour.
Growth of retail sales
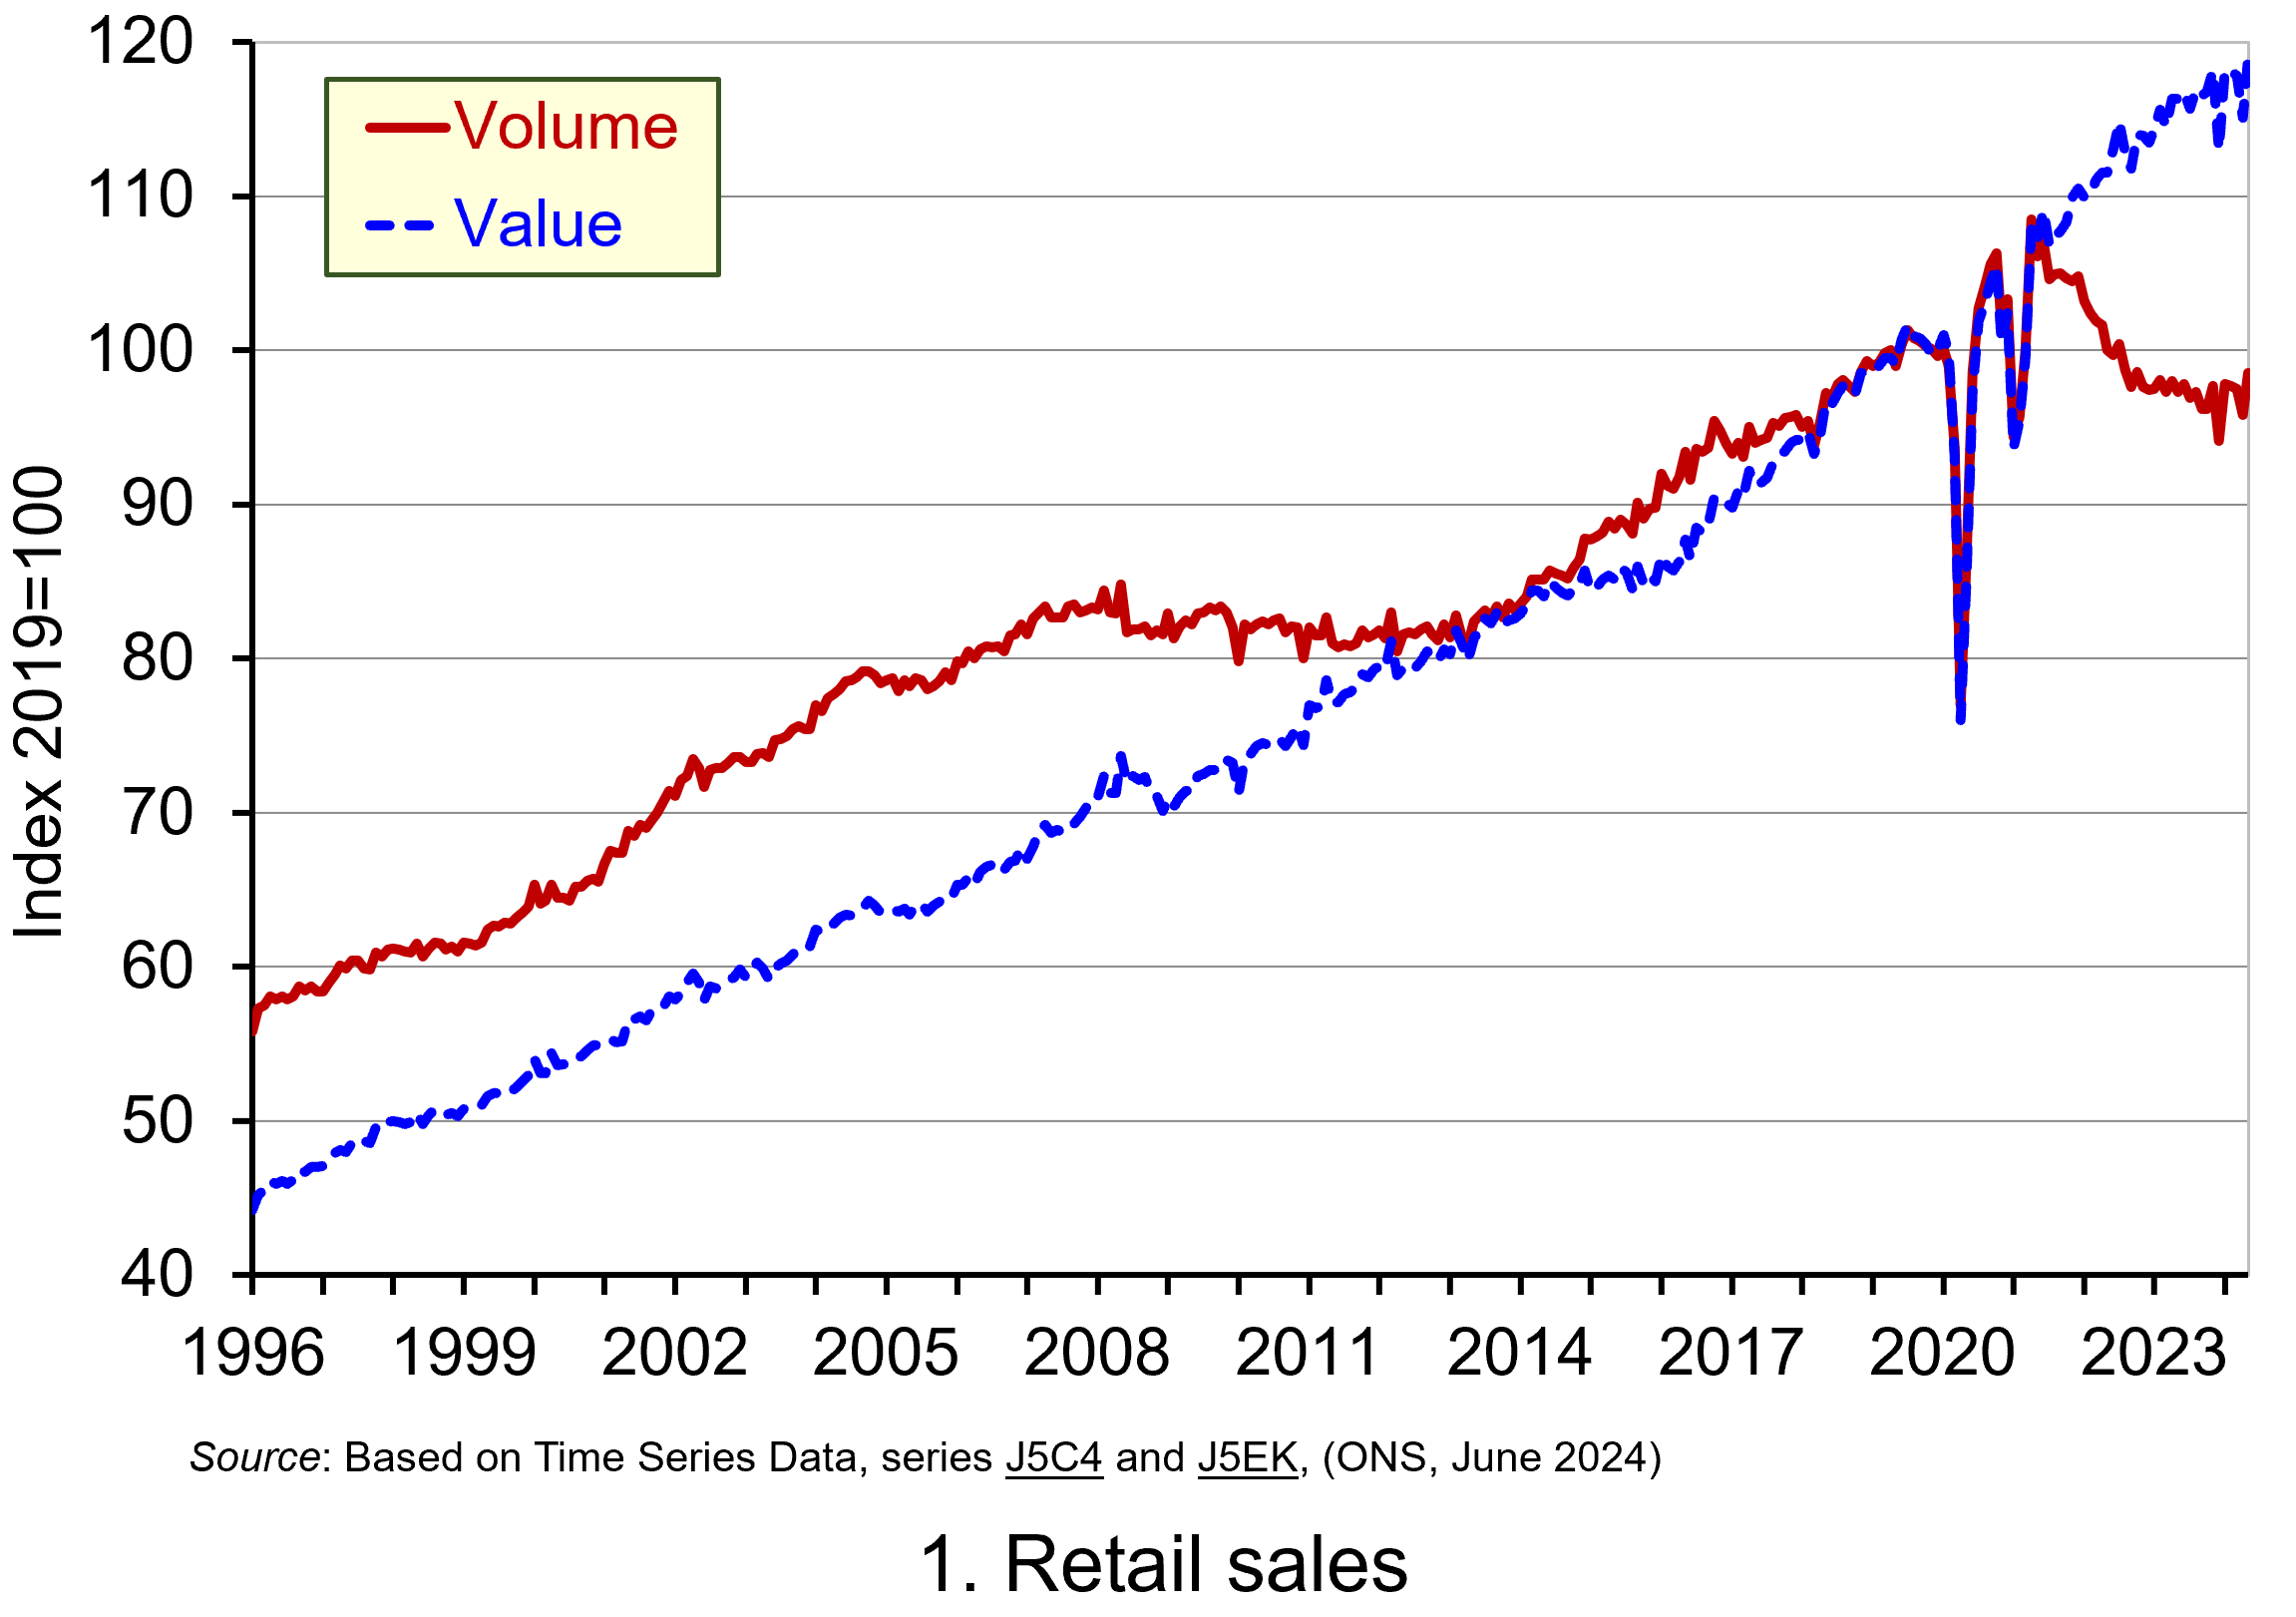 Chart 1 plots the monthly value and volume of retail sales in Great Britain since 1996. (Click here to download a PowerPoint of the chart). In value terms, monthly spending in the retail sector has increased by 169 per cent since January 1996, whereas in volume terms, spending has increased by 77 per cent. Another way of thinking about this is in terms of the average annual rate of increase. This shows that the value of spending has risen at an annual rate of 3.5 per cent while the volume of spending has risen at an annual rate of 2.0 per cent. This difference is to be expected in the presence of rising prices, since nominal growth, as we have just noted, reflects both price and volume changes.
Chart 1 helps to identify two periods where the volume of retail spending ceased to grow. The first of these is following the global financial crisis of the late 2000s. The period from 2008 to 2013 saw the volume of retail sales stagnate and flatline, with a recovery in volumes only really starting to take hold in 2014. Yet in nominal terms retail sales grew by around 14 per cent.
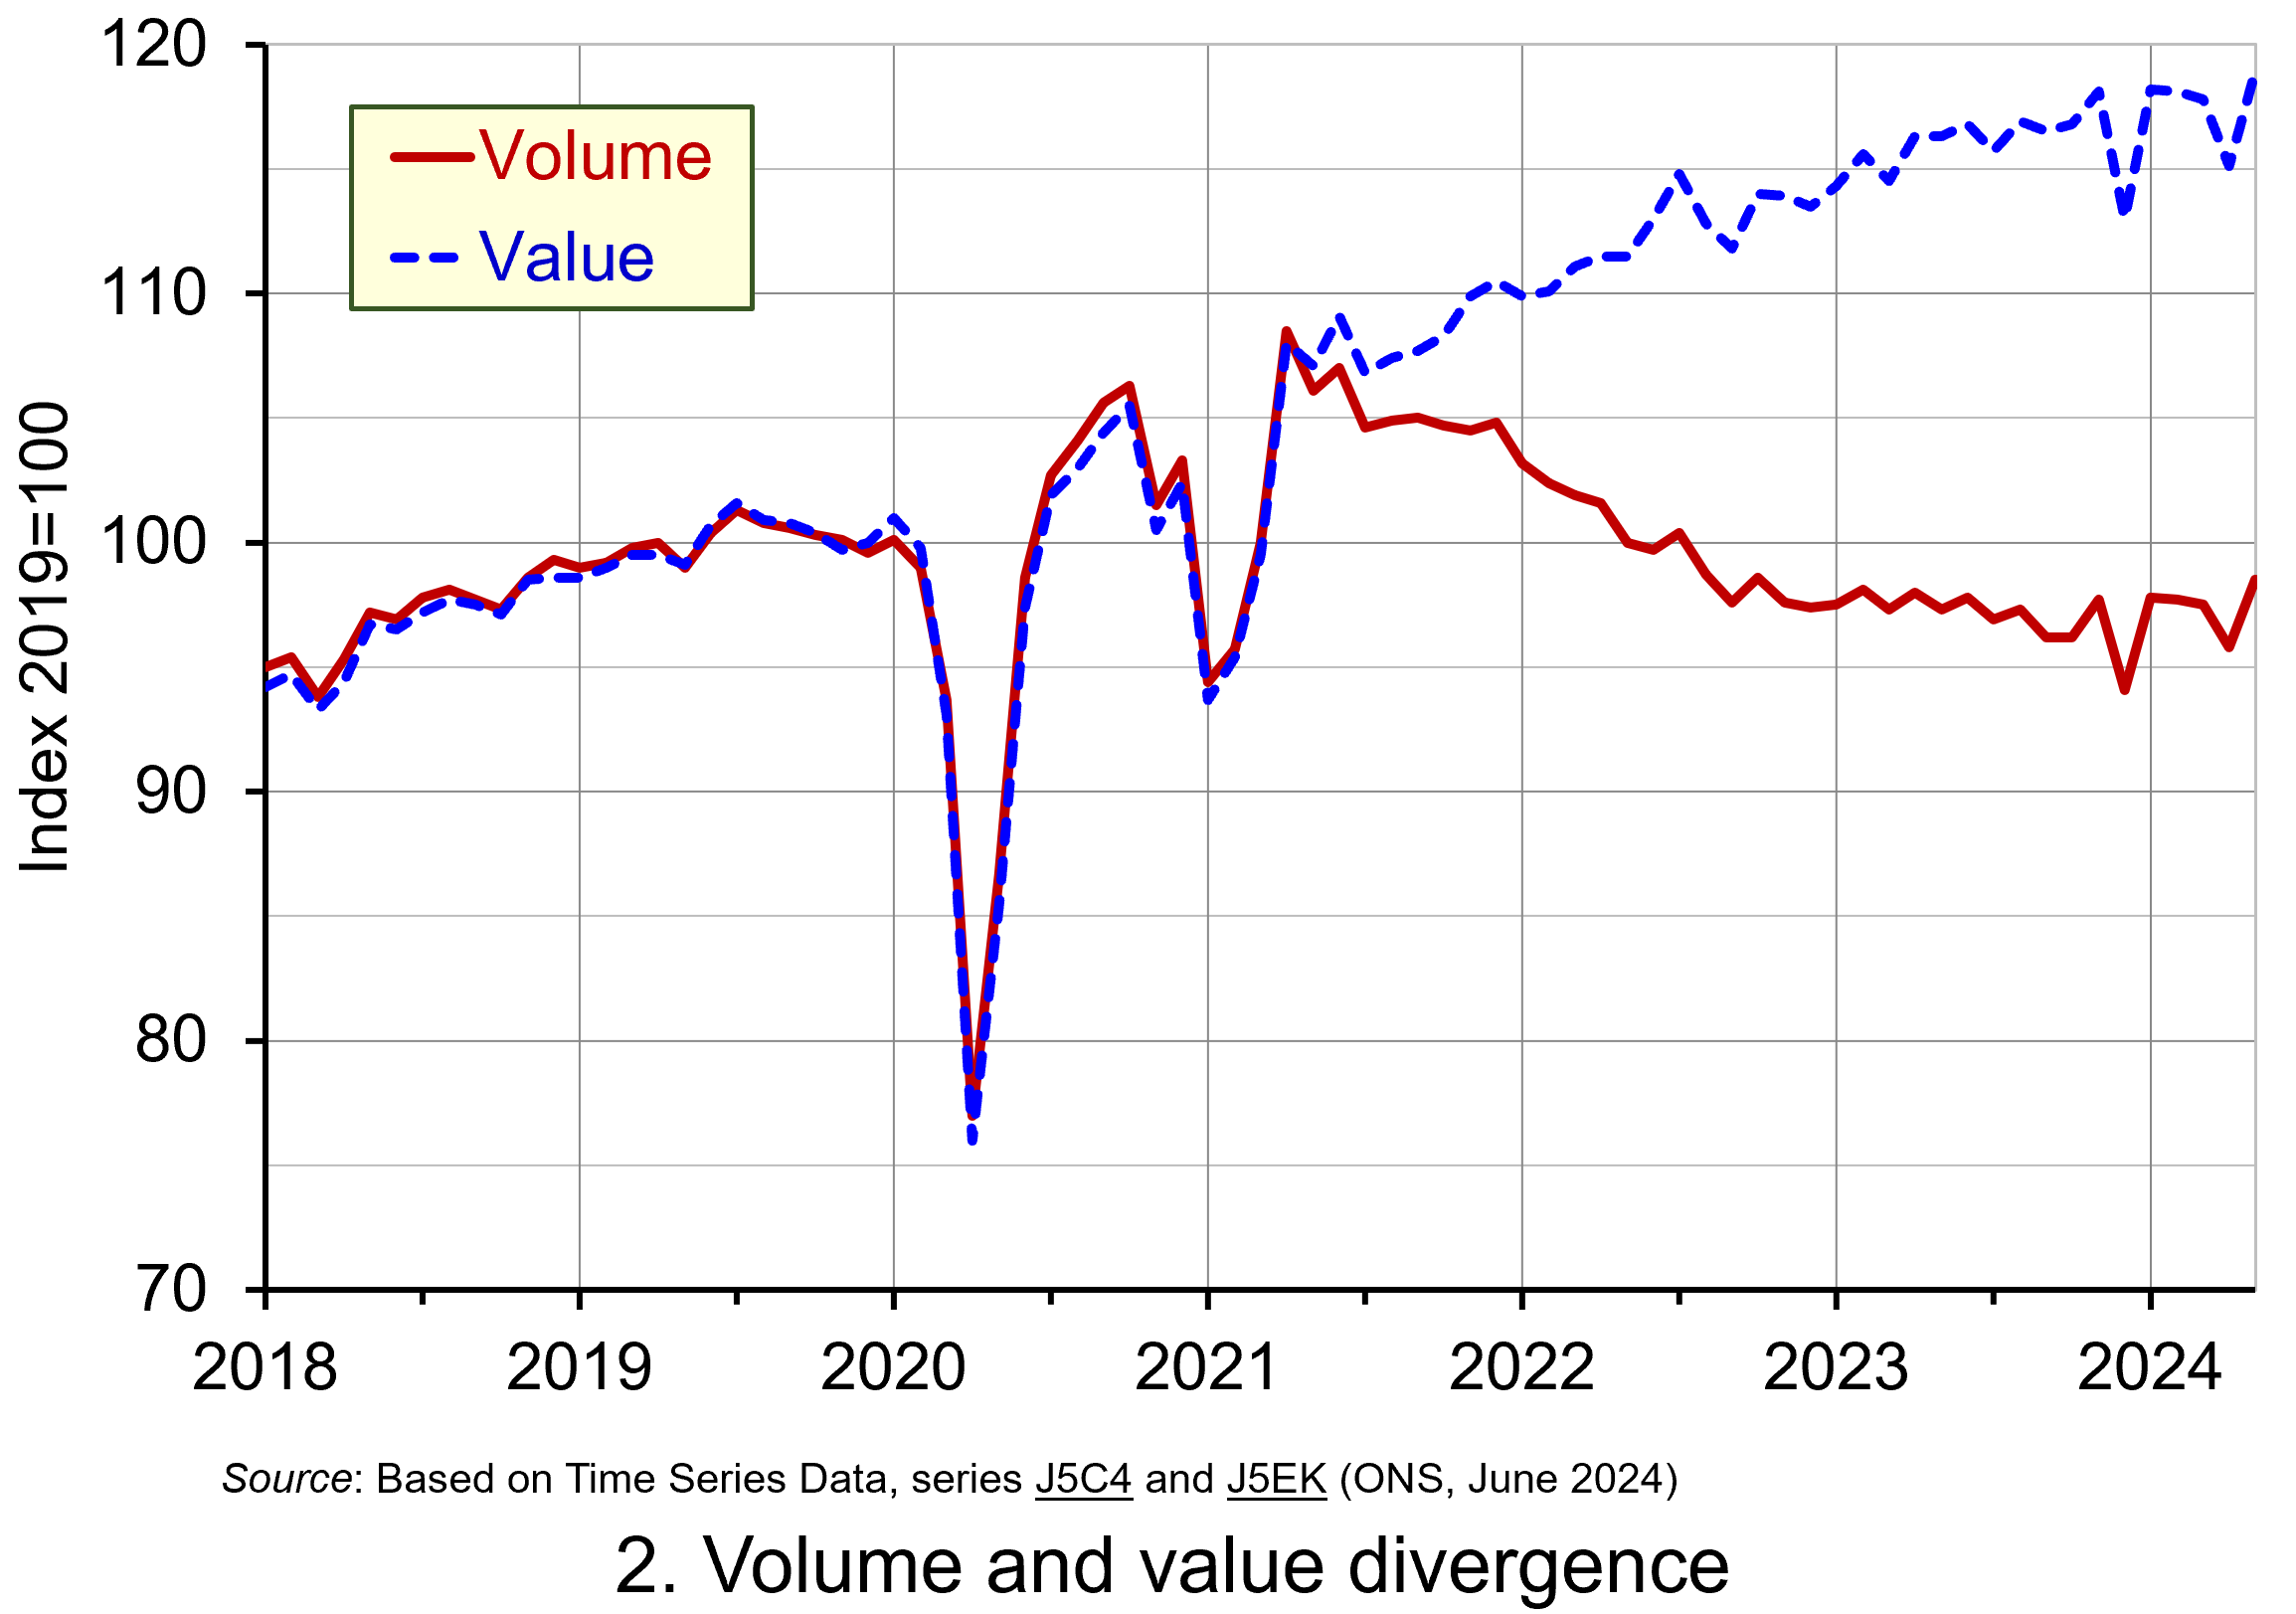 The second of the two periods is from 2021. Chart 2 helps to demonstrates the extent of the struggles of the retail sector in this period. It shows a significant divergence between the volume and value of retail sales. Indeed, between April 2021 and October 2023, while the value of retail sales increased by 8.0 per cent the volume of retail sales fell by 11.0 per cent.
The recent value-volume divergence reflects the inflation shock that began to emerge in 2021. This saw consumer prices, as measured by the Consumer Prices Index (CPI), rise across 2022 and 2023 by 9.1 per cent and 7.3 per cent respectively, with the annual rate of CPI inflation hitting 11.1 per cent in October 2022. Hence, while inflation was a drag on the volume of spending it nonetheless meant that the value of spending continued to rise. Once more this demonstrates why understanding the distinction between nominal and real is important. (Click here to download a PowerPoint of the chart).
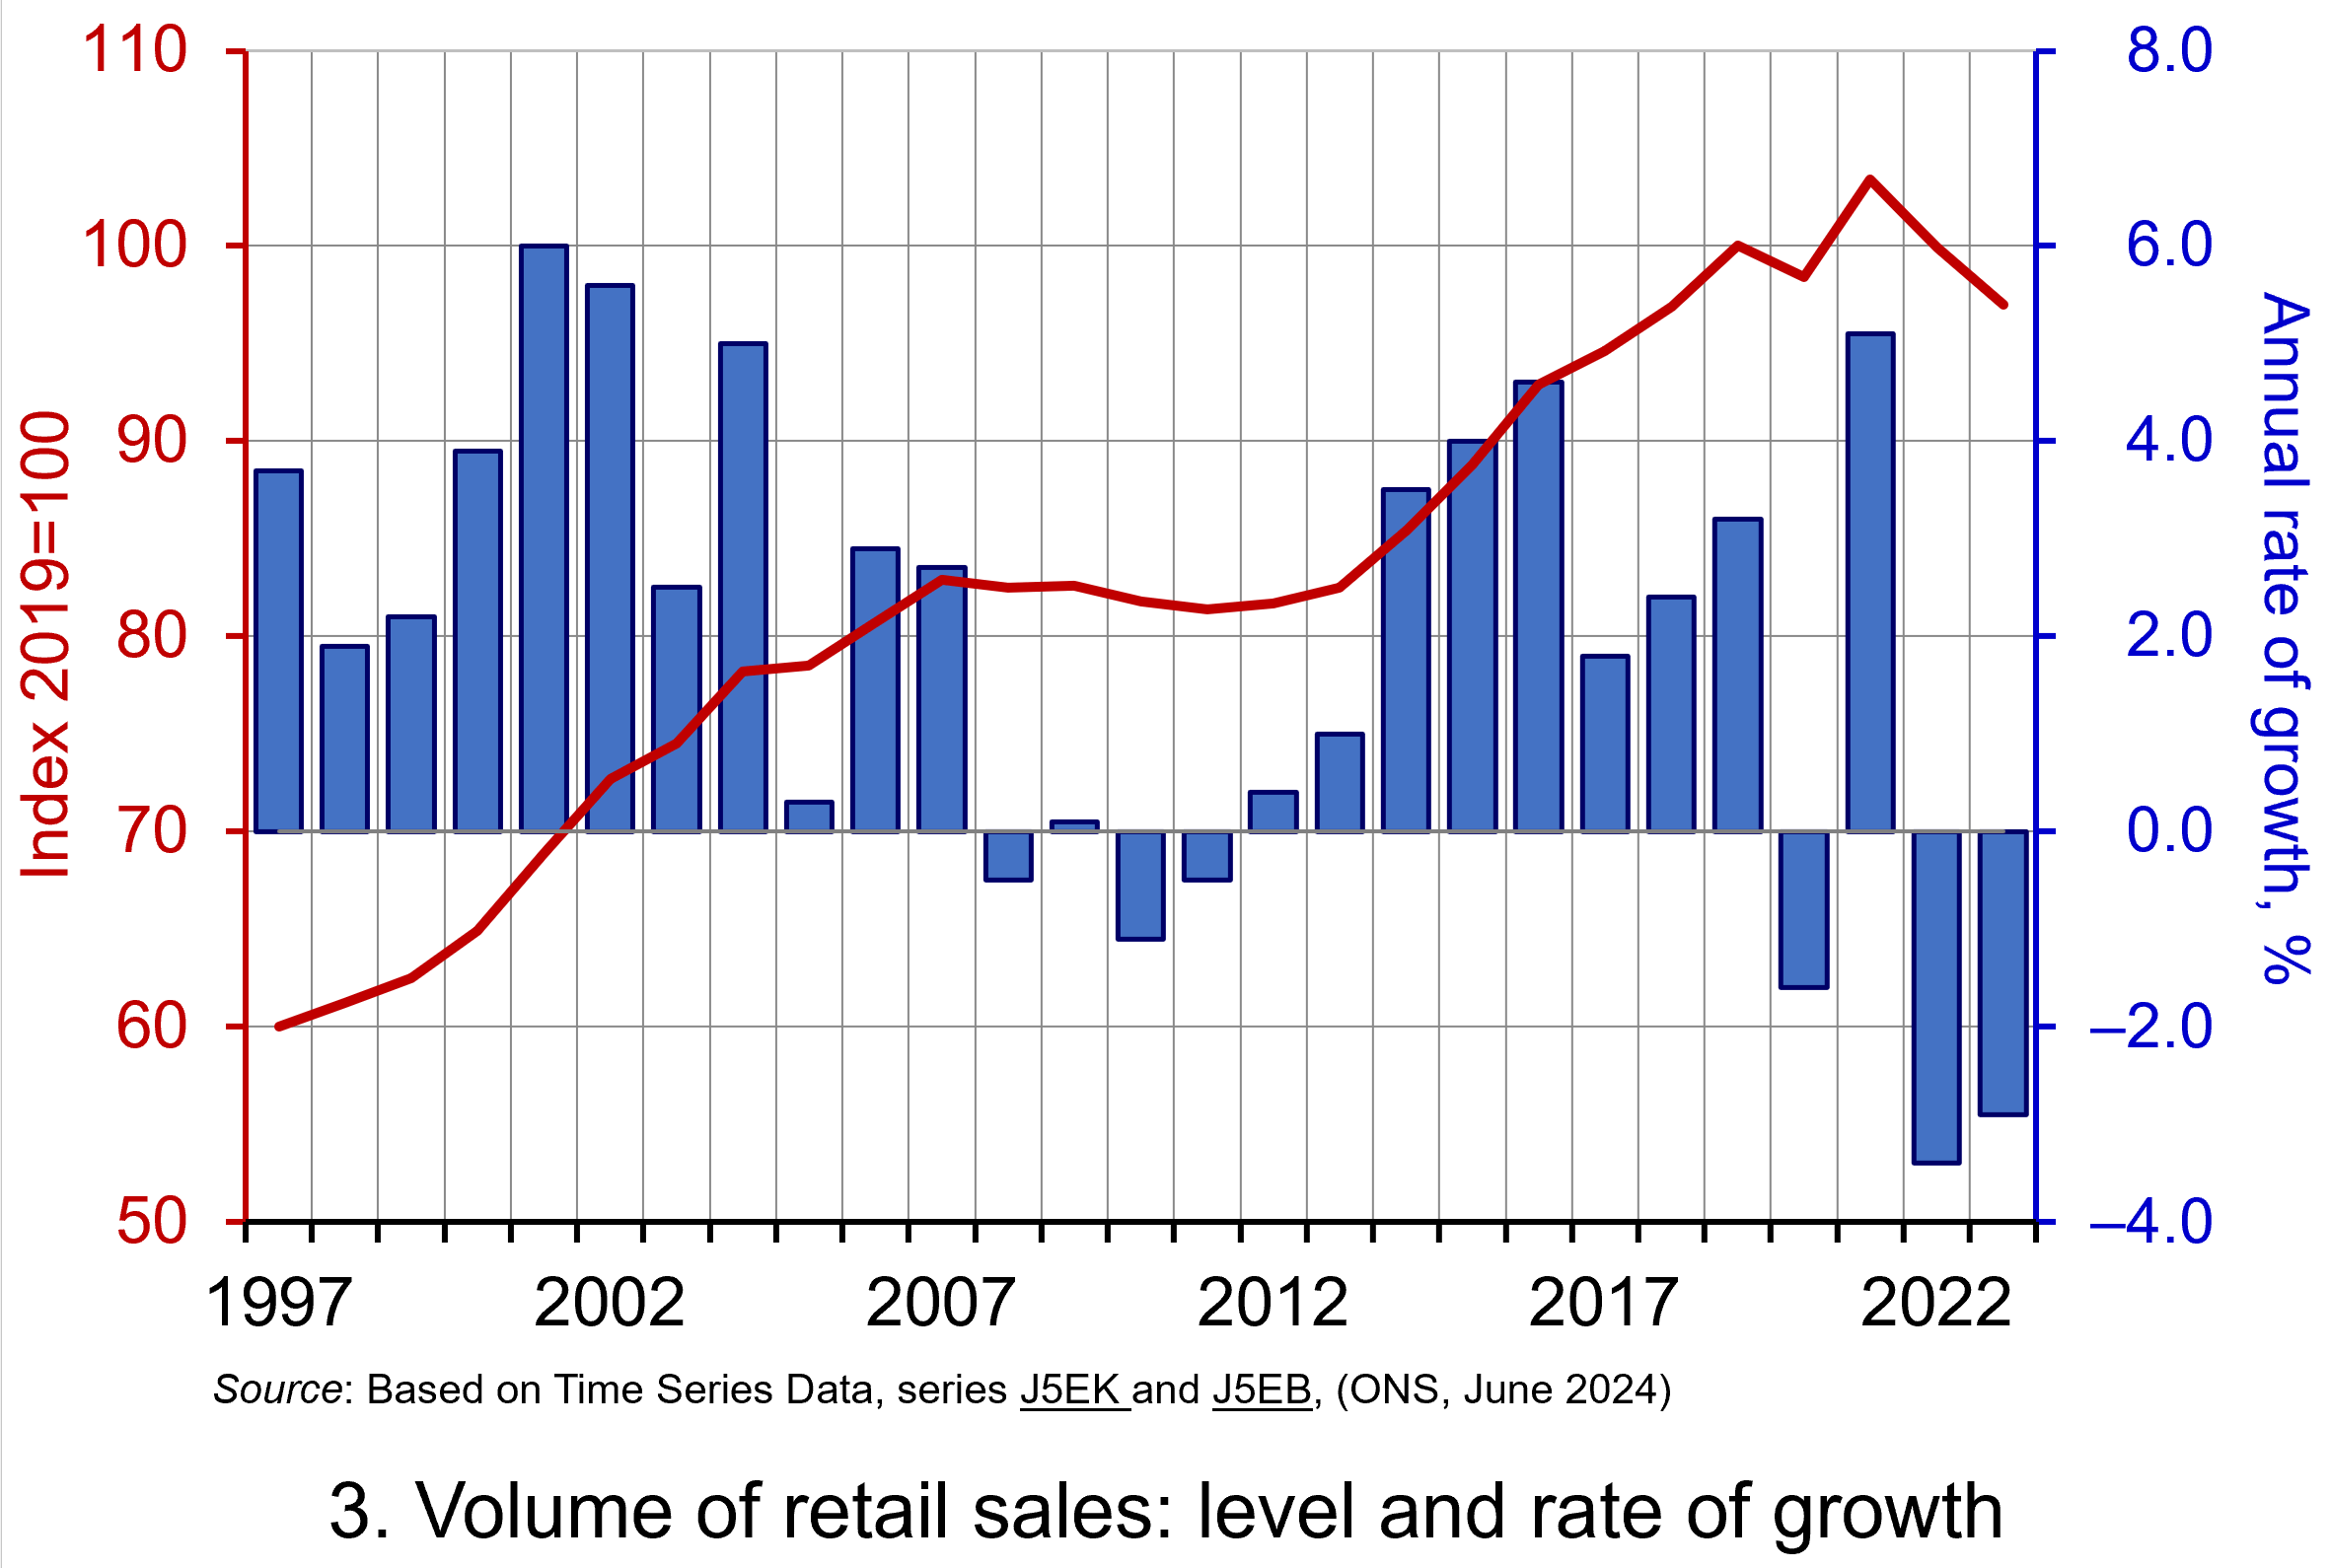 To illustrate the longer-term trend in the volume of retail spending alongside its volatility, Chart 3 plots yearly retail sales volumes and also their percentage change on the previous year.
The chart nicely captures the prolonged halt to retail sales growth following the global financial crisis, the fluctuations caused by COVID and then the sharp falls in the volume of retail spending in 2022 and 2023 as the effects of the inflationary shock on peoples’ finances bit sharply. This cost-of-living crisis significantly affected many people’s disposable income. (Click here to download a PowerPoint of the chart).
Categories of retail sales
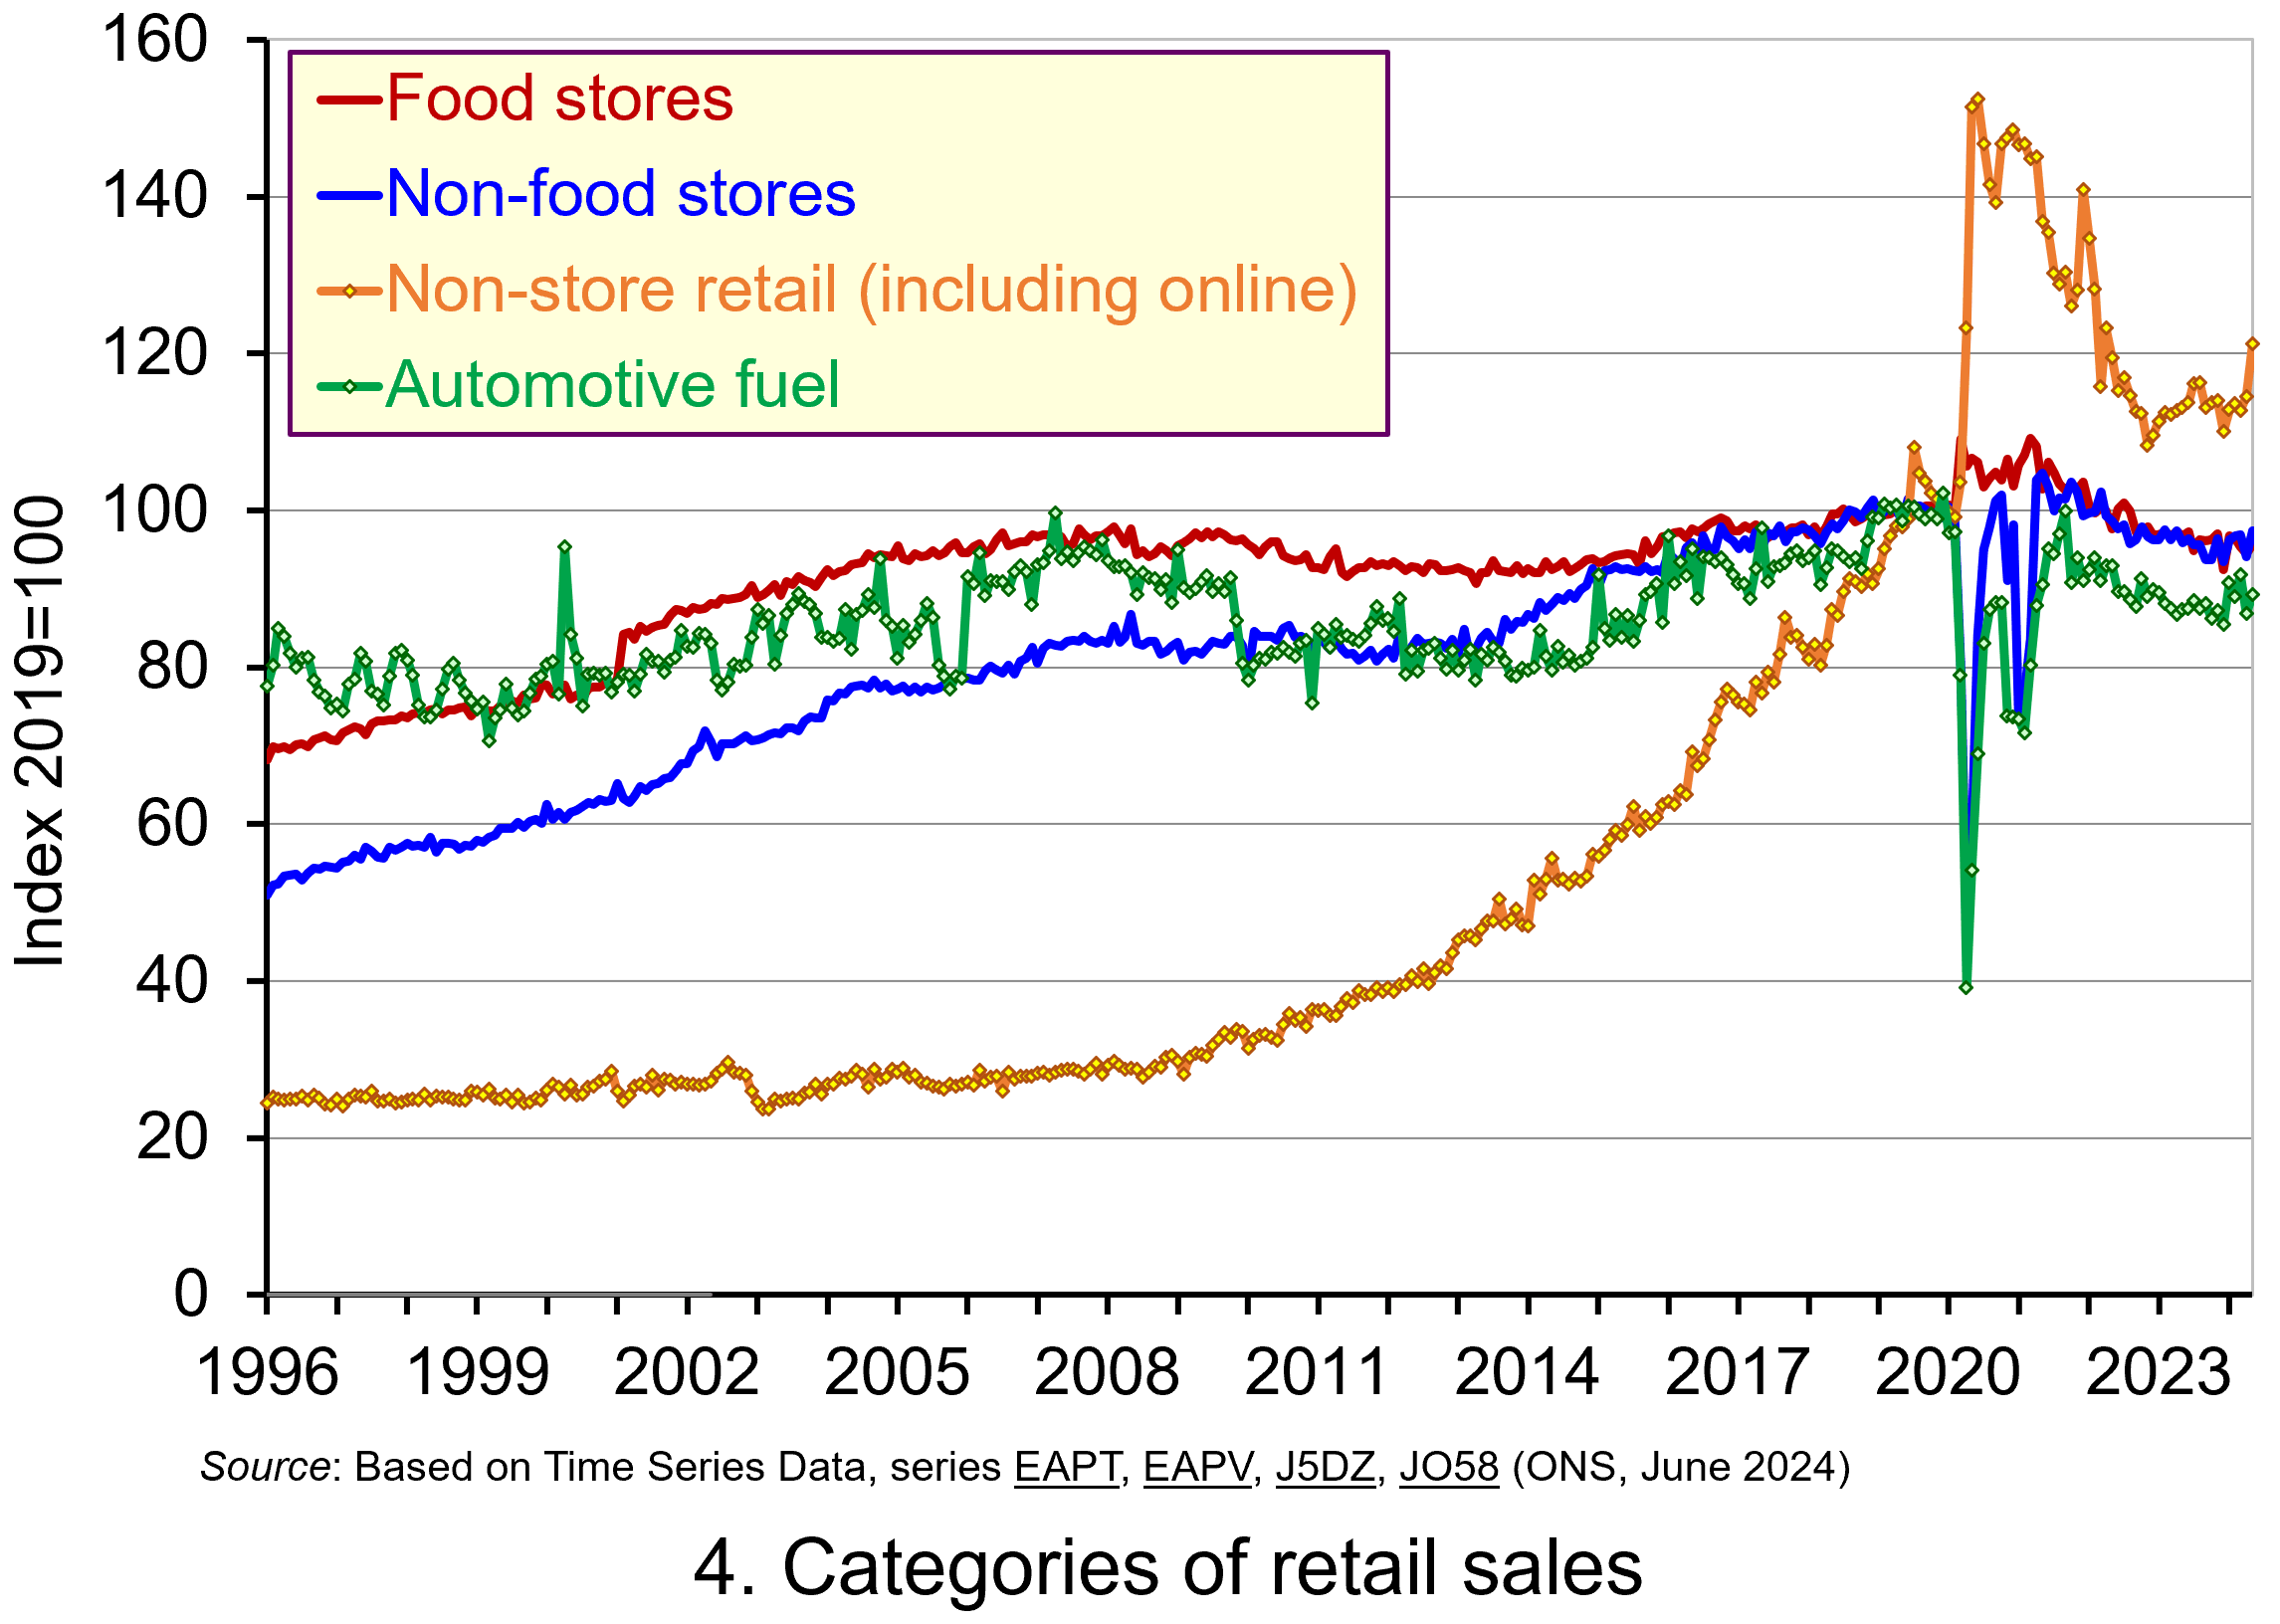 We conclude by considering categories of retail spending. Chart 4 shows volumes of retail sales by four broad categories since 1996. (Click here to download a PowerPoint of the chart). These are food stores, predominantly non-food stores, non-store retail and automotive fuel (i.e. sales of petrol and diesel “at the pumps”).
Whilst all categories have seen an increase in their spending volumes over the period as a whole, there are stark differences in this rate of growth. Perhaps not surprisingly, the most rapid growth is in non-store retail. This includes online retailing, as well as market stalls and catalogues.
The volume of retail spending in the non-store sector has grown at an average annual rate over this period of 6.3 per cent, compared with 2.6 per cent for non-food stores, 1.2 per cent for predominantly food stores and 1.0 per cent for automotive fuels. The growth of non-store retail has been even more rapid since 2010, when the average annual rate of growth in the volume of purchases has been 10.2 per cent, compared to 1.8 per cent for non-food stores, 1.0 per cent for automotive fuels and zero growth for food stores.
If we focus on the most recent patterns in the categories of retail sales, we see that the monthly volume of spending in all categories except non-store retail is now lower than the average in 2019. Specifically, when compared to 2019 levels, the volume of spending in non-food stores in May 2024 was 2.6 per cent lower, while that in food stores was 4.4 per cent lower, and the volume of spending on automotive fuels was 10.8 per cent lower. In contrast, spending in non-store retail was 21.2 per cent higher. Yet this is not to imply that this sector has been immune to the pressures faced by their high-street counterparts. Although it is difficult to disentangle fully the effects of the pandemic and lockdowns on non-store retail sales data, the downward trajectory in the volume of retail sales in the sector that occurred as the economy ‘reopened’ in 2021 and 2022 continued into 2023 when purchases fell by 3.5 per cent.
Final thoughts
The retail sector is an incredibly important part of the economy. A recent research briefing from the House of Commons Library reports that there were 2.7 million jobs in the UK retail sector in 2022, equivalent to 8.6 per cent of the country’s jobs with 314 040 retail businesses as of January 2023. Yet the importance of the retail sector cannot be captured by these statistics alone. Some would argue that the very fabric and wellbeing of our towns and cities is affected by the wellbeing of the sector and, importantly, by structural changes that affect how people interact with retail.
Articles
Research Briefing
Statistical bulletin
Data
Questions
- Which of the following is/are not counted in the UK retail sales data: (i) purchase of furniture from a department store; (ii) weekly grocery shop online; (iii) a stay at a hotel on holiday; (iv) a meal at your favourite café or restaurant?
- Why does an increase in the value of retail sales not necessarily mean that their volume has increased?
- In the presence of deflation, which will be higher: nominal or real growth rates?
- Discuss the factors that could explain the patterns in the volume of spending observed in the different categories of retail sales in Chart 4.
- Discuss what types of retail products might be more or less sensitive to changes in the macroeconomic environment.
- Conduct a survey of recent media reports to prepare a briefing discussing examples of retailers who have struggled or thrived in the recent economic environment.
- What do you understand by the concepts of ‘consumer confidence’ and ‘economic uncertainty’? How might these affect the volume of retail spending?
- Discuss the proposition that the retail sales data cast doubt on whether people are ‘forward-looking consumption smoothers’.
 In the first of a series of updated blogs focusing on the importance of the distinction between nominal and real values we look at the issue of earnings. Here we update the blog Getting Real with Pay written back in February 2019. Then, we noted how the macroeconomic environment since the financial crisis of the late 2000s had continued to affect people’s pay. Specifically, we observed that there had been no growth in real or inflation-adjusted pay. In other words, people were no better off in 2019 than in 2008.
In this updated blog, we consider to what extent the picture has changed five years down the line. While we do not consider the distributional impact on pay, the aggregate picture nonetheless continues to paint a very stark picture, with consequences for living standards and financial wellbeing.
While the distinction between nominal and real values is perhaps best known in relation to GDP and economic growth, the distinction is also applied frequently to analyse the movement of one price relative to prices in general. One example is that of movements in pay (earnings) relative to consumer prices.
Pay reflects the price of labour. The value of our actual pay is our nominal pay. If our pay rises more quickly than consumer prices, then our real pay increases. This means that our purchasing power rises and so the volume of goods and services we can afford increases. On the other hand, if our actual pay rises less quickly than consumer prices then our real pay falls. When real pay falls, purchasing power falls and the volume of goods and services we can afford falls.
Figures from the Office for National Statistics show that in January 2000 regular weekly pay (excluding bonuses and before taxes and other deductions from pay) was £293. By April 2024 this had risen to £640. This is an increase of 118 per cent. Over the same period, the consumer prices index known as the CPIH, which, unlike the better-known CPI, includes owner-occupied housing costs and council tax, rose by 82 per cent. Therefore, the figures are consistent with a rise both in nominal and real pay between January 2000 to April 2024. However, this masks a rather different picture that has emerged since the global financial crisis of the late 2000s.
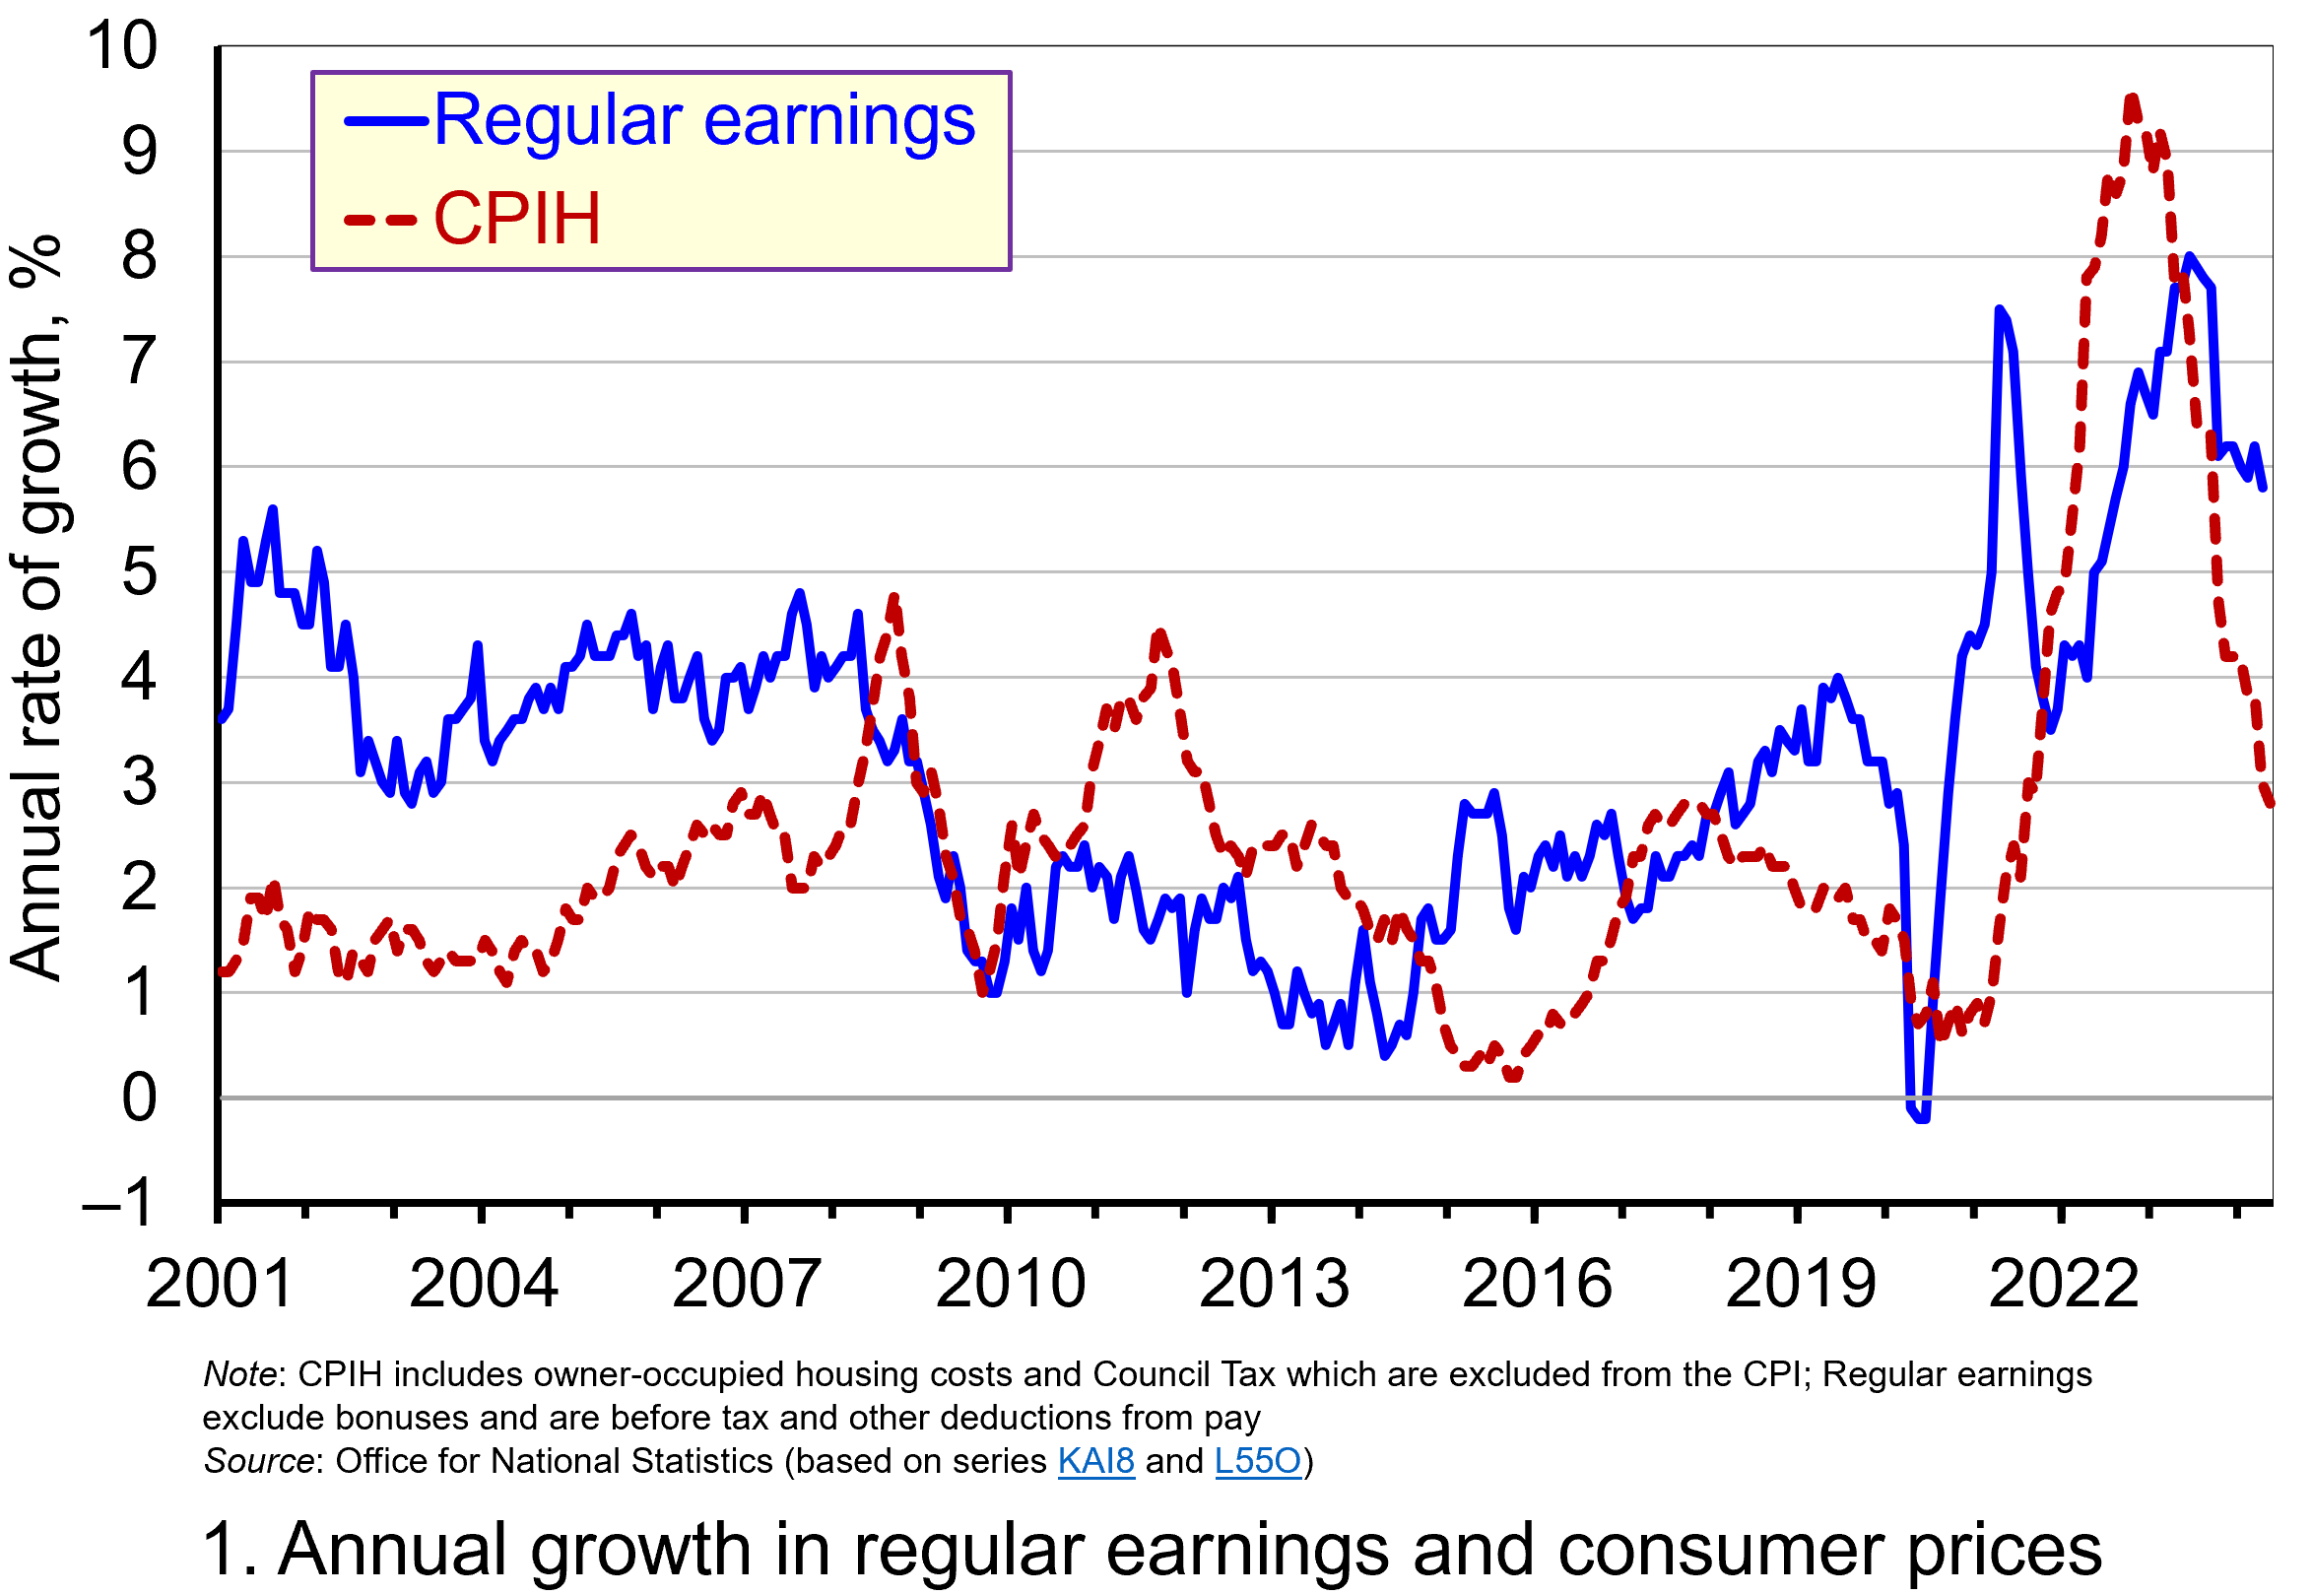 Chart 1 shows the annual percentage changes in actual (nominal) regular weekly pay and the CPIH since January 2001. Each value is simply the percentage change from 12 months earlier. The period up to June 2008 saw the annual growth of weekly pay outstrip the growth of consumer prices – the blue line in the chart is above the red dashed line. Therefore, the real value of pay rose. However, from June 2008 to August 2014 pay growth consistently fell short of the rate of consumer price inflation – the blue line is below the red dashed line. The result was that average real weekly pay fell. (Click here to download a PowerPoint copy of the chart.)
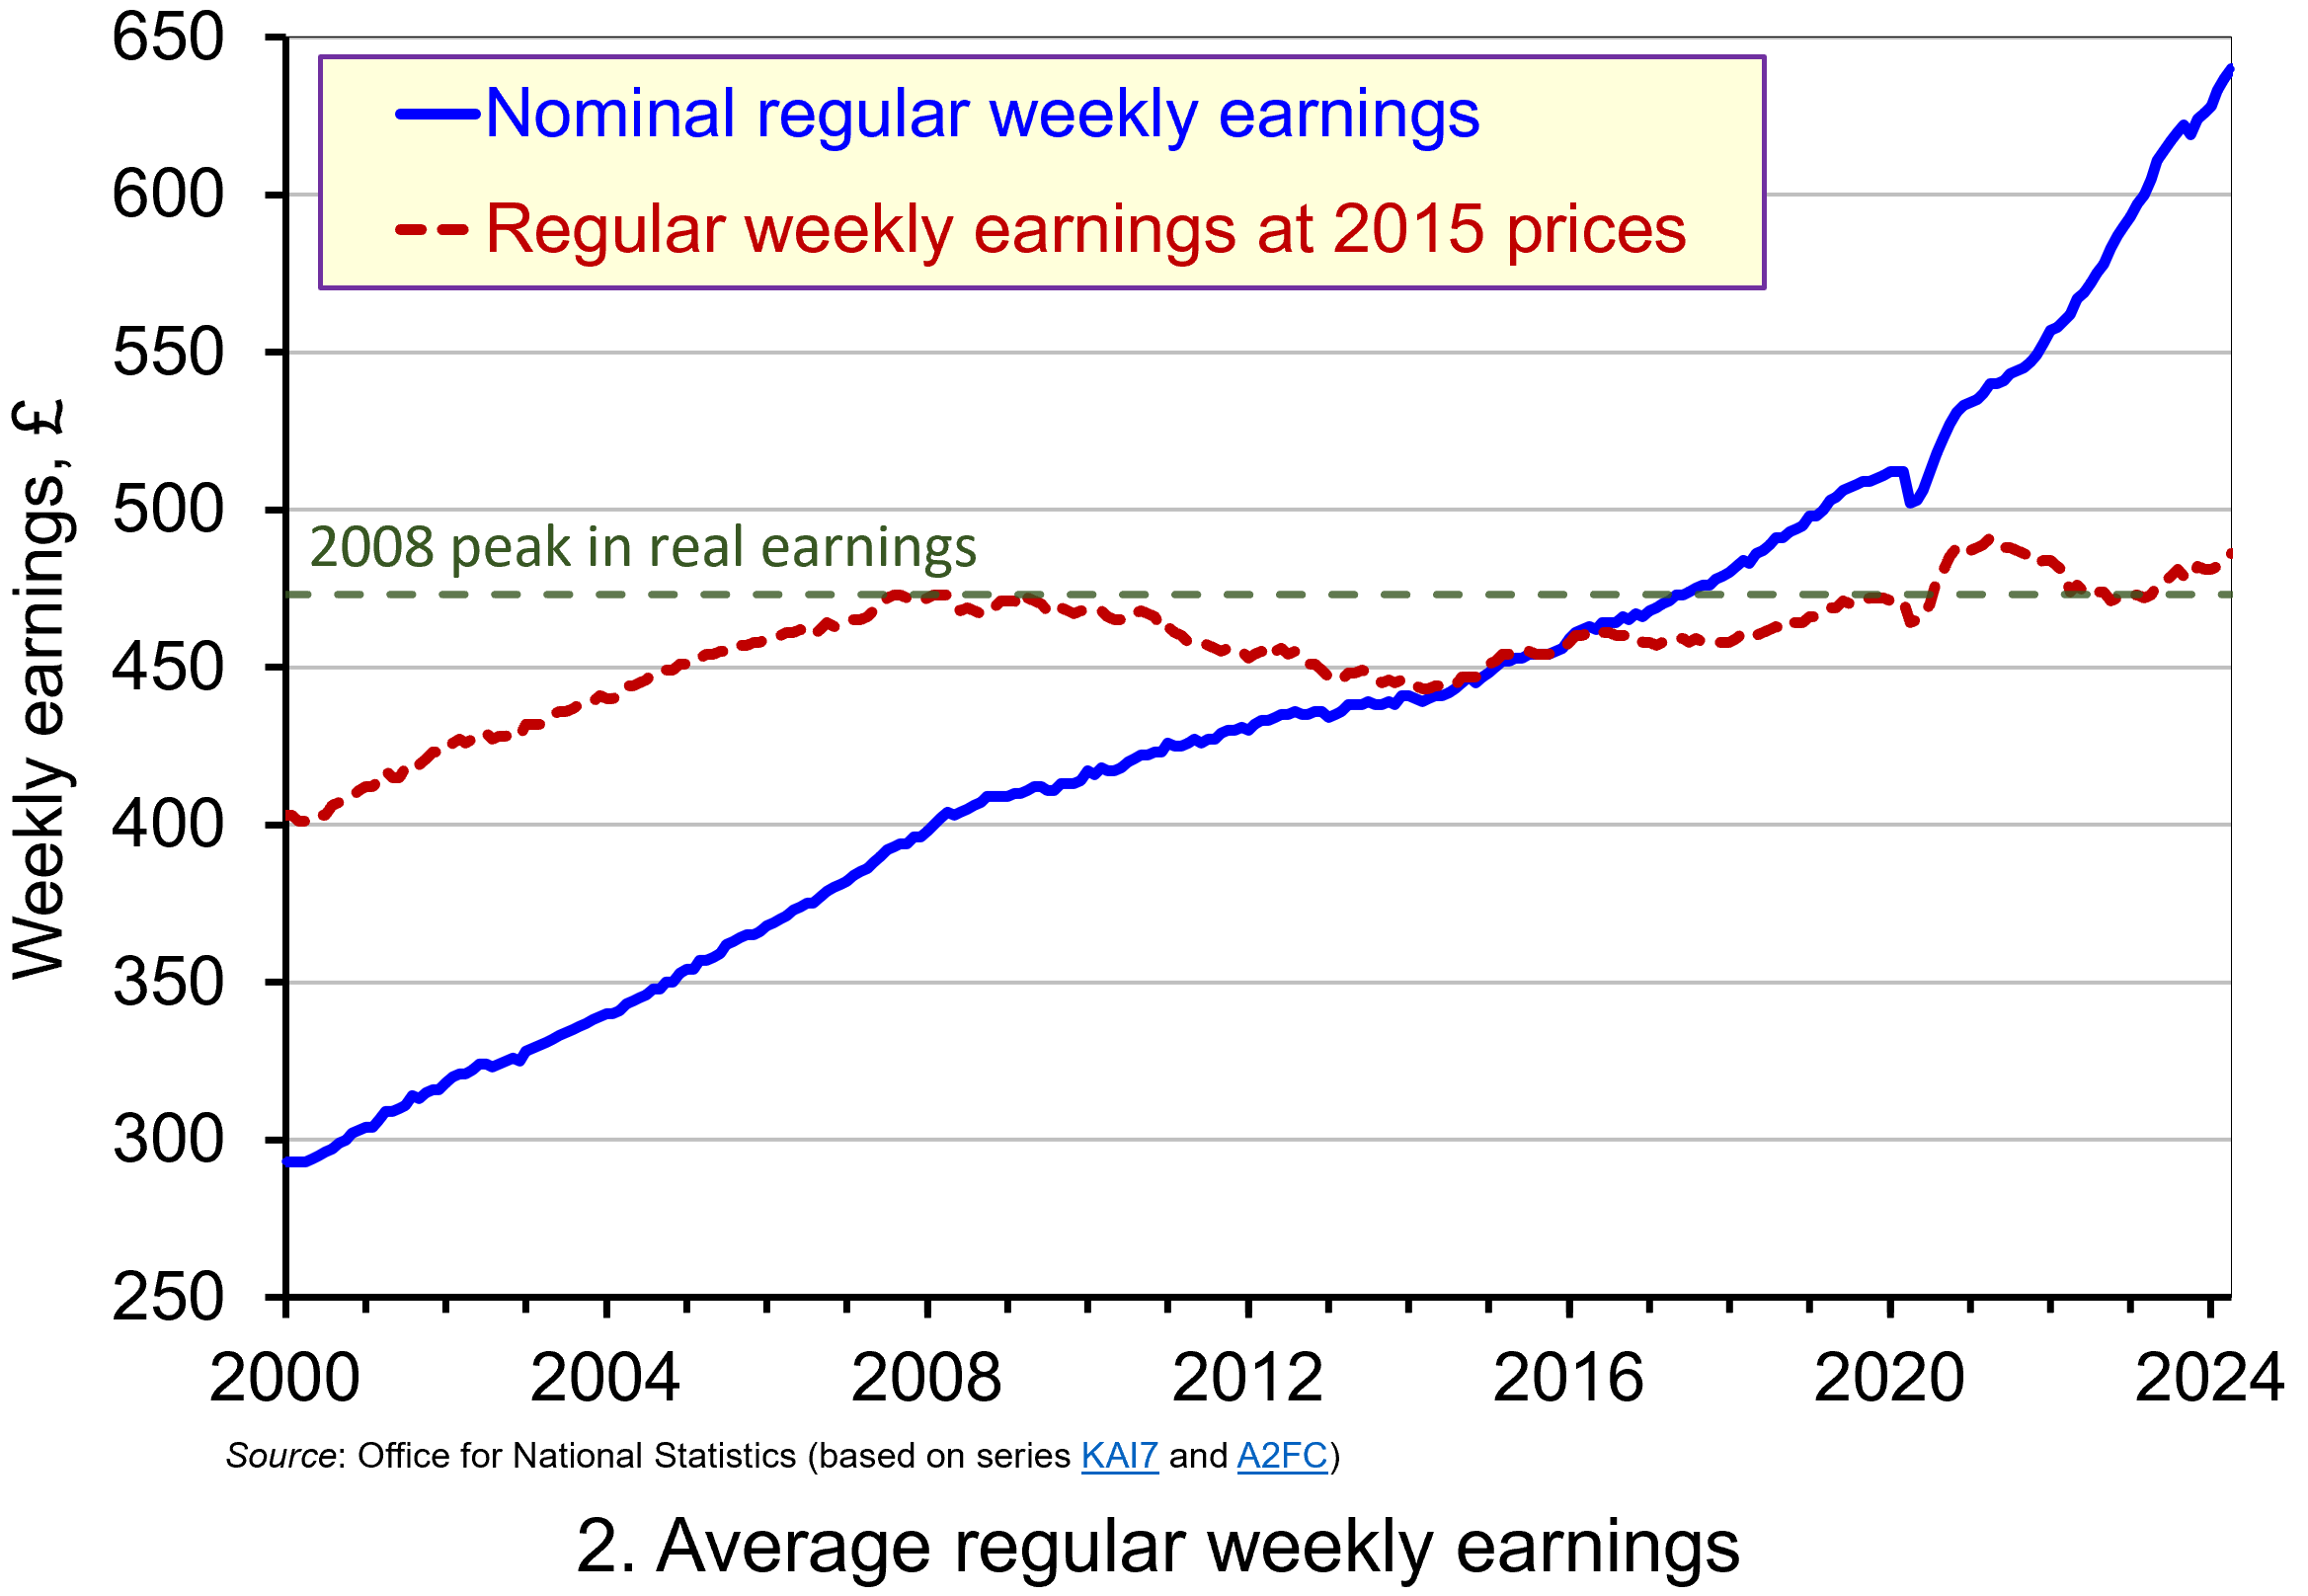 Chart 2 show the average levels of nominal and real weekly pay. The real series is adjusted for inflation. It is calculated by deflating the nominal pay values by the CPIH. Since the CPIH is a price index whose value averages 100 across 2015, the real pay values are at constant 2015 consumer prices. From the chart, we can see that the real value of weekly pay peaked in April 2008 at £473 at 2015 prices. The subsequent period saw rates of pay increases that were lower than rates of consumer price inflation. This meant that by March 2014 the real value of weekly pay had fallen by 6.3 per cent to £443 at 2015 prices. (Click here to download a PowerPoint copy of the chart.)
Although real (inflation-adjusted) pay recovered a little after 2014, 2017 again saw consumer price inflation rates greater than those of pay inflation (see Chart 1). This meant that at the start of 2018 real earnings were 3.2 per cent lower than their 2008-peak (see Chart 2). Real earnings then began to recover, buoyed by the economic rebound following the relaxation of COVID lockdown measures and increasing staffing pressures. Real earnings finally passed their 2008-peak in August 2020. By April 2021 regular weekly pay reached £491 at 2015 prices which was 3.8 per cent above the pre-global financial crisis peak.
However, the boost to real wages was to be short-lived as inflationary pressures rose markedly. While some of this was attributable to the same pressures that were driving up wages, inflationary pressures were fuelled further by the commodity price shock arising from Russia’s invasion of Ukraine and, in particular, its impact on energy prices. This saw the CPIH inflation rate rise to 9.6 per cent in October 2022 (while the CPI inflation rate peaked in the same month at 11.1 per cent). The result was that real weekly earnings fell by 2.7 per cent between January and October 2022 to stand at £471 at 2015 consumer prices. Consequently, average pay was once again below its pre-global financial crisis level.
Although inflationary pressures have recently weakened and real earnings have begun to recover, real regular weekly earnings in April 20024 (£486 at 2015 prices) were a mere 2.7 per cent higher than back in the first half of 2008. This compares to a nominal increase of around 58 per cent over the same period thereby demonstrating the importance of the distinction between nominal and real values in understanding what developments in pay mean for the purchasing power of households.
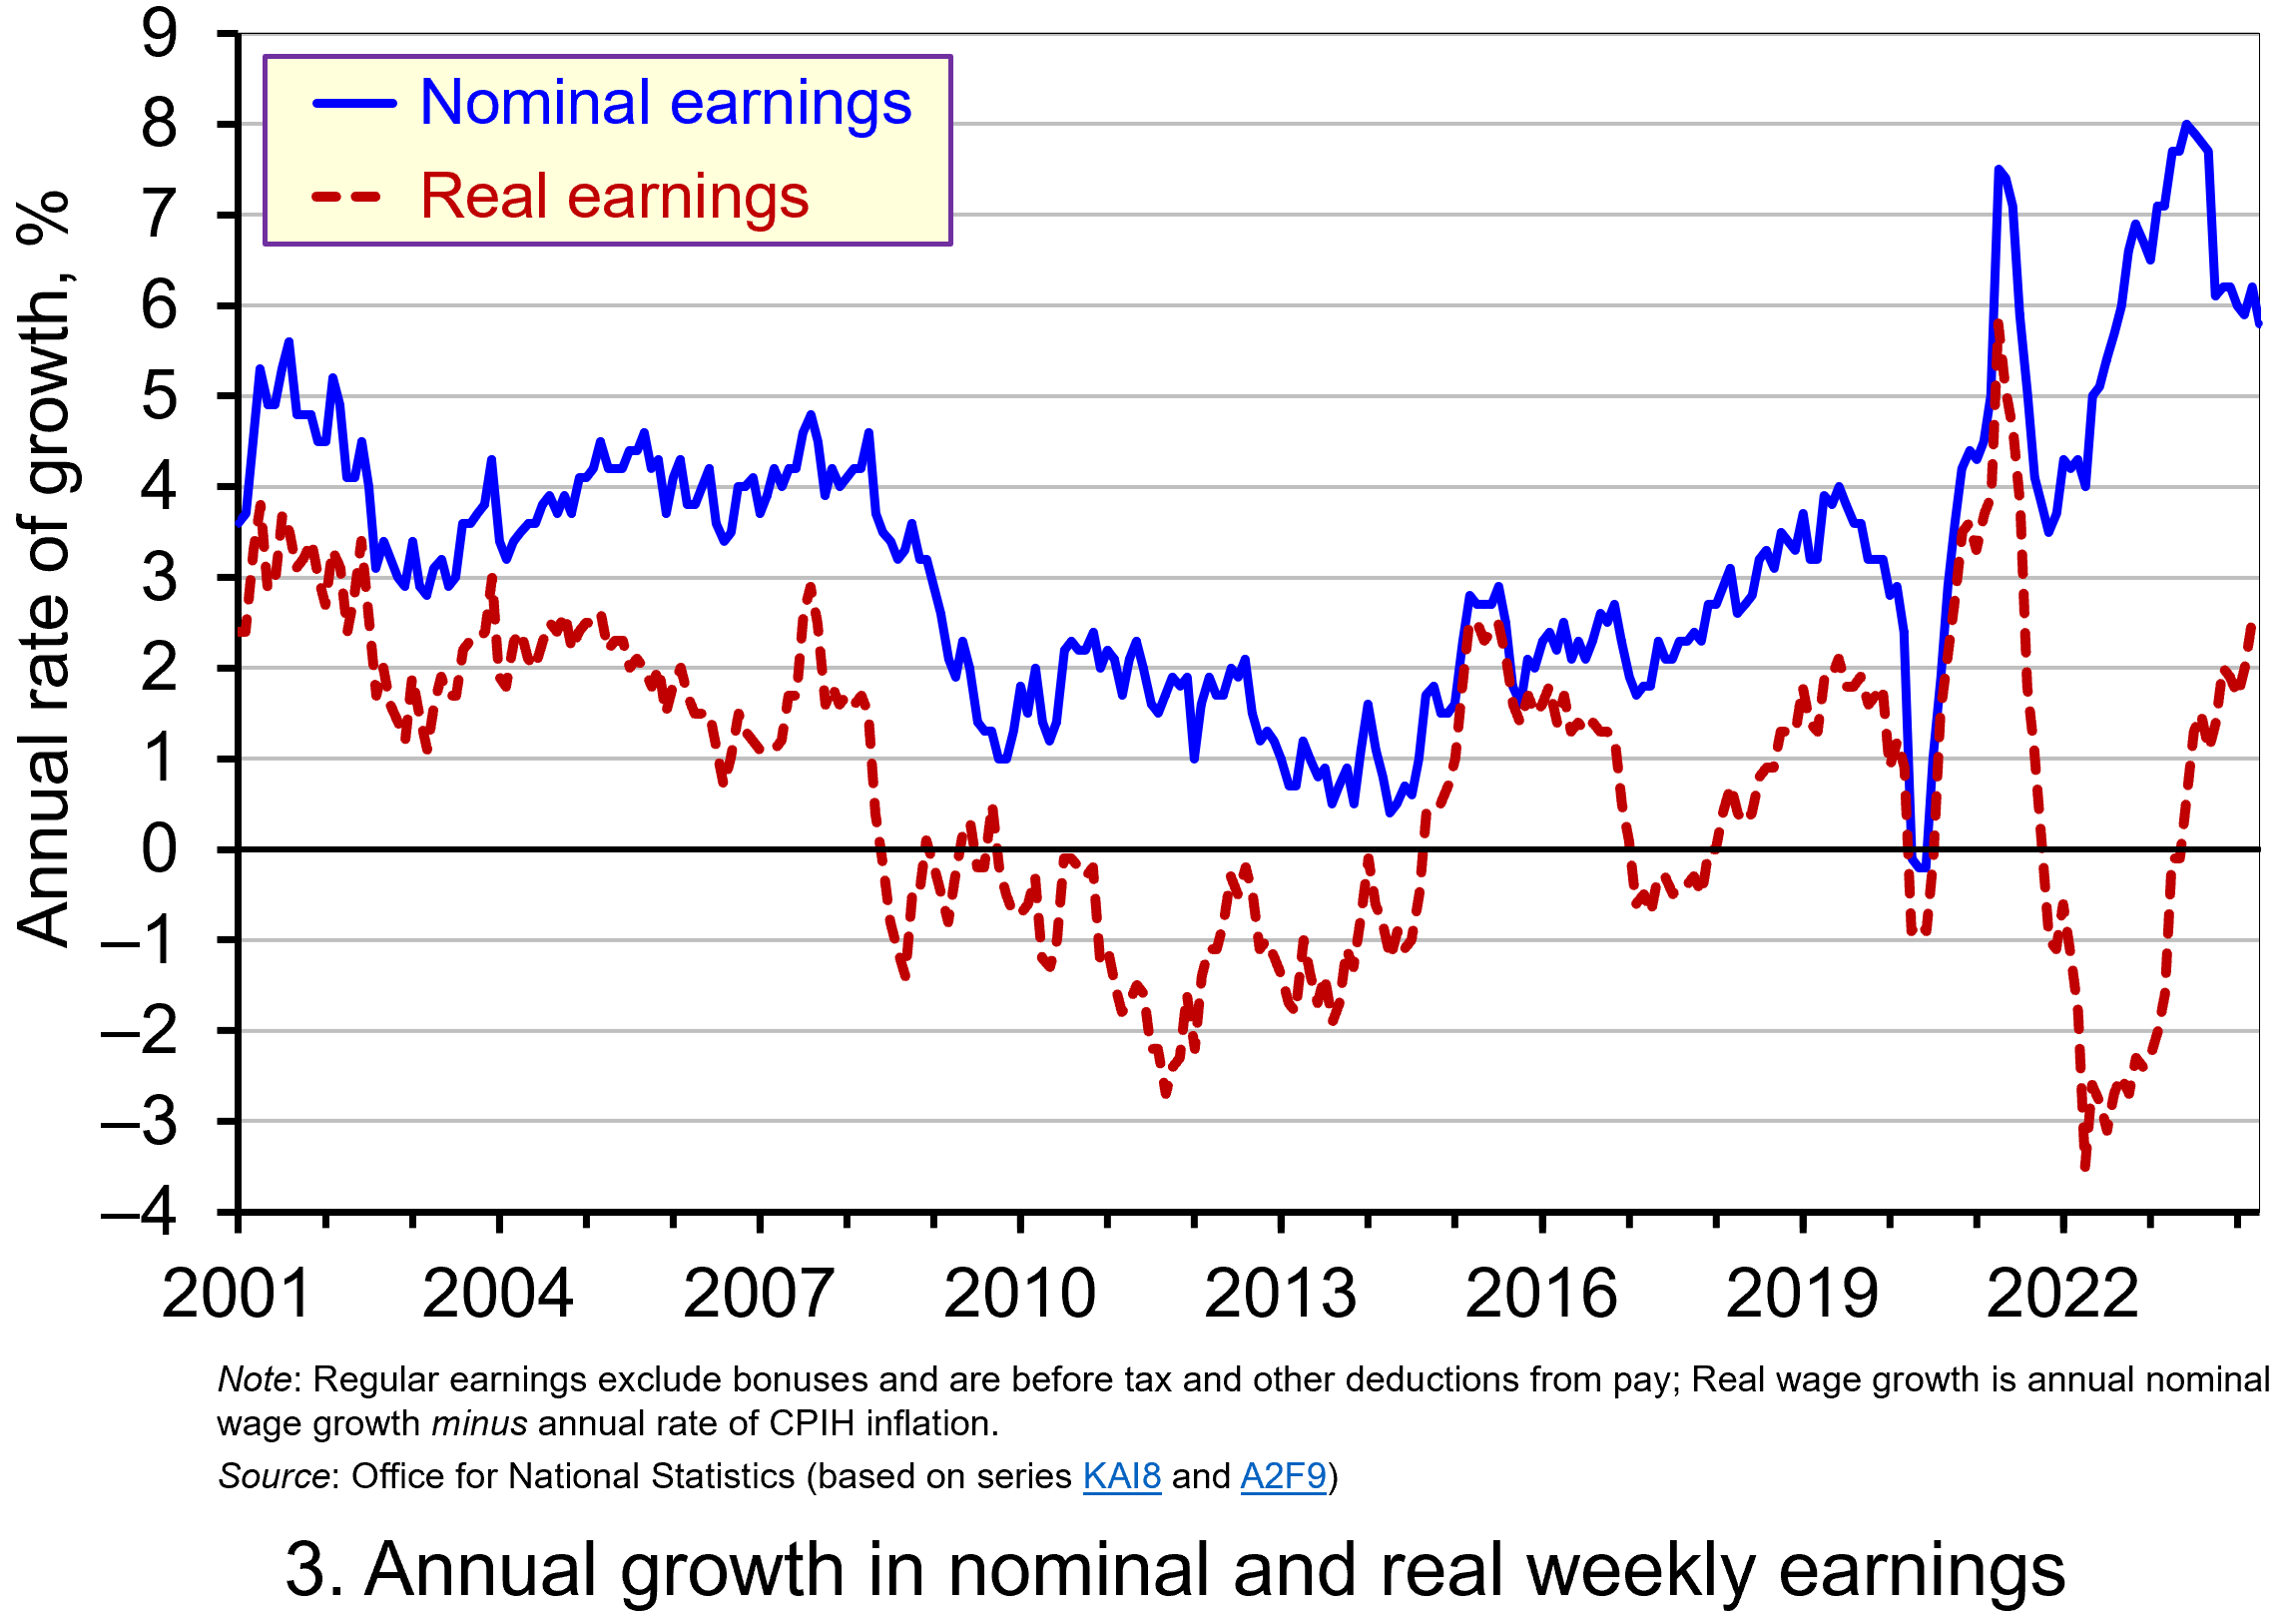 Chart 3 reinforces the importance of the nominal-real distinction. It shows nicely the sustained period of real pay deflation (negative rates of pay inflation) that followed the financial crisis, and the significant rates of real pay deflation associated with the recent inflation shock.
The result is that since June 2008 the average annual rate of growth of real regular weekly pay has been 0.1 per cent, despite nominal pay increasing at an annual rate of 2.9 per cent. In contrast, the period from January 2001 to May 2008 saw real regular weekly pay grow at an annual rate of 2.1 per cent with nominal pay growing at an annual rate of 4.0 per cent. (Click here to download a PowerPoint copy of the chart.)
If we think about the growth of nominal earnings, we can identify two important determinants.
The first is the expected rate of inflation. Workers will understandably want wage growth at least to match the growth in prices so as to maintain their purchasing power.
The second factor is the growth in labour productivity. Firms will be more willing to grant pay increases if workers are more productive, since productivity helps to offset pay increases and maintain firms’ profit margins. Consequently, since over time the actual rate of inflation will tend to mirror the expected rate, the growth of real pay is closely related to the growth of labour productivity. This is significant because, as John discusses in his blog The Productivity Puzzle (14 April 2024), labour productivity growth in the UK, as measured by national output per worker hour, has stalled since the global financial crisis.
Understanding the stagnation of real earnings therefore nicely highlights the interconnectedness of economic variables. In this case, it highlights the connections between productivity, levels of investment and people’s purchasing power. It is not surprising, therefore, that the stagnation of both real earnings and productivity growth since the global financial crisis have become two of the most keenly debated macroeconomic issues of recent times. Indeed, it is likely that their behaviour will continue to shape macroeconomic debates and broader conversations around government policy for some time.
Articles
Questions
- Using the examples of both GDP and earnings, explain how the distinction between nominal and real relates to the distinction between values and volumes.
- In what circumstances would an increase in actual pay translate into a reduction in real pay?
- In what circumstances would a decrease in actual pay translate into an increase in real pay?
- What factors might explain the reduction in real rates of pay seen in the UK following the financial crisis of 2007–8?
- Of what importance might the growth in real rates of pay be for consumption and aggregate demand?
- Why is the growth of real pay an indicator of financial well-being? What other indicators might be included in measuring financial well-being?
- Assume that you have been asked to undertake a distributional analysis of real earnings since the financial crisis. What might be the focus of your analysis? What information would you therefore need to collect?
