Artificial intelligence (AI) has become a key technology in the 21st Century. Businesses use AI systems to analyse data, automate routine tasks, improve customer service, write software, create content and even assist with decision-making. As AI improves and becomes even more capable, governments, economists, businesses and society are debating its effects on productivity, employment and economic growth – and also its potentially extreme dangers.
Some commentators compare AI to earlier technological revolutions such as the steam engine, electricity and the Internet. They argue that AI will continue to increase productivity, create new industries and improve living standards. Others worry that AI may eliminate a large numbers of jobs, increase inequality, concentrate economic power in a few firms and, in the most extreme scenarios, pose a threat to humanity itself.
These debates raise important questions including how society should evaluate the potential risks of a technology whose benefits may be enormous but whose long-term consequences remain uncertain.
AI and the labour market
 Historically, technological change has had both positive and negative effects on employment. Automation reduced the demand for many agricultural workers, while creating jobs in manufacturing. Computers automated clerical tasks but generated entirely new industries in software, telecommunications and digital services.
AI appears likely to follow a similar pattern. According to the World Economic Forum, advances in AI, robotics and information-processing technologies are expected to transform labour markets significantly during the second half of the 2020s, creating demand for new skills while reducing demand for others. The fastest-growing skills are expected to include AI and big data, technological literacy and cybersecurity.
The potential benefits
AI may benefit labour markets in several ways:
- Higher productivity: Workers can complete tasks more quickly with AI assistance.
- New occupations: Demand has emerged for AI engineers, prompt specialists, data scientists and AI governance professionals.
- Better decision-making: Firms can use AI to improve forecasting, inventory management and customer service.
- Complementing human skills: AI may perform repetitive tasks, allowing employees to focus on creativity, problem-solving and interpersonal activities.
- Economic growth: Higher productivity can increase profits, wages and living standards over time.
Many economists argue that AI will not simply replace workers but will change the tasks they perform. Research from the OECD suggests that even highly AI-exposed occupations continue to require management, communication, collaboration and social skills that technologies struggle to replicate.
The potential costs
 At the same time, AI may create significant labour-market challenges. Many white-collar occupations previously considered relatively safe from automation are becoming vulnerable. Generative AI systems can draft reports, analyse legal documents, write computer code and create marketing content. This means that some professional and administrative roles may face considerable disruption.
The World Economic Forum reports that business leaders have differing expectations about the effects of AI. In a 2026 survey (see link below), around 54 per cent expected AI to displace existing jobs, while only 24 per cent expected it to create new jobs within their organisations. Economists have identified several potential problems:
- Structural unemployment: workers in industries that are in decline may struggle to find employment requiring their existing skills.
- Increased income inequality: there may be a growing income disparity between highly skilled and less-skilled workers.
- Growing market power: the largest technology firms that own the most advanced AI systems may see their market power grow further creating dominance in certain areas.
- Regional inequalities: AI-related investment may become concentrated in particular cities and countries, exacerbating regional inequalities within and between countries.
- Pressure on governments: to address issues of structural unemployment and increasing inequality, governments may be forced to expand retraining and social-support programmes.
AI and catastrophic risk
 Most economic discussion around AI focuses on employment and productivity. However, some researchers argue that the most significant risks from AI may be much broader.
Economists distinguish between ordinary risks and catastrophic risks. Catastrophic risks involve events with a very low probability of occurring but potentially enormous consequences. Examples include nuclear accidents, pandemics and certain climate-related disasters.
AI raises similar concerns. Advanced AI systems could potentially be used to conduct cyberattacks, spread misinformation, disrupt critical infrastructure or support the development of dangerous technologies. Some researchers have even suggested that highly advanced AI systems could pose an existential risk to humanity if they become sufficiently powerful and are not properly controlled.
This became a widely discussed topic in the media in September 2026 following the resignation of an employee, Jacob Coxon, from AI firm, Anthropic. He said that people working on AI were ‘genuinely frightened’ about how quickly AI was advancing and what it might mean for the future of humanity. He said:
I believe that if we don’t slow down at the current rate of progress, there is a strong chance that we could all die in the immediate future.
Other researchers have raised similar concerns and there have since been calls from some of the biggest AI companies for regulation of AI to prevent this.
The policy debate and CBA
 All of this creates a challenge for cost-benefit analysis. Suppose AI generates trillions of pounds of economic benefits. But, if there is also a very small probability of catastrophic harm, how should policymakers weigh up the two?
Traditional cost-benefit analysis values risk by multiplying the size of a potential outcome by its probability. However, this approach becomes problematic when both the probability and the consequences are highly uncertain. The risks may be extremely difficult to estimate, while the potential costs could be vast and affect future generations. For this reason, governments and firms increasingly use scenario analysis, stress testing and AI safety assessments to evaluate potential risks. These approaches attempt to prepare for extreme outcomes rather than relying solely on probability calculations.
Supporters of AI argue that technological progress has historically improved living standards and that restricting AI too heavily could reduce innovation and economic growth. Critics argue that uncertainty about potentially catastrophic outcomes justifies a more cautious approach.
The debate therefore extends beyond labour economics to the wider issue of managing catastrophic risk. As with nuclear power or climate change, policymakers must decide how much risk society is willing to accept in exchange for potentially large economic benefits.
Articles
- Why are there concerns AI could threaten humanity, and how real are they?
BBC News, Liv McMahon (17/9/26)
- Two dire warnings, one from Terence Tao, the other from someone who just quit Anthropic
Marcus on AI, Gary Marcus (9/9/26)
- AI insiders fear extinction. Security experts see a familiar fight
Scientific American, Peter Hall (11/9/26)
- US rejects pleas from OpenAI, Anthropic for global AI standards
BBC News, Kali Hays (24/9/26)
- How would AI actually kill all humans? Here are the top 5 scenarios
The Conversation, Toby Walsh (22/9/26)
- Who’s Who In The Fight Over Whether AI Will Kill Us
Forbes, Andréa Morris (24/9/26)
- Why this AI doomsday warning from former Anthropic researcher broke through
The Guardian, Blake Montgomery (15/9/26)
 As AI behavior raises concerns, ex-researcher Jacob Coxon warns what may lie ahead
PBS News
- ‘A setup’: Elon Musk fuels wild theory about Anthropic whistleblower Jacob Coxon
ABC News, Harrison Christian (11/9/26)
- Sam Altman, Dario Amodei urge UN Security Council to adopt international AI standards
CNN, Hadas Gold (24/9/26)
- Not everyone thinks AI will kill us all
CNN, Hadas Gold and Clare Duffy (24/9/26)
- The turbulent AI era is here. The choices we make now are critical.
Gates Notes, Bill Gates (26/8/26)
Reports
Questions
- How might AI increase productivity while also causing unemployment in some sectors? Which sectors are likely to be affected the most?
- Why is it difficult to estimate the costs and benefits of advanced AI?
- Assume that a disaster is estimated to cost society £1000 billion (£1 000 000 000 000). The chances of the disaster occurring are said to be minute, however. Estimates vary from a probability of one in a million to one in a billion. What estimate of this cost would you include in a cost–benefit analysis?
- Why are many low-income countries apparently prepared to accept riskier projects than are high-income ones?
- Discuss whether the greatest economic challenge posed by AI is (a) job displacement; (b) increased inequality; (c) market concentration and the power of large technology firms; or (d) catastrophic long-term risks.
- Read the article by Bill Gates, The turbulent AI era is here. The choices we make now are critical. According to him, what steps should the world take to ensure that ‘AI will be a force for good and leave everyone better off’?
 With businesses increasing their use of AI, this is likely to have significant effects on employment. But how will this affect the distribution of income, both within countries and between countries?
In some ways, AI is likely to increase inequality within countries as it displaces low-skilled workers and enhances the productivity of higher-skilled workers. In other ways, it could reduce inequality by allowing lower-skilled workers to increase their productivity, while displacing some higher-skilled workers and managers through the increased adoption of automated processes.
The effect of AI on the distribution of income between countries will depend crucially on its accessibility. If it is widely available to low-income countries, it could significantly enhance the productivity of small businesses and workers in such countries and help to reduce the income gap with the richer world. If the gains in such countries, however, are largely experienced by multinational companies, whether in mines and plantations, or in labour-intensive industries, such as garment production, few of the gains may accrue to workers and global inequality may increase.
Redistribution within a country
 The deployment of AI may result in labour displacement. AI is likely to replace both manual and white-collar jobs that involve straightforward and repetitive tasks. These include: routine clerical work, such as data entry, filing and scheduling; paralegal work, contract drafting and legal research; consulting, business research and market analysis; accounting and bookkeeping; financial trading; proofreading, copy mark-up and translation; graphic design; machine operation; warehouse work, where AI-enabled warehouse robots do many receiving, sorting, stacking, retrieval, carrying and loading tasks (e.g. Amazon’s Sequoia robotic system); basic coding or document sifting; market research and advertising design; call-centre work, such as enquiry handling, sales, telemarketing and customer service; hospitality reception; sales cashiers in supermarkets and stores; analysis of health data and diagnosis. Such jobs can all be performed by AI assistants, AI assisted robots or chat bots.
Women are likely to be disproportionately affected because they perform a higher share of the administrative and service roles most exposed to AI.
Workers displaced by AI may find that they can find employment only in lower-paid jobs. Examples include direct customer-facing roles, such as bar staff, shop assistants, hairdressers and nail and beauty consultants.
Such job displacement by AI is likely to redistribute income from relatively low-skilled labour to capital: a redistribution from wages to profits. This will tend to lead to greater inequality.
AI is also likely to lead to a redistribution of income towards certain types of high-skilled labour that are difficult to replace with AI but which could be enhanced by it. Take the case of skilled traders, such as plumbers, electricians and carpenters. They might be able to use AI in their work to enhance their productivity, through diagnosis, planning, problem-solving, measurement, etc. but the AI would not displace them. Instead, it could increase their incomes by allowing them to do their work more efficiently or effectively and thus increase their output per hour and enhance their hourly reward. Another example is architecture, where AI can automate repetitive tasks and open up new design possibilities, allowing architects to focus on creativity, flexibility, aesthetics, empathy with clients and ethical decision-making.
An important distinction is between disembodied and embodied AI investment. Disembodied AI investment could include AI ‘assistants’, such as ChatGPT and other software that can be used in existing jobs to enhance productivity. Such investment can usually be rolled out relatively quickly. Although the extra productivity may allow some reduction in the number of workers, disembodied AI investment is likely to be less disruptive than embodied AI investment. The latter includes robotics and automation, where workers are replaced by machines. This would require more investment and may be slower to be adopted.
Then there are jobs that will be created by AI. These include prompt engineers, who develop questions and prompt techniques to optimise AI output; health tech experts, who help organisations implement new medical AI products; AI educators, who train people in the uses of AI in the workplace; ethics advisors, who help companies ensure that their uses of AI are aligned with their values, responsibilities and goals; and cybersecurity experts who put systems in place to prevent AI stealing sensitive information. Such jobs may be relatively highly paid.
 In other cases, the gains from AI in employment are likely to accrue mainly to the consumer, with probably little change in the incomes of the workers themselves. This is particularly the case in parts of the public sector where wages/salaries are only very loosely related to productivity and where a large part of the work involves providing a personal service. For example, health professionals’ productivity could be enhanced by AI, which could allow faster and more accurate diagnosis, more efficient monitoring and greater accuracy in surgery. The main gainers would be the patients, with probably little change in the incomes of the health professionals themselves. Teachers’ productivity could be improved by allowing more rapid and efficient marking, preparation of materials and record keeping, allowing more time to be spent with students. Again, the main gainers would be the students, with little change in teachers’ incomes. Other jobs in this category include social workers, therapists, solicitors and barristers, HR specialists, senior managers and musicians.
Thus there is likely to be a distribution away from lower-skilled workers to both capital and higher-skilled workers who can use AI, to people who work in new jobs created by AI and to the consumers of certain services.
AI will accelerate productivity growth and, with it, GDP growth, but will probably displace workers faster than new roles emerge. This is likely to increase inequality and be a major challenge for society. Can the labour market adapt? Could the effects be modified if people moved to a four- or three-day week? Will governments introduce statutory limits to weekly working hours? Will training and education adapt to the new demands of employers?
Redistribution between countries
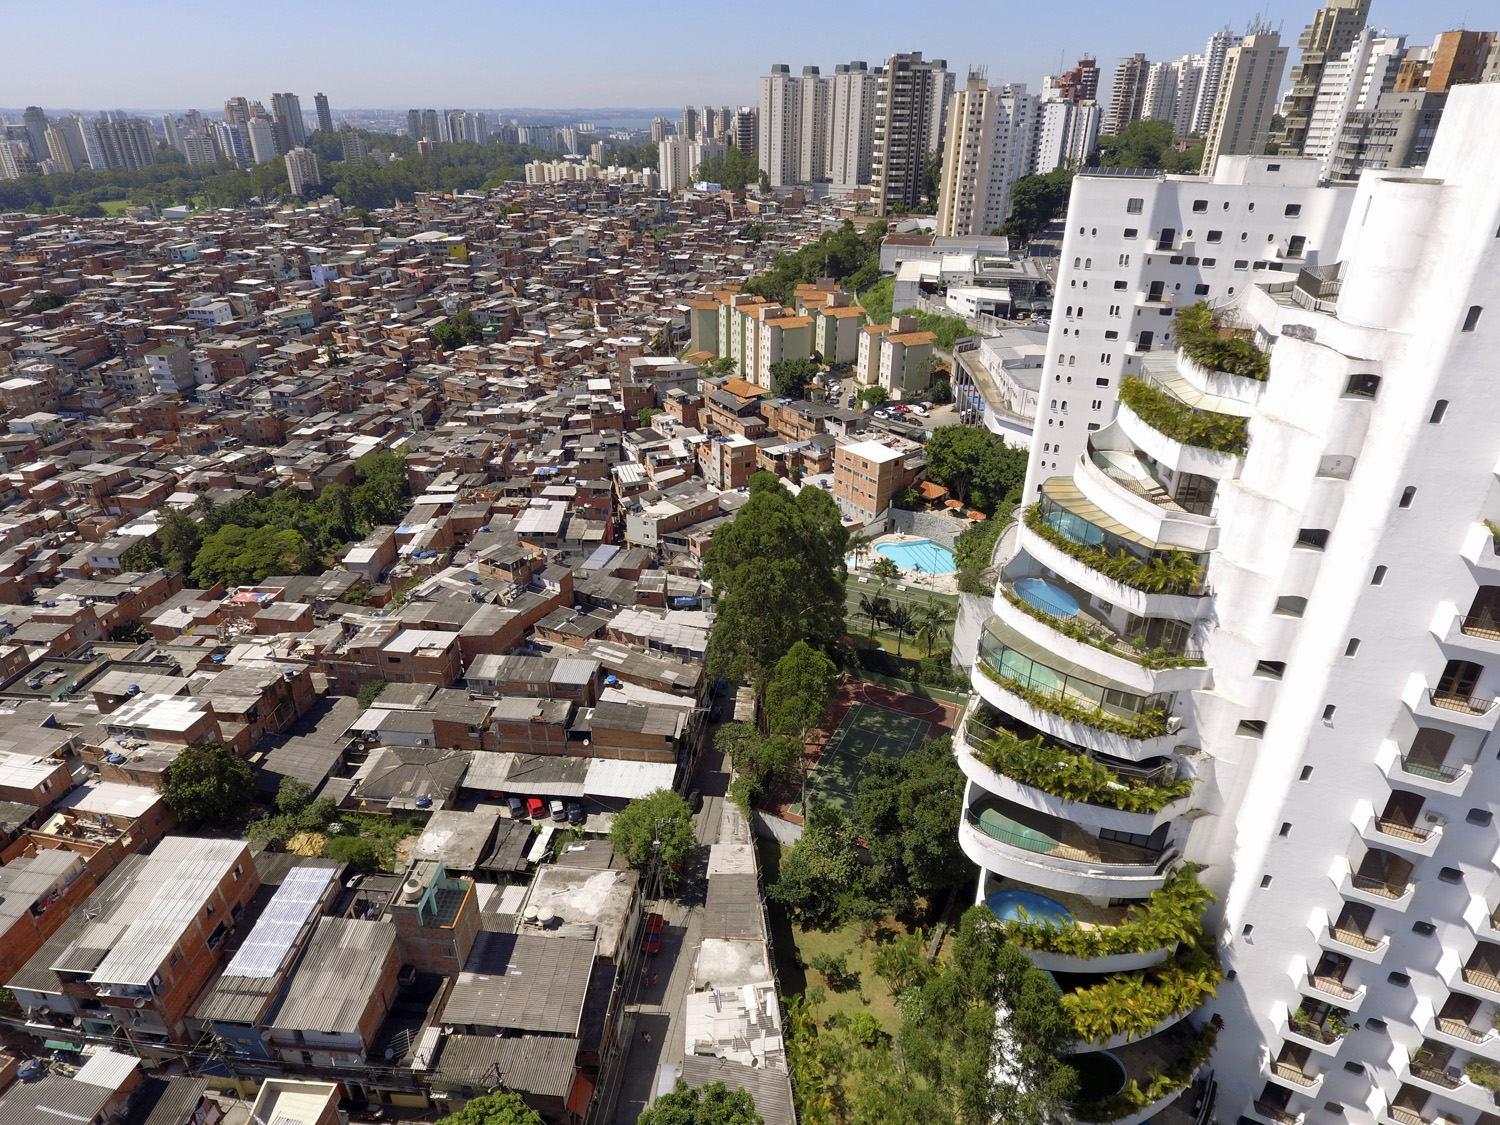 AI threatens to widen the global rich–poor divide. It will give wealthier nations a productivity and innovation edge, which could displace low-skilled jobs in low-income nations. Labour-intensive production could be replaced by automated production, with the capital owned by the multinational companies of just a few countries, such as the USA and China, which between them account for 40% of global corporate AI R&D spending. For some companies, it would make sense to relocate production to rich countries, or certain wealthier developing countries, with better digital infrastructure, advanced data systems and more reliable power supply.
For other companies, however, production might still be based in low-income countries to take advantage of low-cost local materials. But there would still be a redistribution from wages in such countries to the profits of multinationals.
But it is not just in manufacturing where low-income countries are vulnerable to the integration of AI. Several countries, such as India, the Philippines, Mexico and Egypt have seen considerable investment in call centres and IT services for business process outsourcing and customer services. AI now poses a threat to employment in this industry as it has the potential to replace large numbers of workers.
AI-related job losses could exacerbate unemployment and deepen poverty in poorer countries, which, with limited resources, limited training and underdeveloped social protection systems, are less equipped to absorb economic and social shocks. This will further widen the global divide. In the case of embodied AI investment, it may only be possible in low-income countries through multinational investment and could displace many traditional jobs, with much of the benefit going in additional multinational profit.
But it is not all bad news for low-income countries. AI-driven innovations in healthcare, education, and agriculture, if adopted in poor countries, can make a significant contribution to raising living standards and can slow, or even reverse, the widening gap between rich and poor nations. Some of the greatest potential is in small-scale agriculture. Smallholders can boost crop yields though precision farming powered by AI; AI tools can help farmers buy seeds, fertilisers and animals and sell their produce at optimum times and prices; AI-enabled education tools can help farmers learn new techniques.
Articles
- New Skills and AI Are Reshaping the Future of Work
IMF Blog, Kristalina Georgieva (14/1/26)
- Generative AI: degenerative for jobs?
Bank Underground, Bank of England blog, Edward Egan (22/1/26)
- Artificial intelligence (AI) and employment
UK Parliament Research Briefing Lydia Harriss and Sam Money-Kyrle (23/12/25)
- Is Your Job AI-Proof? What to Know About AI Taking Over Jobs
Built In, Matthew Urwin (27/8/25)
- AI likely to displace jobs, says Bank of England governor
BBC News, Michael Race (19/12/25)
- These Jobs Will Fall First as AI Takes Over the Workplace
Forbes, Jack Kelly (30/4/25)
- Disrupted or displaced? How AI is shaking up jobs
exec-appointments.com, Anjli Raval (9/7/25)
- Navigate the economic risks and challenges of generative AI
EY-Parthenon, Lydia Boussour (25/6/24)
- AI Isn’t Increasing Inequality; It’s Revealing the Gaps We Haven’t Wanted to See
HR News, Mark Abbott (18/12/25)
- AI promises efficiency, but it’s also amplifying labour inequality
The Conversation, Mehnaz Rafi (3/12/25)
- 10 Jobs AI Will Replace in 2025
Live Career, Marta Bongilaj (29/12/25)
- From steam to Silicon: Why inequality persists
Aik News HD (Pakistan), Ahmed Fawad Farooq (27/12/25)
- Rethinking AI’s role in income inequality
PwC: The Leadership Agenda (4/9/25)
- How Europe Can Capture the AI Growth Dividend
IMF Blog, Florian Misch, Ben Park, Carlo Pizzinelli and Galen Sher (20/11/25)
- The Next Great Divergence
UNDP: Asia and the Pacific (2/12/25)
- AI risks sparking a new era of divergence as development gaps between countries widen, UNDP report finds
UNDP Press Release (2/12/25)
- AI threatens to widen inequality among states: UN
Aljazeera (2/12/25)
- AI risks deepening inequality, says head of world’s largest SWF
Financial Times, James Fontanella-Khan and Sun Yu (23/11/25)
- Three Reasons Why AI May Widen Global Inequality
Center for Global Development, Philip Schellekens and David Skilling (17/10/24)
- AI Will Transform the Global Economy. Let’s Make Sure It Benefits Humanity
IMF Blog, Kristalina Georgieva (14/1/24)
- AI’s $4.8 trillion future: UN Trade and Development alerts on divides, urges action
UNCTAD Press Release (7/4/25)
- AI could affect 40% of jobs and widen inequality between nations, UN warns
CNBC, Dylan Butts (4/4/25)
Questions
- What types of job are most vulnerable to AI?
- How will AI change the comparative advantage of low-income countries and what effect will it be likely to have on the pattern of global trade?
- Assess alternative policies that governments in high-income countries can adopt to offset the growth in inequality caused by the increasing use of AI.
- What policies can governments in low-income countries or aid agencies adopt to offset the growth in inequality within low-income countries and between high- and low-income countries?
- How might the growth of AI affect your own approach to career development?
- Is AI likely to increase or decrease economic power? Explain.
The share prices of various AI-related companies have soared in this past year. Recently, however, they have fallen – in some cases dramatically. Is this a classic case of a bubble that is bursting, or at least deflating?
Take the case of NVIDIA, the world’s most valuable company, with a market capitalisation of around $4.2 trillion (at current share prices). It designs and produces graphics cards and is a major player in AI. From a low of $86.62 April this year, its share price rose to a peak of $212.19 on 29 October. But then began falling as talk grew of an AI bubble. Despite news on 19 November that its 2025 Q3 earnings were up 62% to $57.0bn, beating estimates by 4%, its share price, after a temporary rise, began falling again. By 21 November, it was trading at around $180.
Other AI-related stocks have seen much bigger rises and falls. One of the biggest requirements for an AI revolution is data processing, which uses huge amounts of electricity. Massive data centres are being set up around the world. Several AI-related companies have been building such data centres. Some were initially focused largely on ‘mining’ bitcoin and other cryptocurrencies (see the blog, Trump and the market for crypto). But many are now changing focus to providing processing power for AI.
 Take the case of the Canadian company, Bitfarms Ltd. As it says on its site: ‘With access to multiple energy sources and strategic locations, our U.S. data centers support both mining and high-performance computing growth opportunities’. Bitfarms’ share price was around CAD1.78 in early August this year. By 15 October, it had reached CAD9.27 – a 421% increase. It then began falling and by 24 November was CAD3.42 – a decline of over 63%.
Data centres do have huge profit potential as the demand for AI increases. Many analysts are arguing that the current share price of data centres undervalues their potential. But current profits of such companies are still relatively low, or they are currently loss making. This then raises the question of how much the demand for shares, and hence their price, depends on current profits or future potential. And a lot here depends on sentiment.
If people are optimistic, they will buy and this will lead to speculation that drives up the share price. If sentiment then turns and people believe that the share price is overvalued, with future profits too uncertain or less than previously thought, or if they simply believe that the share price has overshot the value that reflects a realistic profit potential, they will sell and this will lead to speculation that drives down the share price
 The dot.com bubble of the late 1990s/early 2000s is a case in point. There was a stock market bubble from roughly 1995 to 2001, where speculative investment in internet-based companies caused their stock values to surge, peaking in late 1999/early 2000. There was then a dramatic crash. But then years later, many of these companies’ share prices had risen well above their peak in 2000.
Take the case of Amazon. In June 1997, its share price was $0.08. By mid-December 1999, it had reached $5.65. It then fell, bottoming out at $0.30 in September 2001. The dot-com bubble had burst.
But the potential foreseen in many of these new internet companies was not wrong. After 2001, Amazon’s share price began rising once more. Today, Amazon’s shares are trading at over $200 – the precise value again being driven largely by the company’s performance and potential and by sentiment.
So is the boom in AI-related stock a bubble? Given that the demand for AI is likely to continue growing rapidly, it is likely that the share price of companies providing components and infrastructure for AI is likely to continue growing in the long term. But just how far their share prices will fall in the short term is hard to call. Sentiment is a fickle thing.
Articles
Questions
- Using a supply and demand diagram, illustrate how speculation can drive up the share price of a company and then result in it falling.
- What is meant by overshooting in a market? What is the role of speculation in this process?
- Does a rapid rise in the price of an asset always indicate a bubble? Explain.
- What are the arguments for suggesting that markets are/are not experiencing an AI share price bubble? Does it depend of what part of the AI market is being considered?
- What is meant by the market capitalisation of a company? Is it a good basis for deciding whether or not a company’s share price is a true reflection of the company’s worth? What other information would you require?
- Find out what has been happening to the price of Bitcoin. What factors determine the price of Bitcoin? Do these factors make the price inherently unstable?
 The productivity gap between the UK and its main competitors is significant. In 2024, compared to the UK, output per hour worked was 10.0% higher in France, 19.8% higher in Germany and 41.1% higher in the USA. These percentages are in purchasing-power parity terms: in other words, they reflect the purchasing power of the respective currencies – the pound, the euro and the US dollar.
GDP per hour worked (in PPP terms) is normally regarded as the best measure of labour productivity. An alternative measure is GDP per worker, but this does not take into account the length of the working year. Using this measure, the gap with the USA is even higher as workers in the USA work longer hours and have fewer days holiday per year than in the UK.
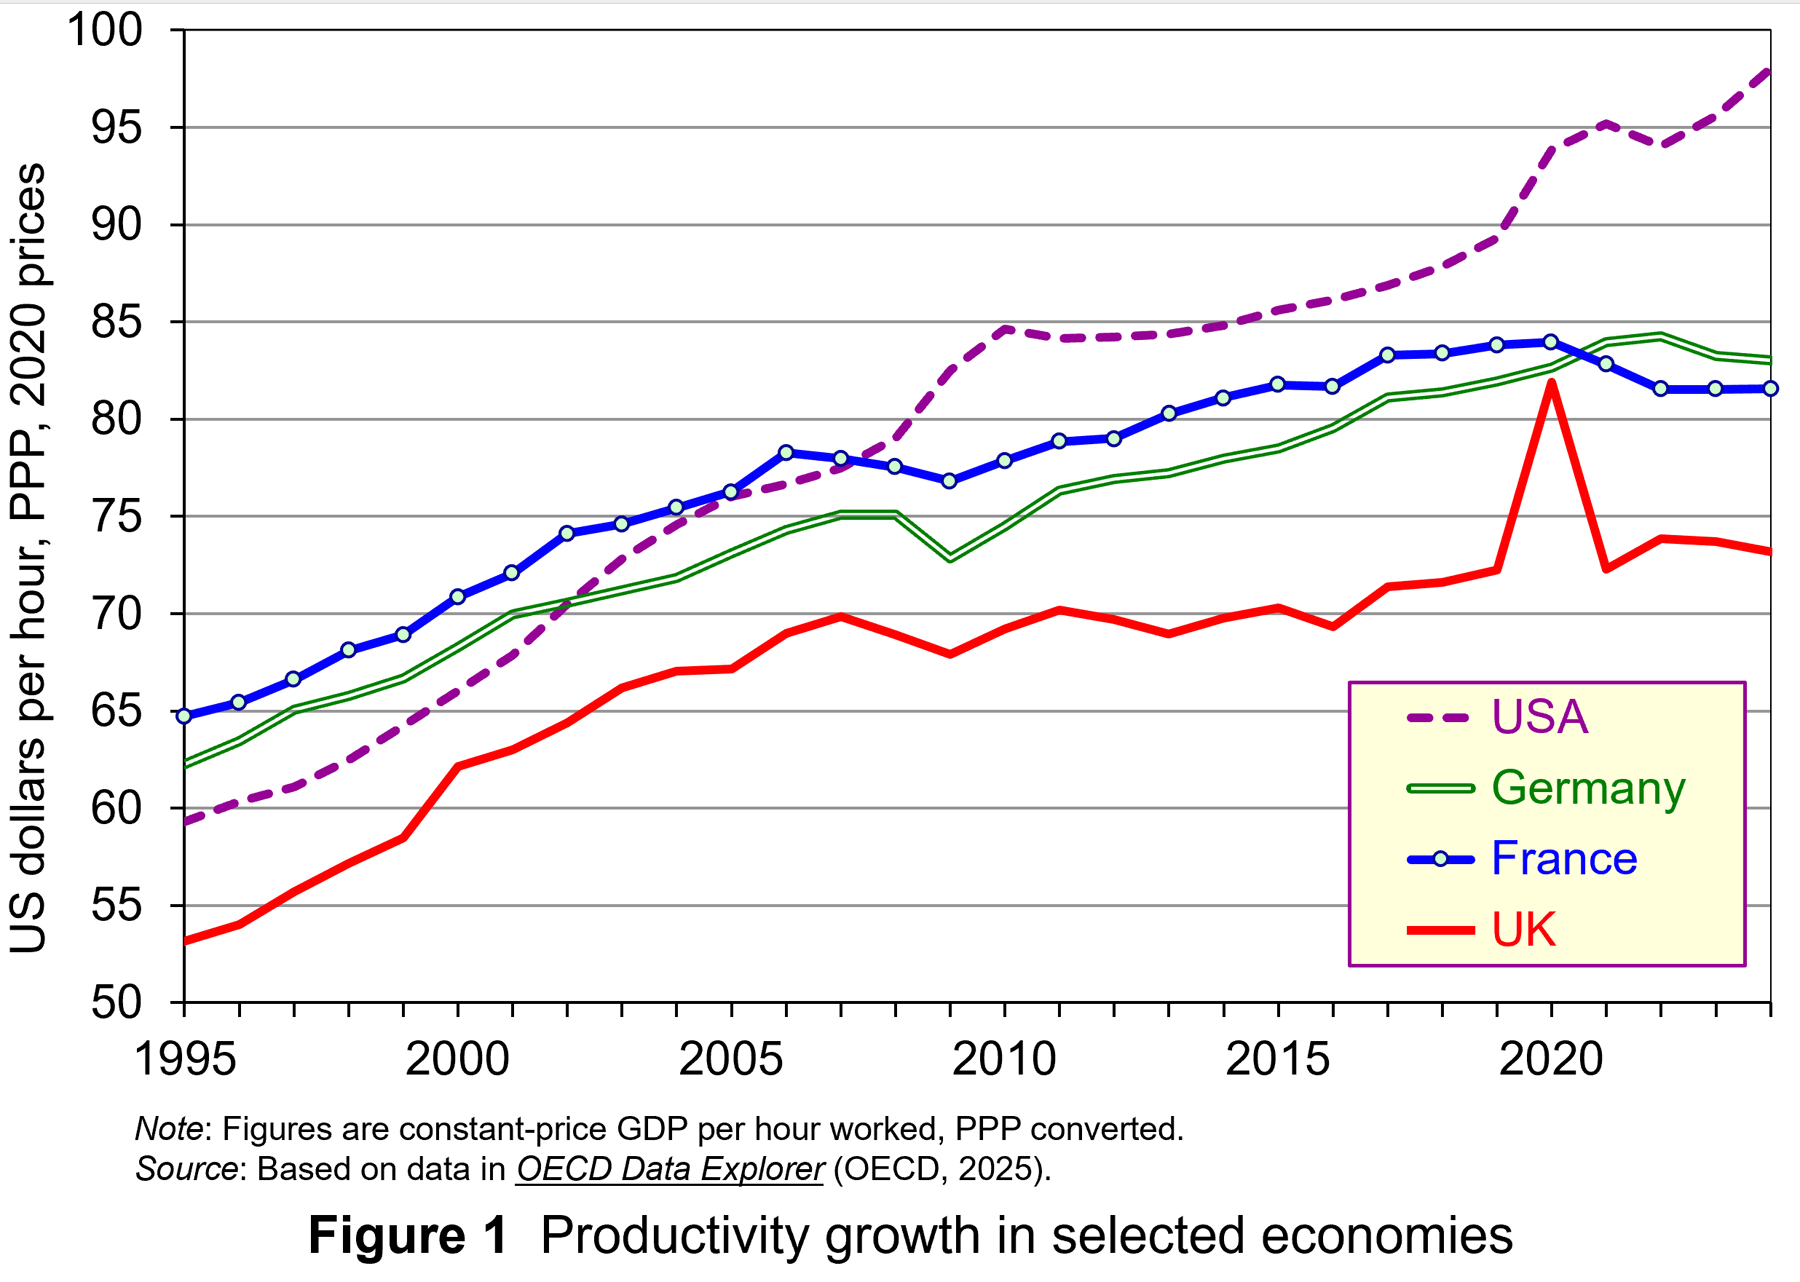 The productivity gap is not a new phenomenon. It has been substantial and growing over the past 20 years. (The exception was in 2020 during lockdowns when many of the least productive sectors, such as hospitality, were forced to close temporarily.)
The productivity gap is shown in the two figures. Both figures show labour productivity for the UK, France, Germany and the USA from 1995 to 2024.
Figure 1 shows output (GDP) per hour, measured in US dollars in PPP terms.
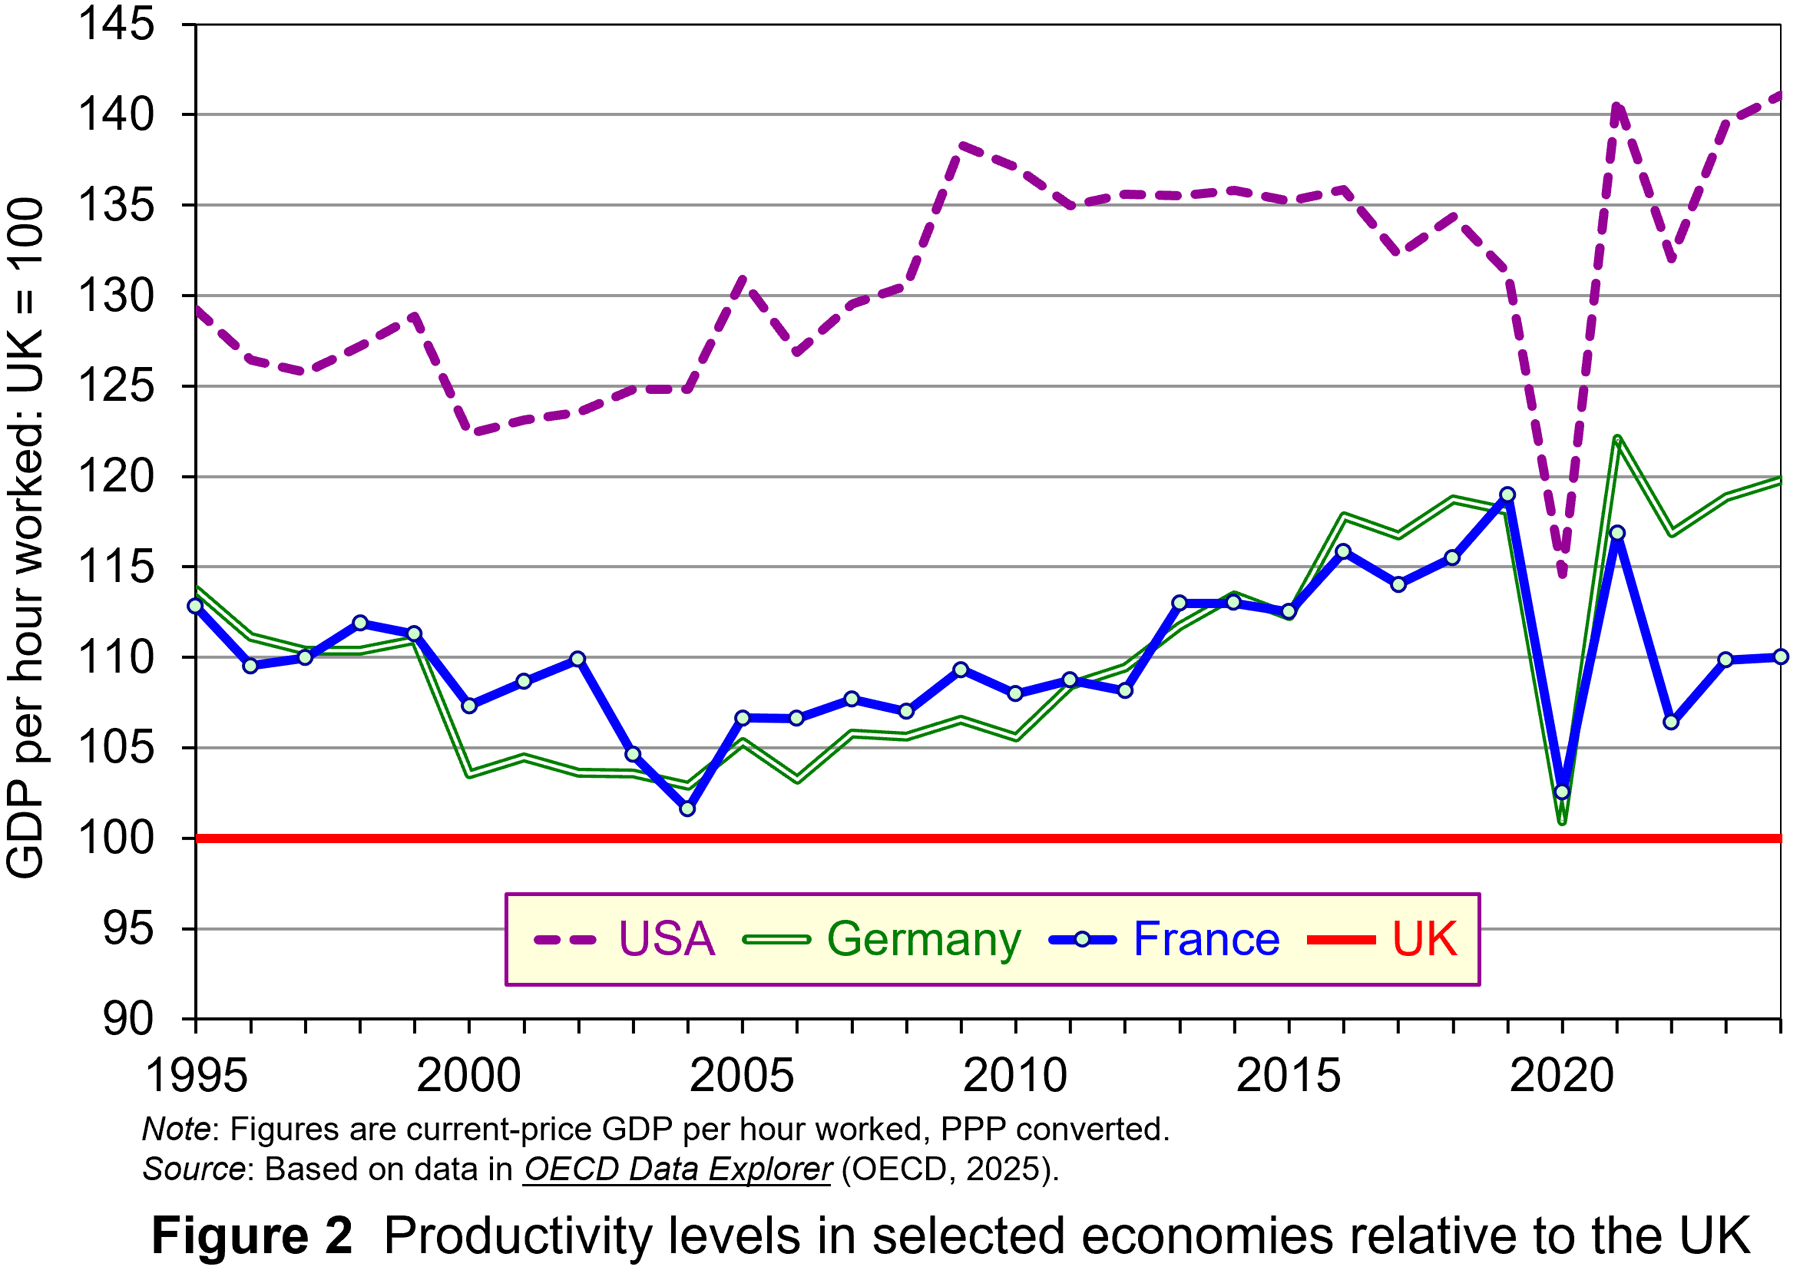 Figure 2 shows output (GDP) per hour relative to the UK, with the UK set at 100. The gap narrowed somewhat up to the early 2000s, but since then has widened.
Low UK productivity has been a source of concern for UK governments and business for many years. Not only does it constrain the growth in living standards, it also make the UK less attractive as a source of inward investment and less competitive internationally.
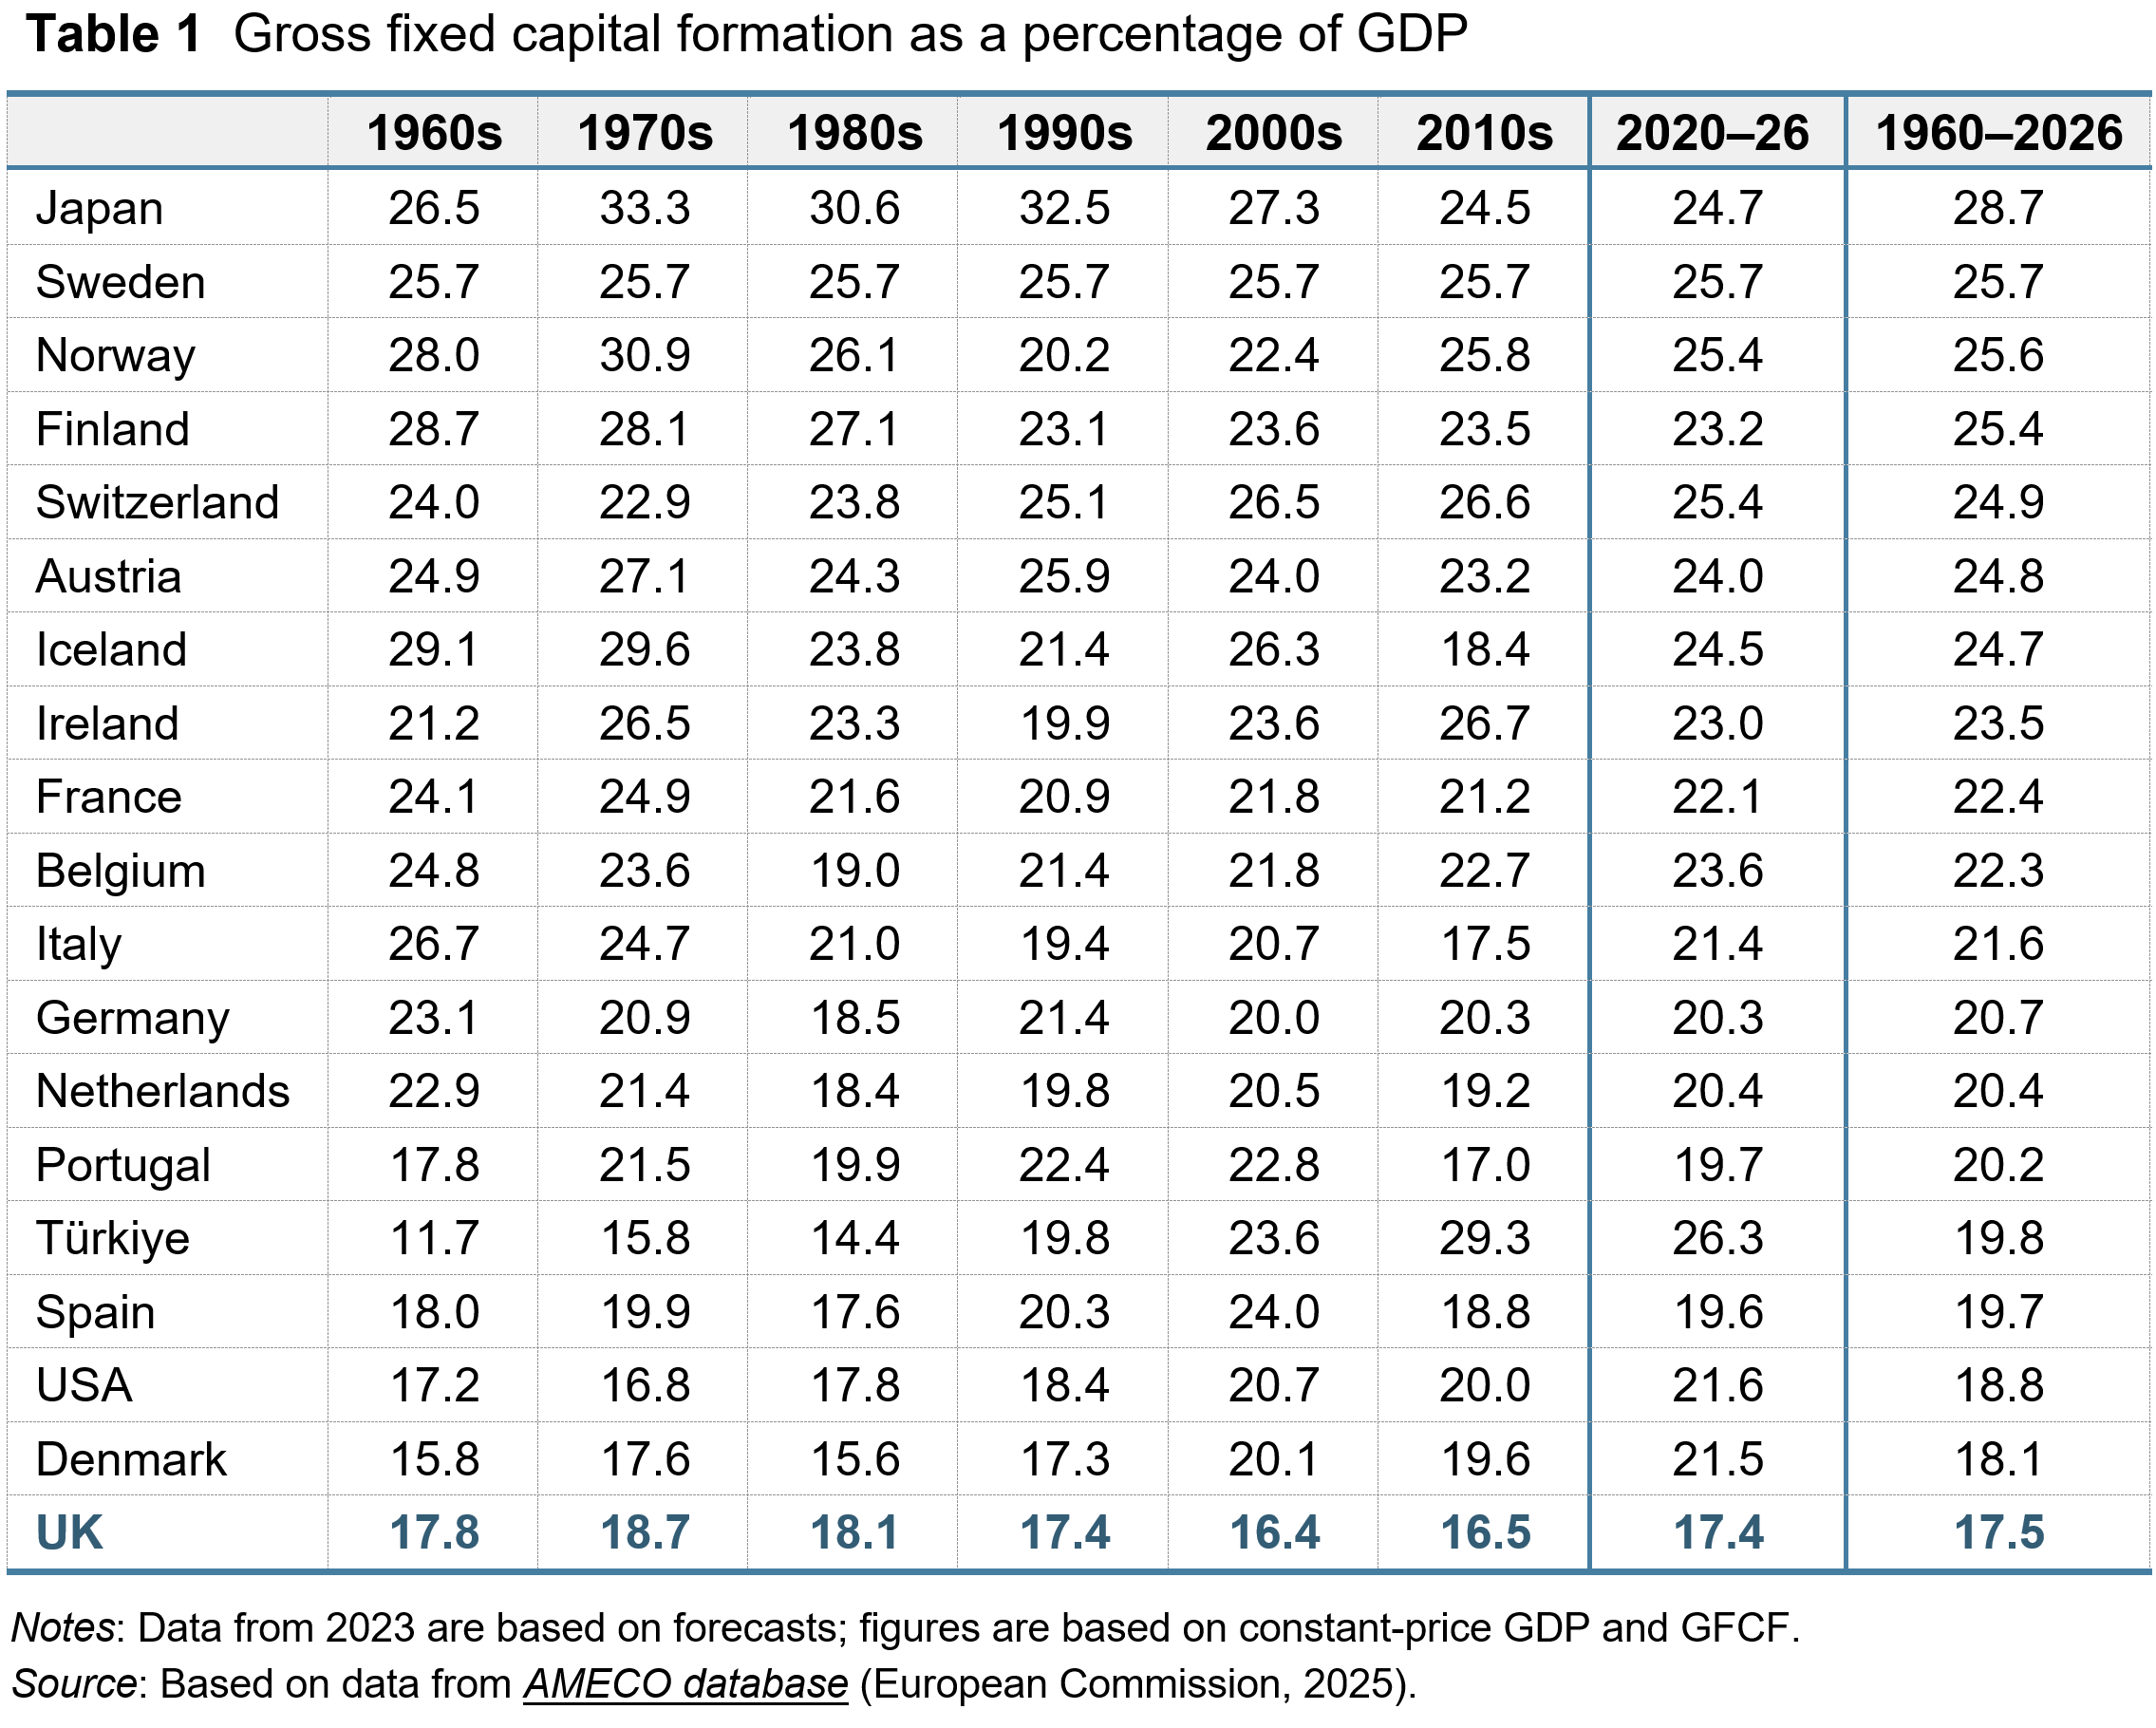
Part of the reason for low UK productivity compared to that in other countries is a low level of investment. As a proportion of GDP, the UK has persistently had the lowest, or almost the lowest, level of investment of its major competitors. This is illustrated in Table 1.
It is generally recognised by government, business and economists that if the economy is to be successful, the productivity gap must be closed. But there is no ‘quick fix’. The policies necessary to achieve increased productivity are long term. There is also a recognition that the productivity problem is a multi-faceted one and that to deal with it requires policy initiatives on a broad front: initiatives that encompass institutional changes as well as adjustments in policy.
So what can be done to improve productivity and how can this be achieved at the micro as well as the macro level?
Improving productivity: things that government can do
 Encouraging investment. Over the years, UK governments have increased investment allowances, enabling firms to offset the cost of investment against pre-tax profit, thereby reducing their tax liability. For example, in the UK, companies can offset a multiple of research and development costs against corporation tax. The rate of relief for small and medium-sized enterprises (SMEs) allows companies that work in science and technology to deduct an extra 86% of their qualifying expenditure from their trading profit in addition to the normal 100% deduction: i.e. a total of 186% deduction. Meanwhile, since April 2016, larger companies have been able to claim a R&D expenditure credit, initially worth 11 per cent of R&D expenditures, then 12 per cent from 2018 and 13 per cent from 2020. This was then raised to 20 per cent from 2023.
Strengthening competition. A number of studies have revealed that, with increasing market share, business productivity growth slows. As a result, government policy sought to strengthen competition policy. The Competition Act 1998, which came into force in March 2000, and the Enterprise Act of 2002, enhanced the powers of the Office of Fair Trading (OFT) (a predecessor to the Competition and Markets Authority) in respect to dealing with anti-competitive practices. It was given the ability to impose large fines on firms which had been found guilty of exploiting a dominant market position. Today, one of the strategic goals of the Competition and Markets Authority (CMA) is the aim of ‘extending competition frontiers’ in order to improve the way competition works.
Encouraging an enterprise culture. The creation of an enterprise culture is seen as a crucial factor not only to encourage innovation but also to stimulate technological progress. Innovation and technological progress are crucial to sustaining growth and raising living standards. The UK government launched the Small Business Service in April 2000, later renamed Business and Industry. Its role is to co-ordinate small-business policy within government and liaise with business, providing advice and information. However, according to the OECD, there remains considerable scope for increasing the level of government support for entrepreneurship in the UK.
Improving productivity: things that organisations can do
In the podcast from the BBC’s The Bottom Line series, titled ‘Productivity: How Can British Business Work Smarter’ (see link below), Evan Davis and guests discuss what productivity really looks like in practice – from offices and factories, to call centres and operating theatres.’ The episode identifies a number of ways in which labour productivity can be improved. These include:
- People could work harder;
- Workers could be better trained and more skilled and thus able to produce more per hour;
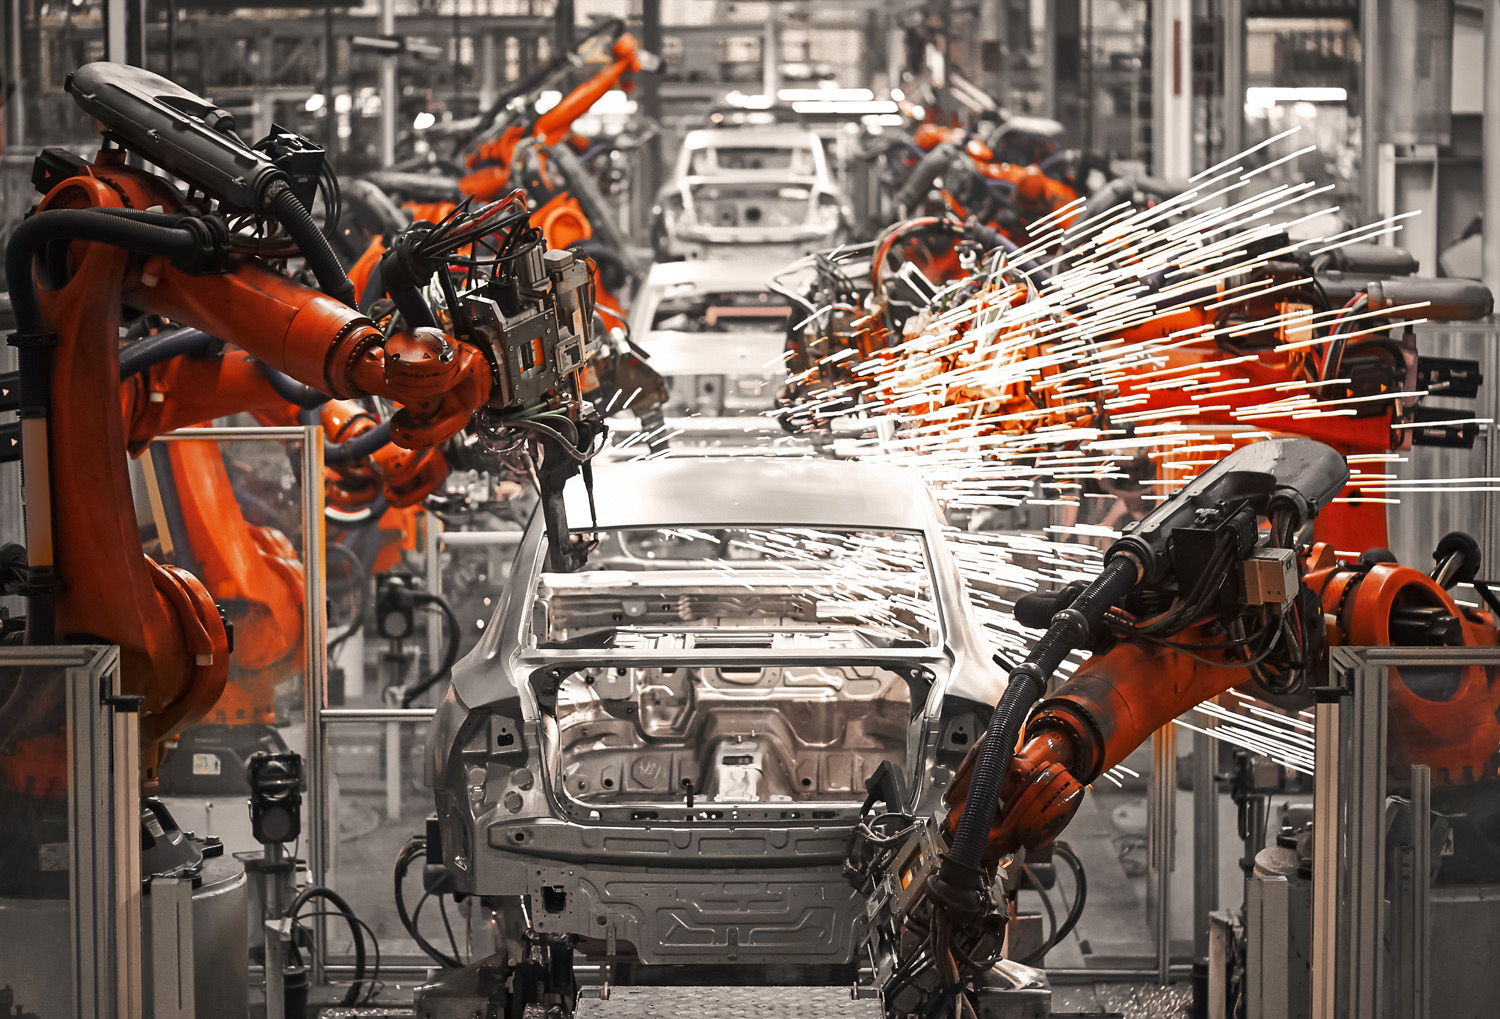
- Capital could be increased so that workers have more equipment or tools to enable them to produce more, or there could be greater automation, releasing labour to work on other tasks;
- Workplaces could be arranged more efficiently so that less time is spent moving from task to task;
- Systems could put in place to ensure that tasks are done correctly the first time and that time is not wasted having to repeat them or put them right;
- Workers could be better incentivised to work efficiently, whether through direct pay or promotion prospects, or by increasing job satisfaction or by management being better attuned to what motivates workers and makes them feel valued;
- Firms could move to higher-value products, so that workers produce a greater value of output per hour.
The three contributors to the programme discuss various initiatives in their organisations (an electronics manufacturer, NHS foundation trusts and a provider of office services to other organisations).
 They also discuss the role that AI plays, or could play, in doing otherwise time-consuming tasks, such as recording and paying invoices and record keeping in offices; writing grants or producing policy documents; analysing X-ray results in hospitals and performing preliminary diagnoses when patients present with various symptoms; recording conversations/consultations and then sorting, summarising and transcribing them; building AI capabilities into machines or robots to enable them to respond to different specifications or circumstances; software development where AI writes the code. Often, there is a shortage of time for workers to do more creative things. AI can help release more time by doing a lot of the mundane tasks or allowing people to do them much quicker.
There are huge possibilities for increasing labour productivity at an organisational level. The successful organisations will be those that can grasp these possibilities – and in many cases they will be incentivised to so so as it will improve their profitability or other outcomes.
Podcast
Articles
- Steeper UK productivity cut of more than £20bn makes tax rises more likely
The Guardian, Kalyeena Makortoff, Phillip Inman and Richard Partington (28/10/25)
- Reeves could face £20bn Budget hole as UK productivity downgraded
BBC News, Faisal Islam (27/10/25)
- To boost UK productivity, ordinary workers must bear more of the tax burden
Financial Times, Anatole Kaletsky (1/11/25)
- Neither China nor Japan – now it is the United States that adopts the brutal 9-9-6 model that redefines productivity and attrition
UnionRayo, Laura M. (1/11/25)
- ‘The money machine is misfiring’: City blames Brexit for UK’s £20bn productivity headache
The Guardian, Richard Partington (31/10/25)
- Organisations can achieve greater productivity and employee engagement with improved performance management, new research finds
WTW Press Release (29/10/25)
- Why does lower productivity mean tax rises are more likely?
BBC Verify, Ben Chu (4/11/25)
- Why is technology not making us more productive?
BBC News, Jonty Bloom (24/7/23)
Data
Questions
- In what different ways can productivity be measured? What is the most appropriate measure for assessing the effect of productivity on (a) GDP and (b) human welfare generally?
- Why has the UK had a lower level of labour productivity than France, Germany and the USA for many years? What can UK governments do to help close this gap?
- Find out how Japanese labour productivity has compared with that in the UK over the past 30 years and explain your findings.
- Research an organisation of your choice to find out ways in which labour productivity could be increased.
- Identify various ways in which AI can improve productivity. Will organisations be incentivised to adopt them?
- Has Brexit affected UK labour productivity and, if so, how and why?
According to Ofcom’s November 2024 Online Nation report (see report linked below), UK adults are falling out of love with dating apps. Use of the top three platforms in the UK (Tinder, Hinge, and Bumble) is declining, even though most users are juggling multiple apps at once. So, what’s going on? Economics may have some valuable insights to help explain the decline.
Too much choice
 First, dating platforms don’t function like typical commodity markets, where prices adjust until supply and demand balance. Instead, dating can be seen as what economists call a ‘matching market’, where success depends on mutual interest, not on a specific price. So even with thousands of potential matches, forming actual connections remains difficult, and more choice doesn’t necessarily translate into better outcomes.
In fact, more choice can backfire. The paradox of choice, a behavioural economics concept, suggests that too many options can lead to choice paralysis. Instead of feeling empowered by an abundance of potential partners, users can feel overwhelmed, unsure, and often less satisfied with whatever choice they end up making (if they make one at all).
So, while we often think of dating apps, like many other platforms, benefiting from positive network effects, where more users increase the platform’s value by offering more potential matches, this can also have negative effects. Swiping through endless profiles and repeating the same small talk, can turn dating into a chore rather than an exciting opportunity.
Adverse selection
 What makes this even harder is that users can’t easily distinguish between who’s genuinely looking for the same thing you are, and who’s just there to pass the time. This information asymmetry leads to the adverse selection problem – a concept famously explored by economist George Akerlof in his 1970 paper ‘The Market for Lemons’ (see link below). He showed how lack of information about product quality can cause high-quality sellers to exit, resulting in market failure where the market becomes dominated by low-quality goods (i.e. ‘lemons’).
A similar dynamic can play out on dating apps. If users believe most profiles are unserious or not genuine, they become less willing to engage, or even stay on the platform. Meanwhile, the most genuine users may give up altogether, worsening the quality of the pool and discouraging others.
In economics, there are some well-known ways in which the problem of adverse selection could be overcome. One such possibility is through signalling, where the more informed person tries to reveal important information to the uninformed person. Indeed, platforms have experimented with signalling mechanisms, like verification tools for example. Paid subscriptions have also been implemented, which could help to some extent (assuming that those who are willing to pay are those who are genuine and serious about finding a match). But these solutions only go so far, and with fewer users paying to signal intent, the problem persists.
Lack of innovation
 This ties into the wider revenue model of dating apps. Unlike many apps that rely on revenue from advertising on one side of the market to offer the app free to consumers on the other side, dating platforms often rely more on revenue through monthly subscriptions and paid upgrades. But with fewer users willing to pay, these platforms may be under pressure. This financial pressure may also affect their ability to innovate or improve the service.
In fact, in the dating app world, there is another reason why platforms may not be innovating as much as they should, aside from simply trying to convince their users to pay for a better service. While it seems like there’s endless choice in the dating app world, much of the market is controlled by a single company, InterActiveCorp (IAC), which owns Tinder, Hinge, Match.com and more. With limited competition, there’s less incentive to compete on quality.
Worse still, dating apps face a unique business problem: if their service works too well, users leave and delete the app. So, there may be a built-in tension between helping users succeed and keeping them swiping.
The outlook for dating apps
So, is the decline in dating app use just temporary, or the start of something bigger? Time will tell. However, from an economics perspective, there is a noticeable shift in demand towards substitutes, such as organised in-person social events and activities, which encourages more and more of these opportunities to emerge. This shift may reflect changing preferences and the costs (in terms of time and emotional energy) that users are willing to invest in online dating.
At the same time, AI already plays a key role in dating apps, and new possibilities seem to be emerging. For example, we could see a bigger rollout of AI-driven chatbots that facilitate conversations or even interact on behalf of users. This could make it easier to connect with potential matches and might help in addressing some of the other issues discussed above.
Articles
Video
Report
Questions
- How might ‘signalling’ and ‘screening’ be used to create new features or services that could help overcome the adverse selection problem in this market?
- Can you think of any other ways in which the adverse selection problem could be overcome in this context?
- Draw a diagram to illustrate the two-sided nature of the dating app market, making clear where there may be positive or negative network effects.
- How else might dating app platforms be making revenue that allows them to offer the app to users at no charge?
- Is the dating app market competitive? You might consider factors such as the availability of substitutes, barriers to entry and innovation.
