The grocery retail market in New Zealand is worth billions of dollars each year and is one of the most concentrated supermarket sectors in the world. The industry is dominated by two large groups: Foodstuffs and Woolworths New Zealand. Together, these firms account for around 80–90 per cent of grocery sales, with Foodstuffs operating brands such as Pak’nSave, New World and Four Square, while Woolworths operates the Woolworths supermarket chain.
The market displays many of the characteristics of an oligopoly. The two dominant firms compete through store location, loyalty schemes, advertising and product range, and to some extent through pricing. At the same time, they benefit from substantial economies of scale, extensive distribution networks and strong relationships with suppliers. These factors mean that there are significant barriers to entry in the market and this can prevent new firms from entering the market and surviving.
Competition concerns
Concern about competition in the sector has led to investigations by New Zealand’s Commerce Commission. The Commission concluded that although there was competition in the market, it was less than optimal and both firms were earning higher profits than they would have been able to earn had they been in operating in a more competitive market.
 It identified various barriers to entry that limited competition, including access to suitable retail sites, ownership of distribution networks and the difficulty of establishing large-scale supply chains in a country with a relatively small population.
Despite the market being dominated by these two big firms, there are also many smaller retailers operating within the market, including independent grocery stores, convenience stores and specialist food retailers. However, they lack the scale that is needed to challenge the dominance of Foodstuffs and Woolworths at a national level.
Potential international entrants, such as Aldi and Lidl, have often been suggested as possible competitors, but the costs of establishing a nationwide network of stores and distribution facilities in New Zealand are significant. There have been examples of large and dominant supermarkets in one country attempting to enter the market in other countries but failing to survive or deciding to exit the market early. For example, Tesco entered the Chinese market in 2004 but, despite its efforts, exited the market in 2020.
Response by the New Zealand government
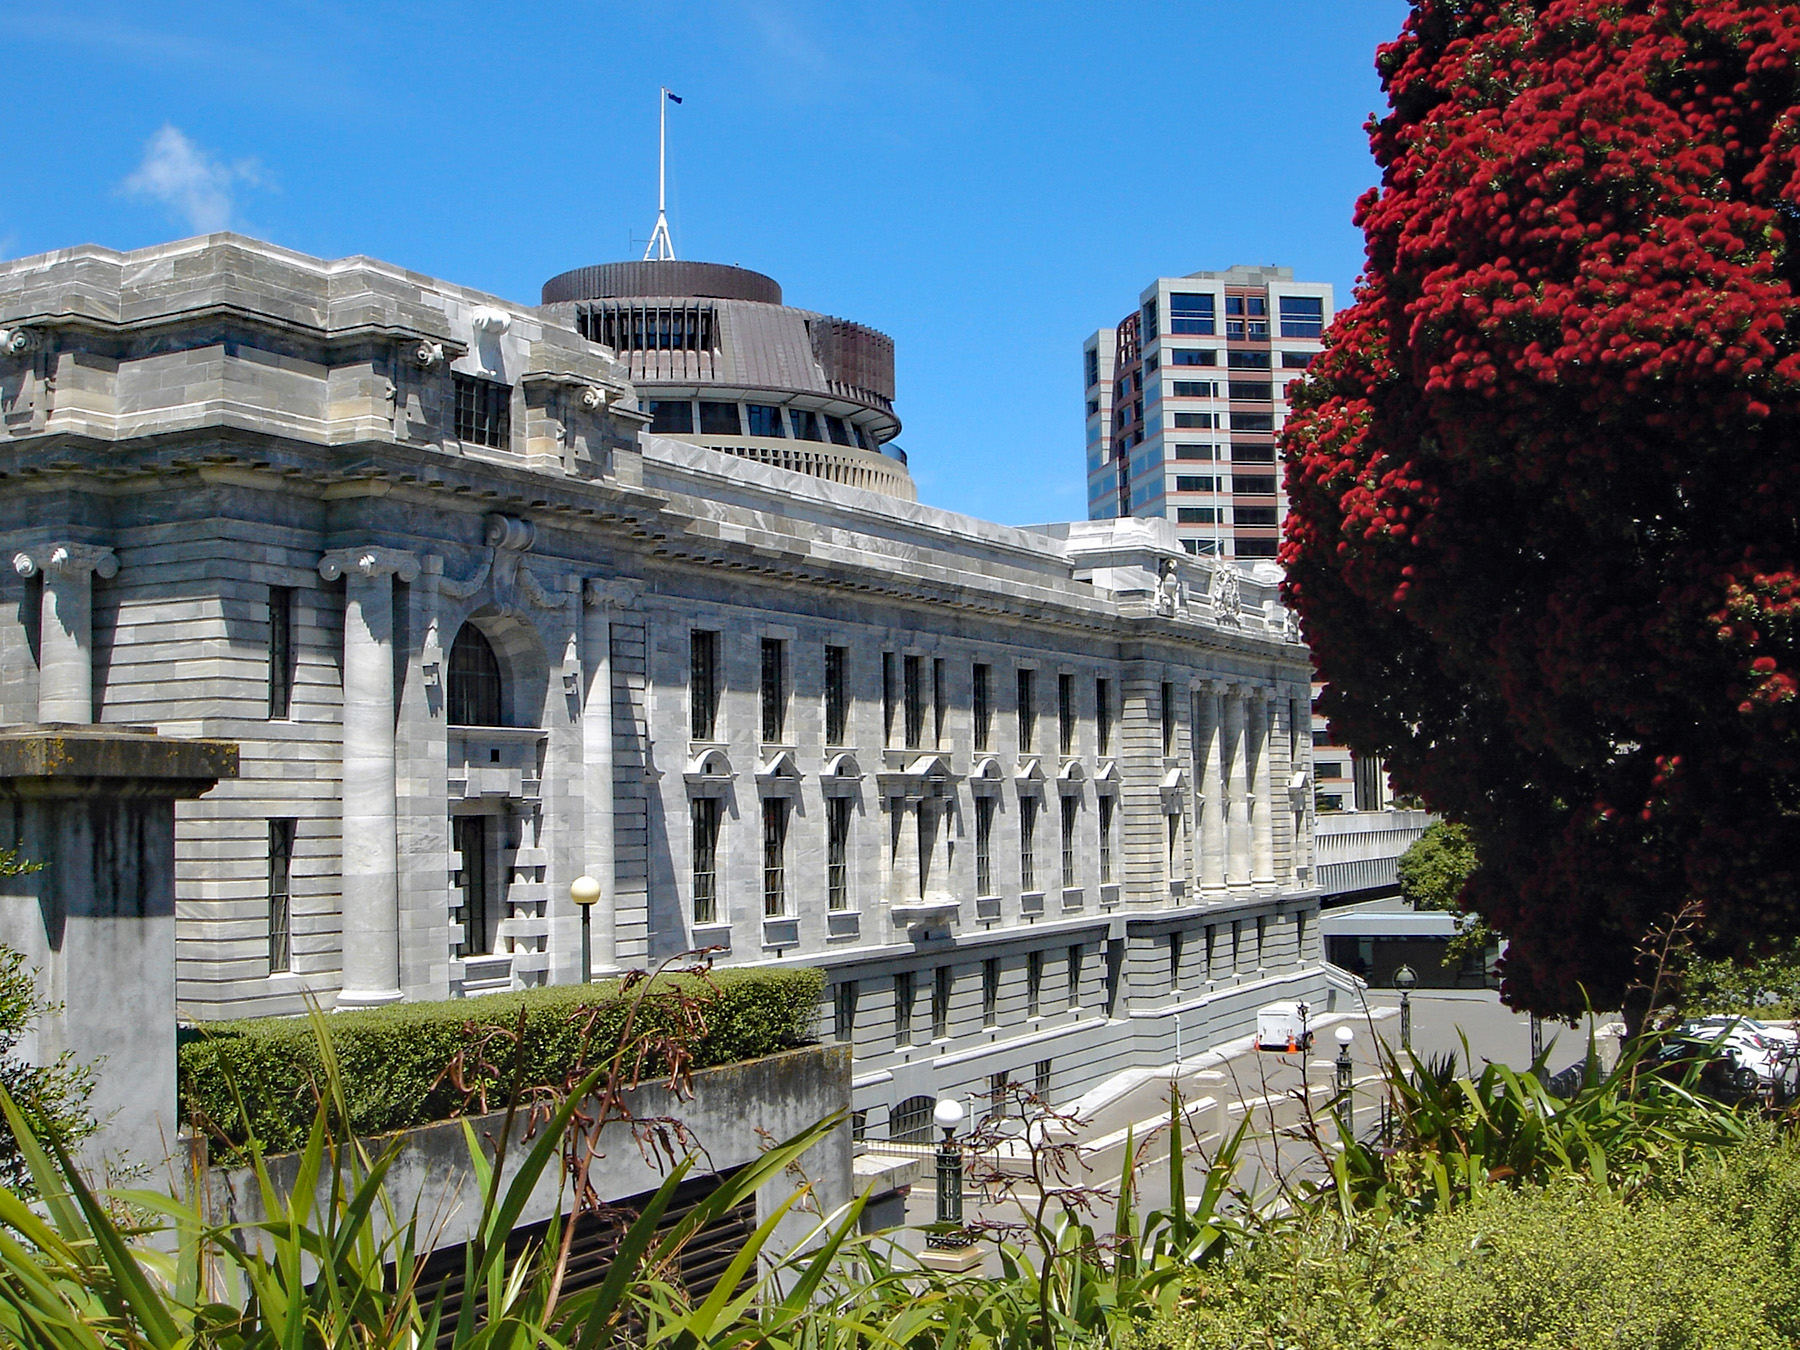 In response to concerns about competition, the New Zealand government has introduced a series of measures designed to make market entry easier. These include restrictions on anti-competitive land covenants, the introduction of a Grocery Commissioner and changes intended to improve access to wholesale grocery supply.
But, despite these measures, recent reports suggest that the overall market structure has changed little, with the two major firms continuing to dominate grocery retailing.
The public interest
Supporters of the current market structure argue that large supermarket chains deliver lower costs through economies of scale and provide consumers with extensive product choice.
Critics counter that limited competition leads to higher prices, reduced innovation and weaker bargaining power for suppliers.
The debate illustrates the difficulties faced by policymakers when attempting to balance efficiency against the promotion of competition.
Whether greater competition will emerge in the future remains uncertain. Much will depend on whether existing reforms can encourage new entrants or whether the structural advantages enjoyed by Foodstuffs and Woolworths continue to deter potential rivals.
Articles
- ‘Substantive, potentially systemic’ supermarket concerns raised by Commerce Commission
- Supermarkets aren’t the problem. This issue is a far bigger deal
- This may be as good as it gets: NZ and Australia face a complicated puzzle when it comes to supermarket prices
- Every party has pitched its own supermarket fix. What if we combined the best ideas?
- NZ regulator eyes ‘problematic’ supermarket supplier fees
- Australia vs NZ: Supermarket competition compared
- Grocery Commissioner puts supermarkets on notice
- High margins, double the normal returns – does NZ’s supermarket duopoly drive prices up?
- Everyone wants to break up the supermarkets. How would it actually work?
RNZ News, Susan Edmunds (7/7/26)
Money Stuff, Rupert Carlyon (23/9/26)
The Conversation, Richard Meade (23/4/25)
The Conversation, Jonathan Baker (21/9/26)
Inside FMCG, Sean Cao (7/7/26)
Consumer NZ, Vanessa Pratley (27/3/25)
RNZ News, Susan Edmunds (18/3/26)
The Press, Susan Edmunds (22/9/26)
The Spinoff, Joel MacManus (22/9/26)
Questions
- What are the characteristics of the New Zealand supermarket industry that create barriers to entry for new firms?
- To what extent is the New Zealand grocery market consistent with the characteristics of an oligopoly?
- Evaluate the likely effectiveness of government measures designed to increase competition in the supermarket sector.
- Australia too has two main supermarket chains: Coles and Woolworths. However, Aldi has entered the Australian market and in some parts of the country had provided significant competition to the two major chians. Why may Aldi have more difficulty in entering the New Zealnd market
- Investigate the grocery retail market in another country (not the UK). Who are the major competitors and what is their market share? What barriers to entry exist? Has the competition authority expressed concerns about the market and if so, what are they?