 An investigation by the International Consortium of Investigative Journalists has revealed how more than 1000 businesses from 340 major companies from around the world have used Luxembourg as a base for avoiding huge amounts of tax. Many of the companies are household names, such as Ikea, FedEx, Apple, Pepsi, Coca Cola, Dyson, Amazon, Fiat, Google, Accenture, Burberry, Procter & Gamble, Heinz, JP Morgan, Caterpillar, Deutsche Bank and Starbucks. Through complicated systems of ‘advanced tax agreements’ (ATAs), negotiated with the Luxembourg authorities via accountants PricewaterhouseCoopers (PwC), companies have used various methods of avoiding tax.
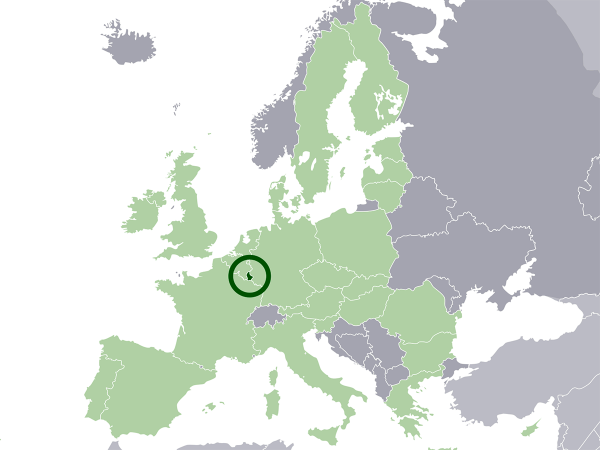
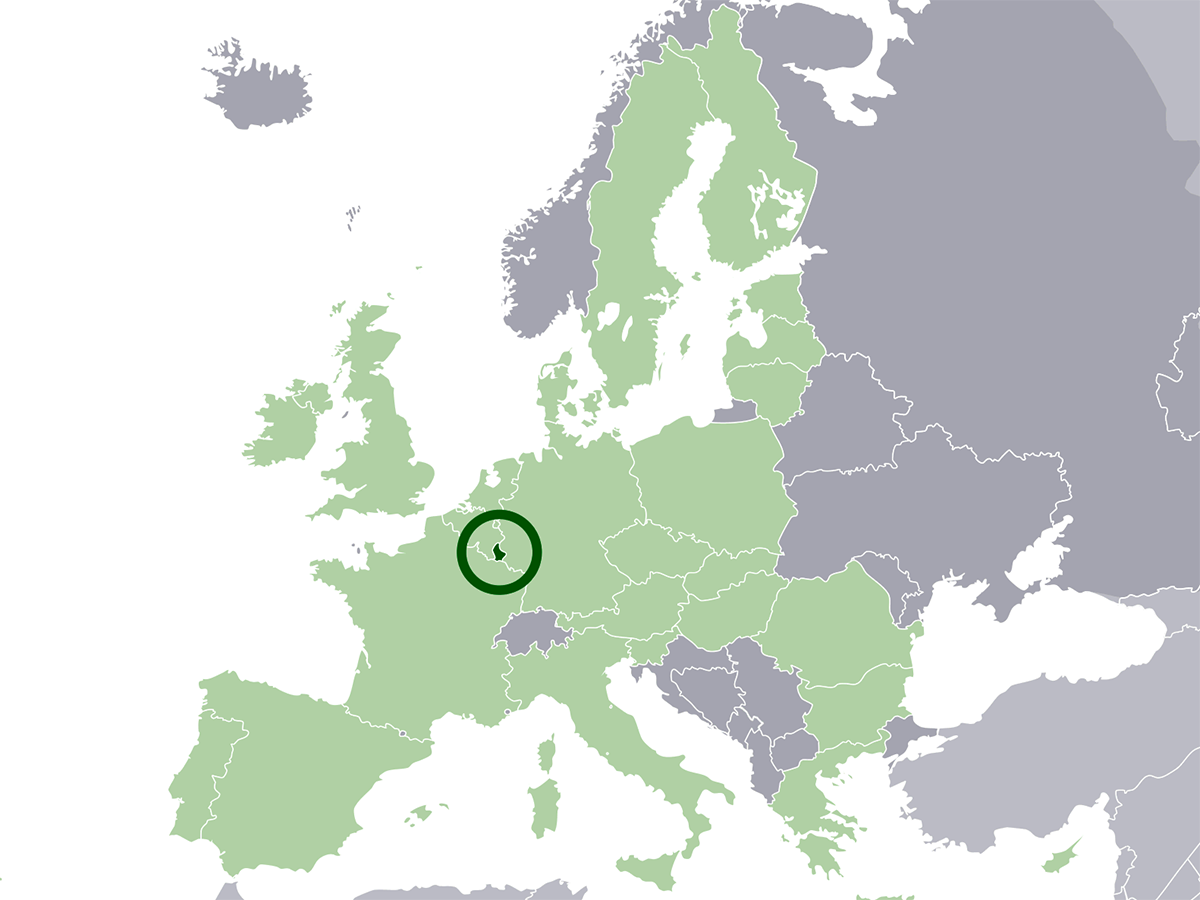
Although such measures are legal, they have denied other countries vast amounts of tax revenues on sales generated in their own countries. Instead, the much reduced tax bills have been paid to Luxembourg. The result is that this tiny country, with a population of just 550,000, has, according to the IMF, the highest (nominal) GDP per head in the world (estimated to be $116,752 in 2014).
 So what methods do Luxembourg and these multinational companies use to reduce the companies’ tax bills? There are three main methods. All involve having a subsidiary based in Luxembourg: often little more than a small office with one employee, a telephone and a bank account. All involve varieties of transfer pricing: setting prices that the company charges itself in transactions between a subsidiary in Luxembourg and divisions in other countrries.
The first method is the use of internal loans. Companies lend money to themselves, say in the UK, from Luxembourg at high interest rates. The loan interest can be offset against profit in the UK, reducing tax liability to the UK tax authorities. But the interest earned by the Luxembourg subsidiary incurs very low taxes. Profits are thus effectively transferred from the UK to Luxembourg and a much lower tax bill is incurred.
The second involves royalty payments for the use of the company’s brands. These are owned by the Luxembourg subsidiary and the overseas divisions pay the Luxembourg subsidiary large sums for using the logos, designs and brand names. Thus, again, profits are transferred to Luxembourg, where there is a generous tax exemption.
The third involves generous allowances in Luxembourg for losses in the value of investments, even without the company having first to sell the investments. These losses can be offset against future profits, again reducing tax liability. By transferring losses made elsewhere to Luxembourg, again usually by some form of transfer pricing, these can be used to reduce the already small tax bill in Luxembourg even further.
 Tax loopholes offered by tax havens, such as Luxembourg, the Cayman Islands and the Channel Islands, are denying exchequers around the world vast sums. Not surprisingly, countries, especially those with large deficits, are concerned to address the issue of tax avoidance by multinationals. This is one item on the agenda of the G20 meeting in Brisbane from the 12 to 16 November 2014.
The problem, however, is that, with countries seeking to attract multinational investment and to gain tax revenues from them, there is an incentive to reduce corporate tax rates. Getting any binding agreement on tax harmonisation, and creating an essentially global single market, is likely, therefore, to prove virtually impossible.
Webcasts and videos
 Luxembourg Leaks: Tricks of the Trade ICIJ in partnership with the Pulitzer Center (5/11/14)
Luxembourg ‘abetted’ companies in avoiding taxes France 24, Siobhán Silke (6/11/14)
Tax deals with Luxembourg save companies billions, says report Deutsche Welle, Dagmar Zindel (6/11/14)
Luxembourg: the tax haven and the $870m loan company above a stamp shop The Guardian, John Domokos, Rupert Neate and Simon Bowers (5/11/14)
Luxembourg leaks: nation under spotlight over tax avoidance claims euronews (6/11/14)
Northern and Shell used west Dublin address to cut Luxembourg tax bill on €1bn The Irish Times, Colm Keena (6/11/14)
The ATO’s global tax avoidance investigation ABC News, Phillip Lasker (9/11/14)
Pepsi, IKEA Secret Luxembourg Tax Deals Exposed TheLipTV, Elliot Hill (9/11/14)
Articles
Leaked Docs Expose More Than 340 Companies’ Tax Schemes In Luxembourg Huffington Post, Leslie Wayne, Kelly Carr, Marina Walker Guevara, Mar Cabra and Michael Hudson (5/11/14)
Luxembourg tax files: how tiny state rubber-stamped tax avoidance on an industrial scale The Guardian, Simon Bowers (5/11/14)
Fact and fiction blur in tales of tax avoidance The Guardian (9/11/14)
companies engaged in tax avoidance The Guardian, Michael Safi (6/11/14)
The Guardian view on tax avoidance: Europe must take Luxembourg to task The Guardian, Editorial (6/11/14)
G20 leaders in the mood to act on tax avoidance after Luxembourg leaks Sydney Morning Herald, Tom Allard (6/11/14)
Scale of Luxembourg tax avoidance revealed economia, Oliver Griffin (6/11/14)
EU to press Luxembourg over tax breaks amid fresh allegations BBC News (6/11/14)
Luxembourg leaks: G20 alone can’t stamp out tax avoidance The Conversation, Charles Sampford (7/11/14)
‘Lux leaks’ scandal shows why tax avoidance is a bad idea European Voice, Paige Morrow (8/11/14)
EU to Probe Luxembourg’s ‘Sweetheart Tax Deal’ with Amazon International Business Times, Jerin Mathew (7/10/14)
Investigative Project
Luxembourg Leaks: Global Companies’ Secrets Exposed The International Consortium of Investigative Journalists (5/11/14)
Questions
- Distinguish between tax avoidance and tax evasion. Which of the two is being practised by companies in their arrangements with Luxembourg?
- Explain what is meant by transfer pricing.
- Do a search of companies to find out what parts of their operations as based in Luxembourg.
- In what sense can the setting of corporate taxes be seen as a prisoner’s dilemma game between countries?
- Discuss the merits of changing corporate taxes so that they are based on revenues earned in a country rather than on profits.
- What type of agreement on tax havens is likely to be achieved by the international community?
- Is it desirable for companies to be able to offset losses against future profits?
 In an earlier post, Elizabeth looked at oligopolistic competition between supermarkets. Although supermarkets have been accused of tacit price collusion on many occasions in the past, price competition has been growing. And recent developments show that it is likely to get a lot fiercer as the ‘big four’ try to take on the ‘deep discounters’, Aldi and Lidl.
Part of the reason for the growth in price competition has been a change in shopping behaviour. Rather than doing one big shop per week in Tesco, Sainsbury’s, Asda or Morrisons, many consumers are doing smaller shops as they seek to get more for their money. A pattern is emerging for many consumers who are getting their essentials in Aldi or Lidl, their ‘special’ items in more upmarket shops, such as Waitrose, Marks & Spencer or small high street shops (such as bakers and ethnic food shops) and getting much fewer products from the big four. Other consumers, on limited incomes, who have seen their real incomes fall as prices have risen faster than wages, are doing virtually all their shopping in the deep discounters. As the Guardian article below states:
A steely focus on price and simplicity, against a backdrop of falling living standards that has sharpened customers’ eye for a bargain, has seen the discounter grab market share from competitors and transform what we expect from our weekly shop.
The result is that the big four are seeing their market share falling, as the chart shows. 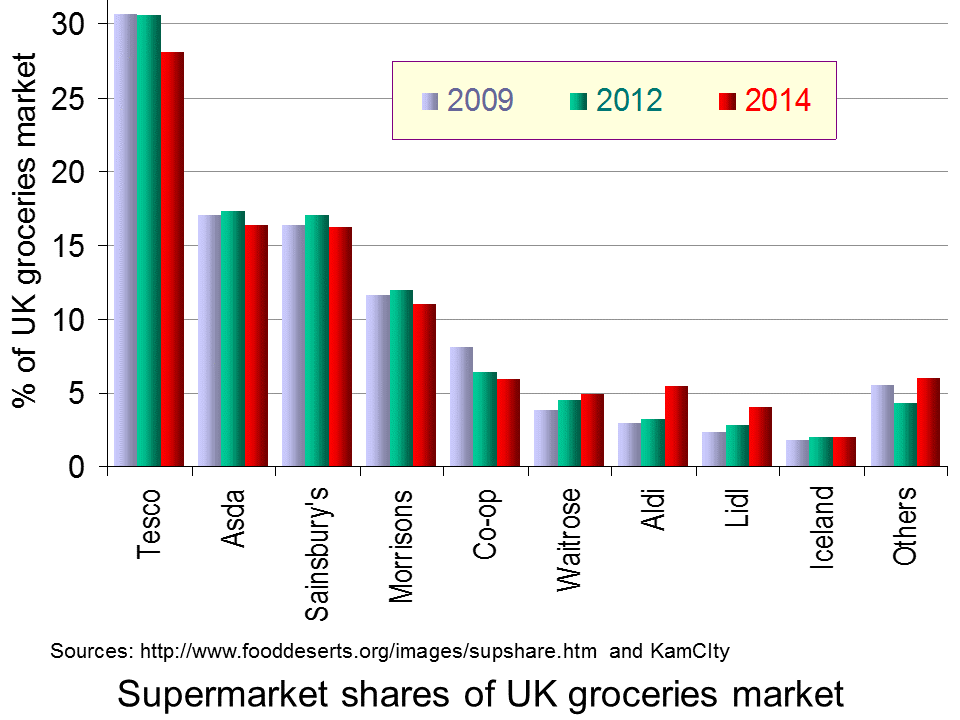 (Click here for a PowerPoint of the chart.) In the past year, Tesco’s market share has fallen from 29.9% to 28.1%, Asda’s from 17.8% to 16.3%, Sainsbury’s from 16.9% to 16.2% and Morrisons’ from 11.7% to 11.0%. By contrast, Aldi’s has risen from 3.9% to 5.4% and Lidl’s from 3.1% to 4.0%, while Waitrose’s has also risen, from 4.7% to 4.9%. And it’s not just market share that has been falling for the big four. Profits have also fallen, as have share prices. Sales revenues in the four weeks to 13 September are down 1.6% on the same period a year ago; sales volumes are down 1.9%.
But can the big four take on the discounters at their own game? Morrison’s has just announced a form of price match scheme called ‘Match & More’. If a shopper finds that a comparable grocery shop is cheaper in not only Tesco, Sainsbury’s or Asda, but also in Aldi or Lidl, then ‘Match & More users will automatically get the difference back in points on their card. Shoppers also will be able to collect extra points on hundreds of featured products and fuel’. When the difference has risen to a total £5 (5000 points), the shopper will get a £5 voucher at the till. The idea is to encourage customers to stay loyal to Morrisons.
 But what if Tesco, Asda and Sainsbury’s do the same? What will be the impact on their prices and profits. Will there be a race to the bottom in prices, or will they be able to keep prices higher than the deep discounters, hoping that many customers will not cash in their vouchers?
But if effectively the big four felt forced to cut their prices to match Aldi and Lidl, could they afford to do so? This depends on their comparative average costs. At first sight, it might be thought that the big four could succeed in profitably matching the discounters, thereby clawing back market share. After all, they are much bigger and it might be thought that they would benefit from greater economies of scale and hence lower costs.
But it is not as simple as this. The discounters have lower costs than the big four. Their shops are typically in areas where rents or land prices are lower; their shops are smaller; they carry many fewer lines and thus gain economies of scale on each line; they have a much higher proportion of own-brand products; products are displayed in the boxes they come in, thus saving on the staff costs of unpacking them and placing them on shelves; they buy what is cheapest and thus do not always display the same brands.
So is Morrison’s a wise strategy? Will other supermarkets be forced to follow? Is there a prisoners’ dilemma here and, if so, is there any form of collusion in which the big four can engage which is not illegal? Can the big four differentiate themselves from the discounters and the up-market supermarkets in ways that will attract back customers?
It is worrying times for the big four.
Articles
- Heavy Discounters Up Pressure On The UK’s Big Four Supermarkets
Alliance News, Rowena Harris-Doughty (3/6/14)
- Tesco loses more market share as supermarket sector slows to record low
CITY A.M., Catherine Neilan (23/9/14)
- Record low for grocery market growth as inflation disappears
Kantar World Panel, Fraser McKevitt (23/9/14)
- How Aldi’s price plan shook up Tesco, Morrison’s, Asda and Sainsbury’s
The Guardian, Sarah Butler (29/9/14)
- Sainsbury’s shares drop 7% on falling sales report
BBC News (1/10/14)
- Sainsbury results: the reaction
Food Manufacture, Mike Stones (3/10/14)
- Morrisons Becomes First Of Big Four Grocers To Price Match Aldi, Lidl
Alliance News, Rowena Harris-Doughty (2/10/14)
- UK: Morrisons Takes On Discounters With Price Match Card
KamCity (3/10/14)
- Morrisons to match the prices of Aldi and Lidl
The Telegraph, Graham Ruddick (2/10/14)
- Three reasons why Morrisons price-matching Aldi and Lidl is not a ‘gamechanger’
The Telegraph, Graham Ruddick (2/10/14)
Questions
- Would it be possible for the big four to price match the deep discounters?
- What is meant by the prisoners’ dilemma? In what ways are the big four in a prisoners’ dilemma situation?
- Assume that you had to advise Tesco on it strategy? What advise would you give it and why?
- Assume that two firms, M and A, are playing the following ‘game’: firm M pledges to match firm A’s prices; and firm A pledges to sell at 2% below M’s price. What will be the outcome of this game?
- Is Morrisons wise to adopt its ‘Match & More’ strategy?
- Why is it difficult for Morrisons to make a like-for-like comparison with Aldi and Lidl in its ‘Match & More’ strategy?
- Why may Aldi and Lidl benefit from Morrisons’ strategy?
 In oligopoly markets, because there are a small number of firms, each firm is affected by its rivals’ decisions. This interdependence results in a tension between cooperation and competition. On the one hand, firms collectively benefit from cooperating and keeping prices high.
On the other hand, an individual firm then has an incentive to undercut its rivals to steal a larger share of the market. This incentive to undercut can potentially result in price wars between firms. This is exactly what has recently occurred between pizza sellers on the Avenue of Americas in Midtown New York. Here, until recently the 6th Ave. Pizza company was selling pizza for $1.50 per slice. However, the entry of two competitors nearby sparked an intense and bitter price war.
First, an outlet called Joey Pepperoni’s Pizza opened nearby and charged $1 per slice. This price was then matched by the 6th Avenue Pizza company. Then, the 2 Bros. pizza chain opened an outlet almost next door to the 6th Avenue Pizza company. Initially, they also charged $1 per slice.
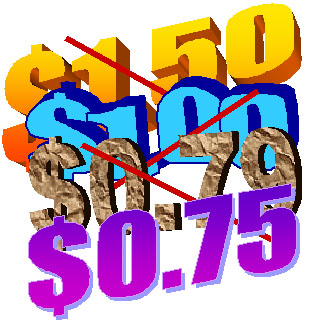 However, this did not last for too long. First 6th Avenue cut its price to 79 cents and then 2 Bros. responded by cutting its price to 75 cents, which 6th Avenue quickly matched.
Which company started this price war has been subject to some debate. The owners of the 6th Avenue Pizza company were angry, alleging that 2 Bros. was trying to force them out of business. However, the owners of 2 Bros. claimed that they were simply responding to the 6th Avenue Pizza company’s decision to start charging 79 cents per slice and they even have evidence from their security cameras confirming this! When asked why they cut their price the owners of the 6th Avenue company said that:
He was taking away our customers. How were we going to pay our rent?
So what will happen next in this market? One of the owners of the 2 Bros. company has said that they will go back to $1 per slice if the 6th Avenue Pizza company does the same, as they can’t make any profit at the current price. However, the tension between cooperation and competition suggests this may be difficult to sustain.
In the meantime, both are quoted suggesting that they may be tempted to reduce prices even further. 6th Avenue Pizza company stated:
We may go to 50 cents. I want to hit him. I want to beat him.
2 Bros. said:
We might go to free pizza soon.
Of course, while the price war continues, the clear winners are the consumers. In the article one is quoted as saying:
I think it’s beautiful. We need 75-cent hamburgers next.
Articles
Questions
- Why is it difficult for firms to maintain high prices in oligopolistic markets?
- What are the key features of competition in the pizza market?
- Is this the type of market where you would expect price wars to be likely?
- How might firms in this market try to differentiate their product?
- Do you think prices will ever return to $1.50 per slice in this market? Explain.
 World leaders have been meeting in Rio de Janeiro at a United Nations Conference on Sustainable Development. The conference, dubbed ‘Rio+20’, refers back to the first UN Conference on Environment and Development (UNCED) held in Rio 20 years ago in June 1992.
The 1992 conference adopted an Agenda 21. It was “comprehensive plan of action to be taken globally, nationally and locally by organizations of the United Nations System, Governments, and Major Groups in every area in which human impacts on the environment.”
The 2012 conference has looked at progress, or lack of it, on sustainability and what needs to be done. It has focused on two major themes: “how to build a green economy to achieve sustainable development and lift people out of poverty, including support for developing countries that will allow them to find a green path for development; and how to improve international coordination for sustainable development.” Issues examined have included decent jobs, energy, sustainable cities, food security and sustainable agriculture, water, oceans and disaster readiness.
But just what is meant by sustainable development? The conference defines sustainable development as that which meets the needs of the present without compromising the ability of future generations to meet their own needs. “Seen as the guiding principle for long-term global development, sustainable development consists of three pillars: economic development, social development and environmental protection.”
The articles below look at prospects for national and global sustainability. They also look at a new measure of national wealth, the Inclusive Wealth Index (IWI). This index has been developed under the auspices of the International Human Dimensions Programme on Global Environmental Change (IHDP) and published in its Inclusive Wealth Report 2012 (see report links below).
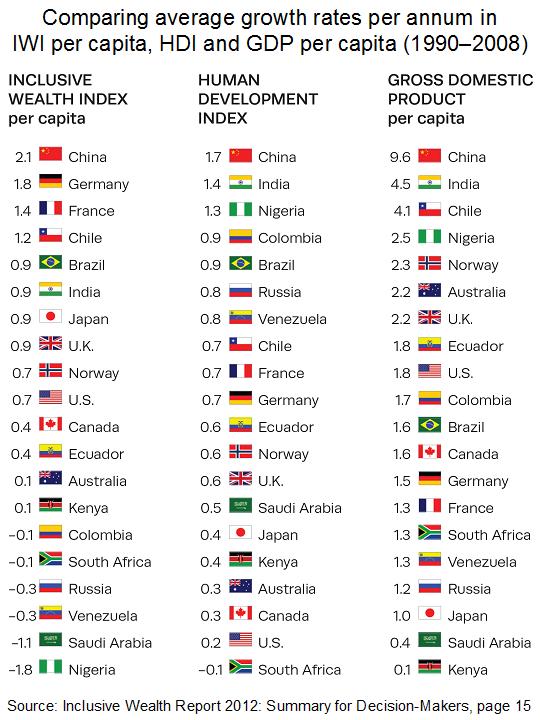 The IWR 2012 was developed on the notion that current economic production indicators such as gross domestic product (GDP) and the Human Development Index (HDI) are insufficient, as they fail to reflect the state of natural resources or ecological conditions, and focus exclusively on the short term, without indicating whether national policies are sustainable.
The IWR 2012 features an index that measures the wealth of nations by looking into a country’s capital assets, including manufactured, human and natural capital, and its corresponding values: the Inclusive Wealth Index (IWI). Results show changes in inclusive wealth from 1990 to 2008, and include a long-term comparison to GDP for an initial group of 20 countries worldwide, which represent 72% of the world GDP and 56% of the global population. (Click on chart for a larger version.)
So will growth in IWI per capita be a better measure of sustainable development than growth in GDP per capita? The articles also consider this issue.
Articles: summit
Rio+20 deal weakens on energy and water pledges BBC News, Richard Black (17/6/12)
Rio+20: Progress on Earth issues ‘too slow’ – UN chief BBC News, Richard Black (20/6/12)
Rio+20 Earth Summit Q&A The Telegraph, Louise Gray (16/5/12)
Rio+20 Earth Summit: campaigners decry final document Guardian, Jonathan Watts and Liz Ford (23/6/12)
A catastrophe if global warming falls off the international agenda Observer, Will Hutton (24/6/12)
Analysis: Rio +20 – Epic Fail The Bureau of Investigative Journalism Brendan Montague (22/6/12)
Articles: IWI
Accounting for natural wealth gains world traction Atlanta Business NewsKaty Daigle (17/6/12) (see alternatively)
New index shows lower growth for major economies Reuters, Nina Chestney (17/6/12)
A New Balance Sheet for Nations: UNU-IHDP and UNEP Launch Sustainability Index that Looks Beyond GDP EcoSeed (20/6/12)
World’s leading economies lag behind in natural capital Firstpost (18/6/12)
Beyond GDP: Experts preview ‘Inclusive Wealth’ index at Planet under Pressure conference EurekAlert, Terry Collins (28/3/12)
New sustainability index created that looks at more than gross domestic product bits of science (17/6/12)
For Sustainability, Go Beyond Gross Domestic Product Scientific AmericanDavid Biello (17/6/12)
Report
Inclusive Wealth Report 2012: Overview IHDP
Inclusive Wealth Report 2012: Summary for Decision-makers IHDP
Inclusive Wealth Report 2012: full report IHDP
Questions
- What progress has been made towards sustainable development over the past 20 years?
- What are the limitations of conferences such as Rio+20 in trying to achieve global action?
- With the current challenges faced by the eurozone and the global economy more generally, is this a good time to be discussing long-term issues of sustainable development?
- Explain how IWI is derived and measured?
- Looking at the chart above, explain the very different positions of countries in the three columns.
- What are the strengths and weaknesses of using growth in IWI compared with using growth in GDP as measures of (a) economic development; (b) economic wellbeing?
 Paul Volcker was Chair of the US Federal Reserve from 1979 to 1987. He was also Chair of the Economic Recovery Advisory Board under President Barack Obama from February 2009 to January 2011. In the webcast and articles below, he reflects on the current state of the world financial system – from regulation, to the euro crisis, to world imbalances, to the system of floating exchange rates.
He argues that global financial systems are vulnerable to breakdowns. What is needed is reform to the system, and for that there needs to be consensus by politicians, regulators and central banks.
But, in the absence of international consensus on some key points, reform will be greatly weakened, if not aborted. The freedom of money, financial markets and people to move – and thus to escape regulation and taxation – might be an acceptable, even constructive, brake on excessive official intervention, but not if a deregulatory race to the bottom prevents adoption of needed ethical and prudential standards.
Perhaps most important is a coherent, consistent approach to dealing with the imminent failure of “systemically important” institutions. Taxpayers and governments alike are tired of bailing out creditors for fear of the destructive contagious effects of failure – even as bailouts encourage excessive risk-taking.
According to Volcker, countries must be prepared to surrender some sovereignty. Policies must be co-ordinated internationally and there must be stronger regulation by international bodies, such as the IMF and stronger concerted action by global organisations, such as the G20.
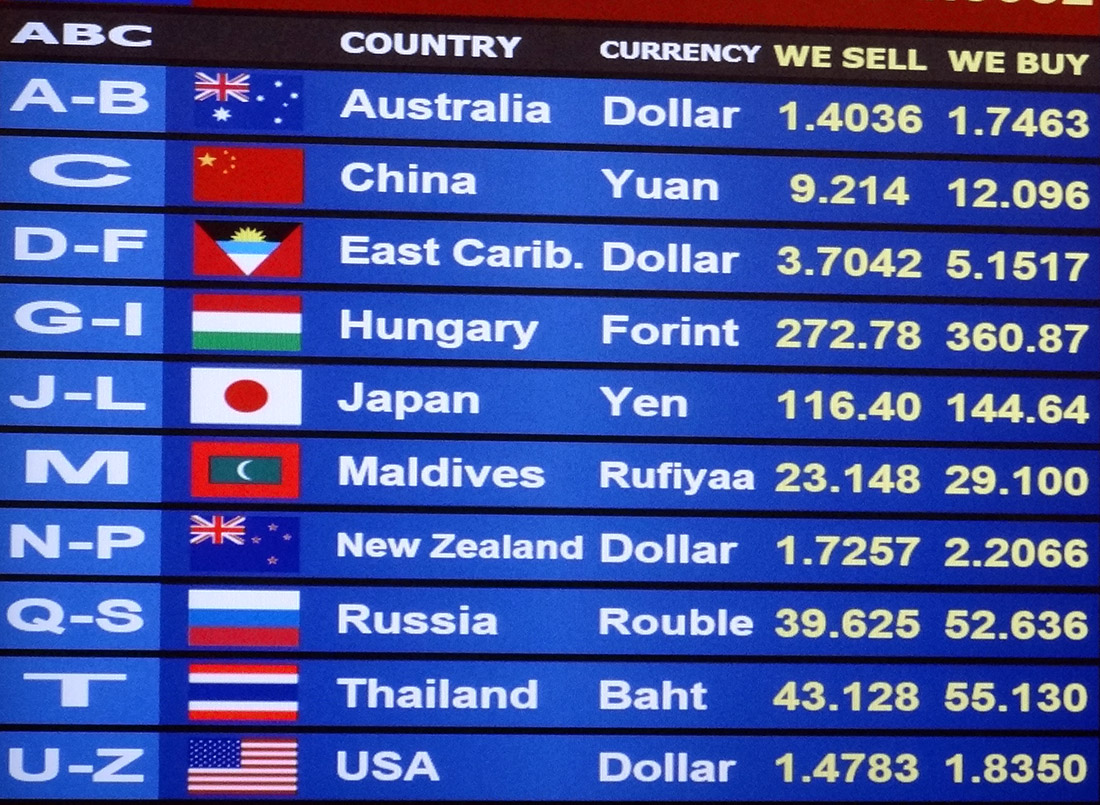 Left to their own devices, in an era of floating exchange rates, countries may pursue policies that exacerbate global imbalances.
Not so long ago, we were comforted by theorising that floating exchange rates would mediate international adjustments in a timely and orderly way. But, in the real world, many countries, particularly but not limited to small, open economies, simply find it impractical or undesirable to permit their currency to float.
We are left with the certainty, however awkward, that active participation in an open world economy requires some surrender of economic sovereignty. Or, to put the point more positively, it requires a willingness to co-ordinate policies more effectively.
Webcast
Volcker Urges Global Monetary System Overhaul BloombergBusinessweek (31/5/12)
Articles
Is global financial reform possible? Guardian, Paul Volcker (6/6/12)
Volcker Urges Global Financial System Overhaul After Crisis BloombergBusinessweek, Robyn Meredith and Shamim Adam (31/5/12)
Questions
- What reforms, according to Volcker, need to be implemented in order for the euro to function effectively without crises?
- What can the USA do to ease the euro crisis?
- What are Volcker’s views on the regulation of the US banking system?
- How are incentive structures in banks related to speculative activities?
- Should banks be allowed to fail?
- What financial imbalances exist between countries?
- What international monetary reforms are required?
- What light can game theory shed on the difficulty of achieving global policy co-ordination?
- Is an international system of floating exchange rates appropriate given the size of international financial flows?
 An investigation by the International Consortium of Investigative Journalists has revealed how more than 1000 businesses from 340 major companies from around the world have used Luxembourg as a base for avoiding huge amounts of tax. Many of the companies are household names, such as Ikea, FedEx, Apple, Pepsi, Coca Cola, Dyson, Amazon, Fiat, Google, Accenture, Burberry, Procter & Gamble, Heinz, JP Morgan, Caterpillar, Deutsche Bank and Starbucks. Through complicated systems of ‘advanced tax agreements’ (ATAs), negotiated with the Luxembourg authorities via accountants PricewaterhouseCoopers (PwC), companies have used various methods of avoiding tax.
 So what methods do Luxembourg and these multinational companies use to reduce the companies’ tax bills? There are three main methods. All involve having a subsidiary based in Luxembourg: often little more than a small office with one employee, a telephone and a bank account. All involve varieties of transfer pricing: setting prices that the company charges itself in transactions between a subsidiary in Luxembourg and divisions in other countrries.
 Tax loopholes offered by tax havens, such as Luxembourg, the Cayman Islands and the Channel Islands, are denying exchequers around the world vast sums. Not surprisingly, countries, especially those with large deficits, are concerned to address the issue of tax avoidance by multinationals. This is one item on the agenda of the G20 meeting in Brisbane from the 12 to 16 November 2014.