Inflation has been rising around the world. The main reason has been the supply shock of rising oil, fertiliser and commodity prices caused by the Iran war and the disruption to global supply chains from conflicts in the Middle East and Russia (see the blog, Why have diesel prices risen more than petrol prices?). Central banks, including the US Federal Reserve Bank, the European Central Bank and the Bank of Japan, have responded to this cost-push inflationary shock by raising interest rates. The Bank of England is likely to raise Bank rate at its next meeting on 5 November 2026.
Similar supply shocks have been experienced in recent years (see the May 2026 blog, Supply shocks – long-term gain from the short-term pain?).
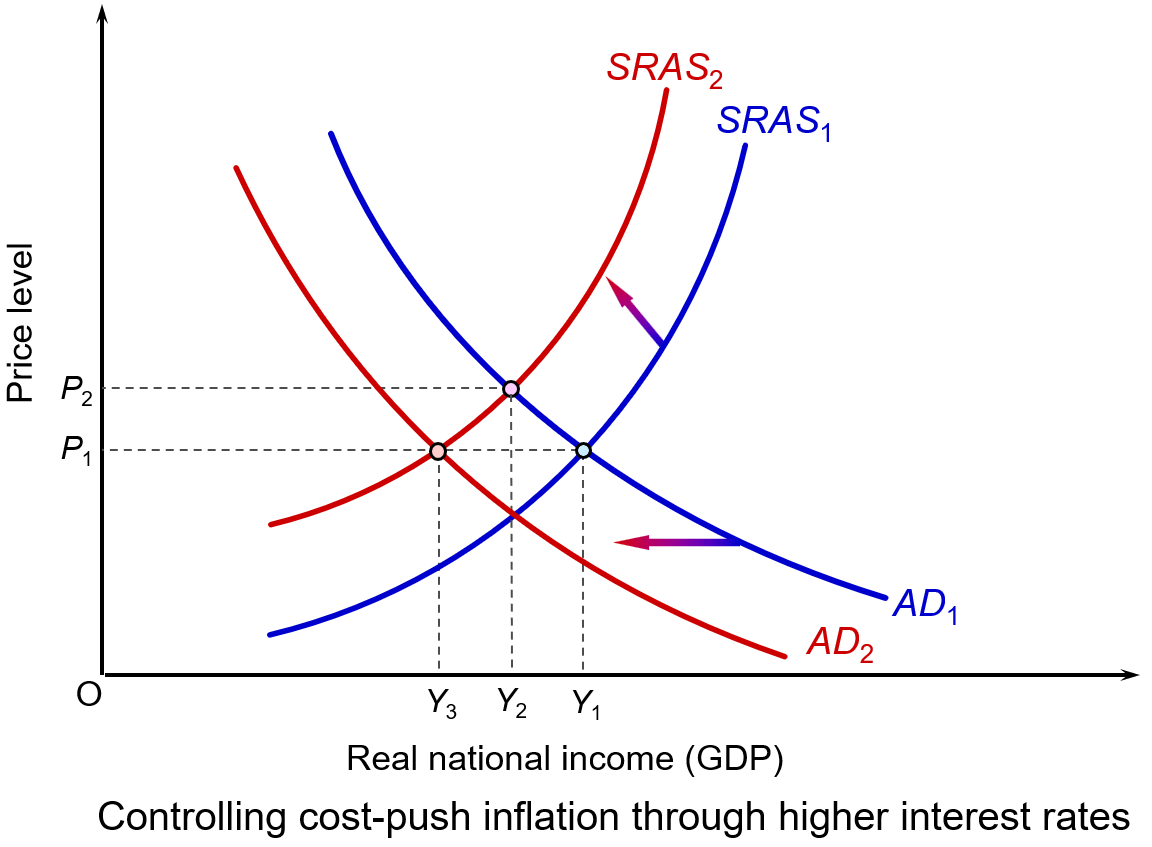 Raising interest rates reduces aggregate demand, or at least its rate of growth. This puts downward pressure on prices, or at least on the rate of inflation. This can be illustrated in the diagram. (Click here for a PowerPoint.)
It shows a country’s initial short-run aggregate supply curve (SRAS1) and initial aggregate demand curve (AD1). The price index is P1 and real GDP is Y1.
The higher costs shift the SRAS curve upwards to the left, say to SRAS2. The price index rises to P2 and real GDP falls to Y2. If, in response to the higher prices, the central bank raises the interest rate, this shifts the aggregate demand curve to the left, say to AD2. As a result, the price index falls back to P1, but the fall in demand causes real GDP to fall further, to Y3.
Policy alternatives
 So, is a rise in interest rates the appropriate response to higher costs that push inflation above, or further above, its target, which for most countries is 2%?
If the cause of inflation was excessive increases in aggregate demand from, say, large government budget deficits or a large increase in consumer demand, then a rise in interest rates would have helped reduce this unsustainable rise in demand. But if the cause of the inflation is a supply shock, is curbing aggregate demand the correct solution?
Ideally, the solution would be to tackle the cost increases directly. A rise in productivity, for example, would help to increase aggregate supply and counter the effect of rising commodity prices. But productivity increases take place over the longer term and are not a solution to a short-term supply shock. Better still, if the increase in commodity prices could be reversed, by finding a political solution that reopened the Strait of Hormuz and other choke points, then higher interest rates would not be needed.
Alternatively, some countries might be able to resort to price controls. These could be targeted at specific sectors such as energy, rent or construction. For example, the UK government has used energy price caps to limit household energy bills.
But even though this may control inflation in the short term, price controls create shortages because demand exceeds the reduced supply. This could lead to higher prices in unofficial markets as people sought to avoid the price controls. It could also create considerable problems for firms planning their logistics when supplies may simply not be available.
Alternatively, subsidies could be used to support output or prices in similar areas. Or they could be targeted at low-income households. These, however, could be costly for governments and may distort markets.
If price controls and subsidies are rejected, and in the absence of short-term increases in aggregate supply, the only solution to inflation is curbing aggregate demand to match the reduced aggregate supply. This could be achieved through fiscal policy by raising taxes or reducing government expenditure, but would prove unpopular and would probably be rejected by governments. Generally, they would prefer to pass the burden to central banks through the use of monetary policy.
The blunt instrument of monetary policy
But, raising interest rates is, indeed, a blunt instrument. Tighter monetary policy cannot increase the global supply of fuel, fix broken supply chains or lower insurance and construction costs. In other words, it cannot directly fix supply shocks, only limit their effect on prices.
 Also, by making borrowing more expensive, higher interest rates may suppress business investment and house building. This adverse supply-side effect may worsen inflation over the longer term.
The hope is that such effects will be avoided by suppressing inflation and helping thereby to maintain business confidence. It is a delicate balancing act for central bankers, who want to constrain inflation but do not want to plunge their economies into recession and damage longer-term increases in potential real GDP.
Most of all, the hope is that by suppressing nominal demand, second-round effects will be avoided. These are where higher prices encourage workers to demand higher wages to compensate for higher prices and businesses to raise prices to cover those wage increases, knowing that they can pass these price increases on to consumers as their competitors are doing the same. This risks creating a damaging wage-price spiral and embedding inflation. By raising interest rates and signalling that they will bring inflation back down to the target rate, central banks hope to anchor long-term inflation expectations. They hope that this will ensure that temporary price shocks do not become permanently embedded in the economy.
Distributional consequences
 However, the burden of higher interest rates will not be shouldered equally. They predominantly penalise a minority of the population, especially younger households with consumer debt and/or large variable-rate mortgages relative to their income or fixed rate mortgages coming the end of their term and requiring renewing. They also penalise businesses which rely on short-term debt.
Meanwhile, people who own their homes outright or wealthy savers may be largely unaffected or even benefit from higher yields on their savings deposits. Similarly, firms with low debt may hardly be affected.
Consequences for servicing public debt
Higher interest rates increase governments’ debt-servicing costs. More has to be paid on new borrowing, either to finance budget deficits or to replace government bonds and bills that are maturing. This consumes a larger share of public spending and limits the fiscal room to support vulnerable households suffering from the price and interest increases.
We examined such costs in the US context in the blog US national debt reaches $40 trillion: but does it matter?.
Fingers crossed!
By being cautious about raising interest rates, central banks hope that geopolitical developments will be favourable and that the supply constraints will diminish. For example, the hope is that there will be a settlement between the USA and Iran that allows oil to flow once more through the Strait of Hormuz. That is why, despite inflation being well above target, central banks have been raising interest rates by just a quarter of a percentage point.
Articles
- US interest rates raised for first time in three years
BBC News, Michael Race (17/9/26)
- What the Fed interest rate hike likely means for borrowers and savers
NBC4 New York, Paul Wiseman (16/9/26)
- How increasing interest rates could reduce inflation, but potentially cause a recession
CNBC, Trina Paul (21/9/26)
- Interest rates held but Bank signals rise if energy prices stay high
BBC News, Dearbail Jordan and Kevin Peachey (17/9/26)
- Bank of England defies Fed’s rate-hike lead, leaving rates unchanged
CNBC, Chloe Taylor (17/9/26)
- ECB hikes rates to 2.5% as energy shock pushes eurozone inflation higher
Euronews, Quirino Mealha (10/9/26)
- Japan raises interest rates to 31-year high to curb impact of rising prices
The Guardian, Mark Sweney (18/9/26)
- What exactly is inflation, and are interest rates the only option for dealing with it?
The Conversation, Luke Hartigan (10/2/26)
- US consumers and businesses are now facing a future of more expensive borrowing
The Conversation, John W Diamond (16/9/26)
- Inflation: raising interest rates was never the right medicine – here’s why central bankers did it anyway
The Conversation, Robert Gausden (20/10/23)
- There are three main reasons inflation is rising. Higher rates won’t fix them
ABC (Australia), Michael Janda (15/9/26)
- Higher interest rates are meant to lower inflation. US economist John Cochrane says there’s only ‘shaky’ evidence it works
ABC (Australia), Michael Janda and Alicia Barry(15/3/24)
- How Governments Fight Inflation with Monetary Policies
Investopedia, Leslie Kramer (11/3/26)
- Interest rates are not the tool to solve the inflation caused by the US’s war with Iran
The Guardian, Josh Ryan-Collins (18/3/26)
- Are higher interest rates the only tool for managing inflation?
Rethinking Economics, Tim Thornton (3/8/23)
Videos
Information
Questions
- What policies have central banks pursued during the Iran war?
- Paint an optimistic scenario for the global economy five years hence.
- Paint a pessimistic scenario for the global economy five years hence.
- Compare the reasons given by the Federal Reserve and ECB for raising interest rates with those given by the Bank of England for not raising them.
- Donald Trump argues for cutting interest rates as a stimulus to the US economy. Provide a critique of this policy.
 The world has suffered from a number of adverse supply shocks in recent years. First there was the credit supply shock of 2007–9 that led to a default on mortgages, a collapse in confidence in the banking system, the drying up of the inter-bank market, the freezing of lending and a global economic contraction. Then there was the COVID-19 pandemic. This shock to the the global economy led to a a fall in output and breaks in supply chains. As recovery took place, supply-side difficulties led to a surge in inflation.
Then there was the Russian invasion of Ukraine. This shock to energy and grain supplies led to rises in fuel and food prices: a cost-push inflationary shock. More recently, the closing of the Strait of Hormuz has cut off an important supply route and again sent fuel and other other prices rising.
These supply-side shocks create a dilemma for central banks. They push up inflation, but push output and employment down – a situation of ‘stagflation’.
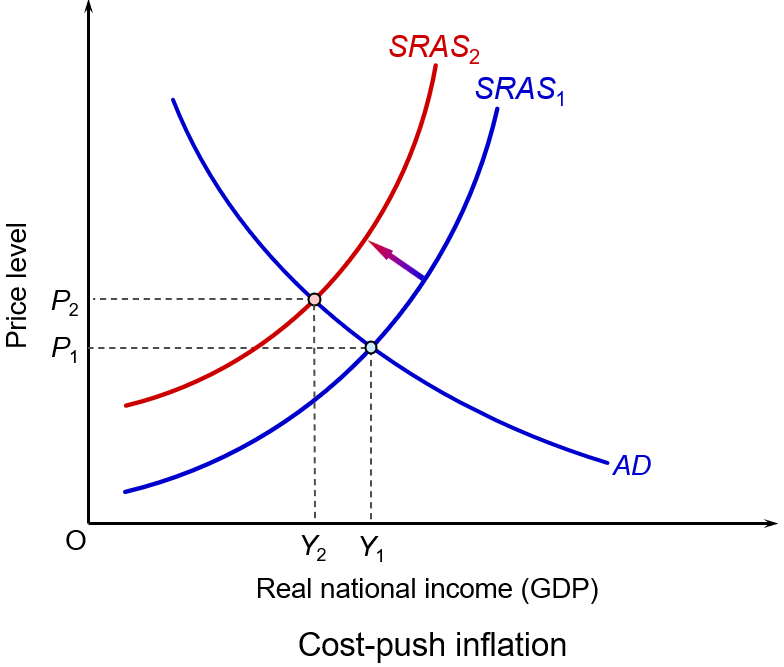 This can be illustrated with a simple aggregate demand and supply diagram. The shock shifts the aggregate supply curve upwards to the left, illustrated by the move from SRAS1 to SRAS2. The price level rises to P2 and GDP falls to Y2.
But central bank policy is designed to affect aggregate demand, not aggregate supply. If it raises interest rates, aggregate demand will shift to the left. The price level will fall (or at least the rate of inflation will fall), but output will fall further. If it cuts interest rates, aggregate demand will shift to the right. This will help to curtail, or even reverse, the fall in GDP, but will lead to even higher prices.
For countries where their central bank has a simple inflation mandate (e.g. keeping inflation close to 2%), sticking to this target in the short term would result in higher interest rates, lower economic growth and higher unemployment – and possibly even a recession. In such cases, central banks tend to project forward beyond the short-term shock and set interest rates to target inflation in a few months’ time. Indeed, many central banks do explicitly target inflation in the medium term (1 or 2 years) rather than the short term.
 Central banks, such as the US Federal Reserve Bank, which have a dual mandate of targeting inflation but also maximising employment, the trade-off between these two objectives can be stark. Getting the inflation down requires a higher rate of interest; maximising employment in the face of an adverse supply shock requires a lower rate of interest.
The short-term economic costs, let alone the human costs if the shock involves a war, can be great. People may suffer extreme hardship. The cost to the US Treasury of the first six weeks of the Iran war were estimated by the Pentagon to be some $29bn1 – which translates into higher taxes for US residents, lower government spending on non-war related items, higher government borrowing or some combination of the three. Other estimates put the cost to the US taxpayer as much higher – up to $1 trillion over the longer term.2 Then there are the costs to consumers of higher fuel and other prices, estimated at around $410 per month.3
The costs to Iranian citizens will be much higher in terms of war damage and loss of livelihood, let alone the suffering and loss of life. Then there are the costs to the rest of the world from higher prices of fuel, fertilisers and various industrial materials that are normally shipped through the Strait of Hormuz.
Long-term economic gain?
 Supply shocks often expose economic vulnerabilities that can later be addressed, making supply chains more diverse and more resilient. They can give a boost to alternative technologies, such as a switch from fossil-fuels to green energy.
After the 2007–9 financial crisis, banking systems were made more robust under the Basel III system. Capital and liquidity requirements were increased and bank leverage was decreased. Many countries, such as the UK, introduced ‘ringfencing’ to separate retail banking from the riskier investment banking. This increased confidence in the banking system.
The COVID-19 pandemic gave a boost to working remotely and the establishment of more flexible work patterns. What was a necessity during lockdowns, was seen as an effective model by many companies. Fully remote or hybrid working became commonplace for many jobs that were previously done in the office. Time has allowed employers to find the best balance of in-office and remote working, with the optimum balance often varying by type of job being performed.
The rising price of oil and gas following the Russian invasion of Ukraine in February 2022, saw many countries that had been reliant on imports from Russia, accelerating their efforts to switch to renewable energy. Supply chains were re-examined and there was a move towards ‘re-shoring’, ‘near-shoring’, or ‘friend-shoring’: that is, obtaining supplies from countries that are nearer and/or more reliable as trading partners.
 This approach was further boosted by the extensive tariffs imposed by the Trump second administration. One of the responses to the higher tariffs was to seek markets, both for exports and imports, away from the USA. To the extent that there is ‘re-shoring’ (substituting exports and imports for production and consumption within the country), then this amounts to deglobalisation. If this represents a move from low-cost to high-cost production and is contrary to the law of comparative advantage, then there will be a net economic loss. If, however, the reduction in risk of disruption and the boost to domestic industries allows a reduction in costs, there could be a net gain.
The most recent example of the Iran war has led many countries to reconsider sources of supply and to make their supply chains more robust and less risky. Gulf countries are considering expanding their pipeline network to avoid the Strait of Hormuz. For other countries, it is providing a further boost to green energy. Increased investment in the renewable sector will help to bring down costs and make countries less vulnerable to future conflicts involving oil-producing countries or sea passages.
To summarise: if initially adverse supply-side shocks cause a diversification and strengthening of supply chains, a diversification of energy sources, accelerated technological innovation and the adoption of new more efficient techniques, the long-term supply-side effects could be positive. Pain today for gain tomorrow?
But the short run comes before the long run and today’s costs are real and mounting. A shock may stimulate a positive response, but the current shock is persisting, and forecasts are getting more dire by the day. And even when the Iran war is over, there may be more shocks around the corner – ‘unknown unknowns’. As Keynes said: ‘In the long run we’re all dead’.
References
- Pentagon’s estimate for Iran war grows to $29B
Politico, Mark Sweney (12/5/26)
- World Politics The Iran war could cost the American taxpayer $1 trillion, says Harvard academic
CNBC, Joseph Wilkins (14/4/26)
- The Economic Costs of the Iran War
American Enterprise Institute, Roger Pielke Jr. (2/4/26)
Articles
Questions
- What policies have central banks pursued during the Iran war?
- Paint an optimistic scenario for the global economy five years hence.
- Paint a pessimistic scenario for the global economy five years hence.
- Compare the sources of supply of oil and gas for Europe directly prior to the Iran war with those directly prior to the Russian invasion of Ukraine.
- Compare the relative merits of globalisation and deglobalisation. Does this depend on the nature of globalisation and deglobalisation?
 Central bankers, policymakers, academics and economists met at the Economic Symposium at Jackson Hole, Wyoming from August 24–26. This annual conference, hosted by Kansas City Fed, gives them a chance to discuss current economic issues and the best policy responses. The theme this year was ‘Structural Shifts in the Global Economy’ and one of the issues discussed was whether, in the light of such shifts, central banks’ 2 per cent inflation targets are still appropriate.
Inflation has been slowing in most countries, but is still above the 2 peer cent target. In the USA, CPI inflation came down from a peak of 9.1% in June 2022 to 3.2% in July 2023. Core inflation, however, which excludes food and energy was 4.7%. At the symposium, in his keynote address the Fed Chair, Jay Powell, warned that despite 11 rises in interest rates since April 2022 (from 0%–0.25% to 5%–5.25%) having helped to bring inflation down, inflation was still too high and that further rises in interest rates could not be ruled out.
We are prepared to raise rates further if appropriate, and intend to hold policy at a restrictive level until we are confident that inflation is moving sustainably down toward our objective.
However, he did recognise the need to move cautiously in terms of any further rises in interest rates as “Doing too much could also do unnecessary harm to the economy.” But, despite the rises in interest rates, growth has remained strong in the USA. The annual growth rate in real GDP was 2.4% in the second quarter of 2023. Unemployment, at 3.5%, is low by historical standards and similar to the rate before the Fed began raising interest rates.
Raising the target rate of inflation?
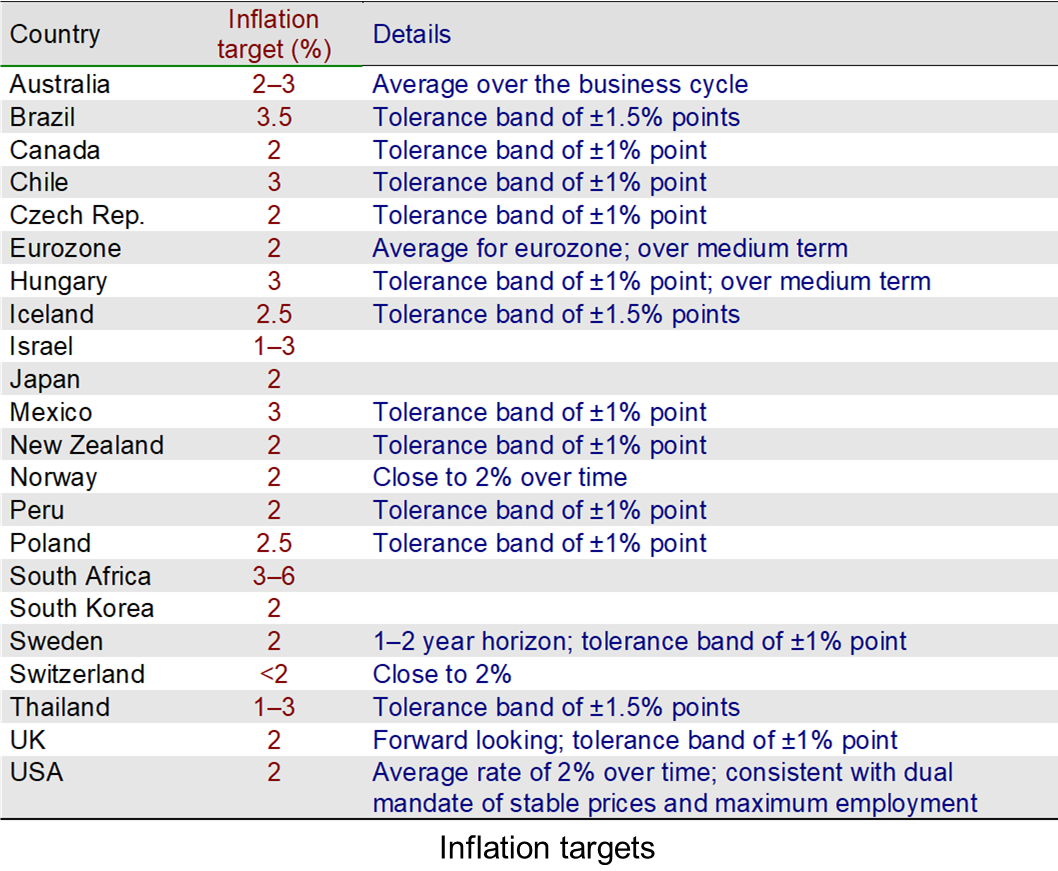 Some economists and politicians have advocated raising the target rate of inflation from 2 per cent to, perhaps, 3 per cent. Jason Furman, an economic policy professor at Harvard and formerly chief economic advisor to President Barack Obama, argues that a higher target has the benefit of helping cushion the economy against severe recessions, especially important when such there have been adverse supply shocks, such as the supply-chain issues following the COVID lockdowns and then the war in Ukraine. A higher inflation rate may encourage more borrowing for investment as the real capital sum will be eroded more quickly. Some countries do indeed have higher inflation targets, as the table shows.
Powell emphatically ruled out any adjustment to the target rate. His views were expanded upon by Christine Lagarde, the head of the European Central Bank. She argued that in a world of greater supply shocks (such as from climate change), greater frictions in markets and greater inelasticity in supply, and hence greater price fluctuations, it is important for wage increases not to chase price increases. Increasing the target rate of inflation would anchor inflationary expectations at a higher level and hence would be self-defeating. Inflation in the eurozone, as in the USA, is falling – it halved from a peak of 10.6% in 2022 to 5.3% in July this year. Given this and worries about recession, the ECB may not raise interest rates at its September meeting. However, Lagarde argued that interest rates needed to remain high enough to bring inflation back to target.
The UK position
 The Bank of England, too, is committed to a 2 per cent inflation target, even though the inflationary problems for the UK economy are greater that for many other countries. Greater shortfalls in wage growth have been more concentrated amongst lower-paid workers and especially in the public health, safety and transport sectors. Making up these shortfalls will slow the rate of inflationary decline; resisting doing so could lead to protracted industrial action with adverse effects on aggregate supply.
Then there is Brexit, which has added costs and bureaucratic procedures to many businesses. As Adam Posen (former member of the MPC) points out in the article linked below:
Even if this government continues to move towards more pragmatic relations with the EU, divergences in standards and regulation will increase costs and decrease availability of various imports, as will the end of various temporary exemptions. The base run rate of inflation will remain higher for some time as a result.
Then there is a persistent problem of low investment and productivity growth in the UK. This restriction on the supply side will make it difficult to bring inflation down, especially if workers attempt to achieve pay increases that match cost-of-living increases.
Sticking to the status quo
There seems little appetite among central bankers to adjust inflation targets. Squeezing inflation out of their respective economies is painful when inflation originates largely on the supply side and hence the problem is how to reduce demand and real incomes below what they would otherwise have been.
Raising inflation targets, they argue, would not address this fundamental problem and would probably simply anchor inflationary expectations at the higher level, leaving real incomes unchanged. Only if such policies led to a rise in investment would a higher target be justified and central bankers do not believe that it would.
Articles
- What happens in Jackson Hole doesn’t stay in Jackson Hole
CNN, Elisabeth Buchwald (26/8/23)
- Fed Chair Powell calls inflation ‘too high’ and warns that ‘we are prepared to raise rates further’
CNBC, Jeff Cox (25/8/23)
- Inflation? This man holds the key
Politico, Geoffrey Smith and Carlo Boffa (24/8/23)
- Global inflation pressures could become harder to manage in coming years, research suggests
Independent, Christopher Rugaber (27/8/23)
- Christine Lagarde warns of long-term inflation risks after global economic upheaval
Financial Times, Martin Arnold and Colby Smith (25/8/23)
- No appetite at Fed, ECB for changing inflation goal
Reuters, Ann Saphir, Howard Schneider and Balazs Koryani (25/8/23)
- Is it time for Fed to raise interest rate target to 3%? Experts weigh in
mint, Nishant Kumar (22/8/23)
- What is the UK inflation rate and why is it so high?
BBC News (16/8/23)
- If you think the UK’s high-inflation cycle has run its course, think again
The Observer, Adam Posen (26/8/23)
Data
Questions
- Use an aggregate demand and supply diagram (AD/AS or DAD/DAS) to illustrate inflation since the opening up of economies after the COVID lockdowns. Use another one to illustrate the the effects of central banks raising interest rates?
- Why is the world likely to continue experiencing bigger supply shocks and greater price volatility than before the pandemic?
- With hindsight, was increasing narrow money after the financial crisis and then during the pandemic excessive? Would it have been better to have used the extra money to fund government spending on infrastructure rather than purchasing assets such as bonds in the secondary market?
- What are the arguments for and against increasing the target rate of inflation?
- How do inflationary expectations influence the actual rate of inflation?
- Consider the arguments for and against the government matching pay increases for public-sector workers to the cost of living.
The mandates of central banks around the world are typically focused on controlling inflation. In many cases, this is accompanied by operational independence from government, but with the government setting an inflation target. The central bank then chooses the appropriate monetary policy to achieve the inflation target. This is argued to provide the conditions that can deliver lower and less variable inflation rates – at least over the longer term.
However, some economists argue that this has the potential to create the conditions for greater economic volatility and financial instability. The events surrounding the collapse of Silicon Valley Bank (SVB) – the largest since the global financial crisis – have helped to reignite these debates.
Inflation targeting central banks
The theoretical foundations for delegating monetary policy to central banks with mandates to meet an inflation rate target is often attributed to the paper of Fynn Kydland and Edward Prescott published in the Journal of Political Economy in 1977. It argues that if governments, rather than independent central banks, operate monetary policy, systemically-high inflation can become established if low-inflation announcements by governments lack credibility. Delegation of monetary to a central bank with an inflation rate target, however, can create the necessary conditions for credibility. This, in turn, gives the public confidence to maintain lower and more stable inflationary expectations than would otherwise be the case.
To mitigate the problem of a potential inflationary bias, it is argued that governments should delegate monetary policy to a conservative central banker: one that places less weight on output or employment stabilisation and more weight on inflation stabilisation than does society. However, as identified by Kenneth Rogoff in his paper published in the Quarterly Journal of Economics in 1985, this raises the spectre of greater volatility in output and employment when economies are buffeted by supply shocks.
Inflation–output stabilisation trade-off
The inflation–output stabilisation trade-off identified by Rogoff has particular relevance to the macroeconomic environment experienced by many countries in recent times. As economies began to open up after the pandemic, demand–supply imbalances saw the 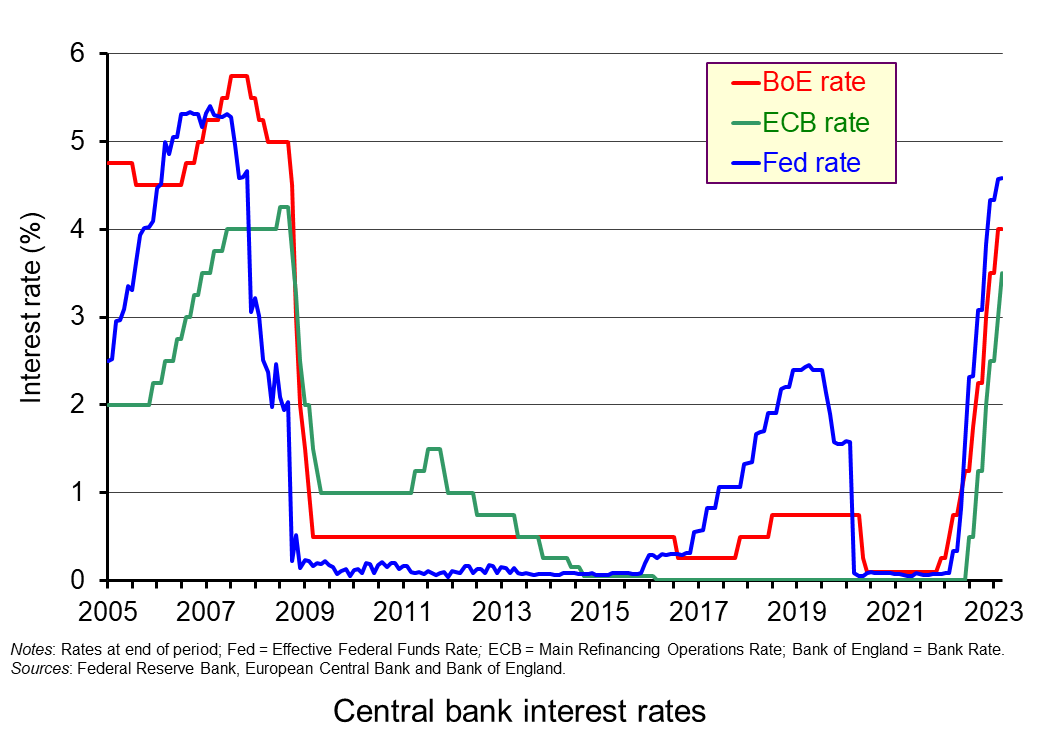 emergence of inflationary pressures. These pressures were then exacerbated by the Russian invasion of Ukraine, which drove up commodity prices.
Rather than pursuing a less contractionary policy in the face of these supply shocks so as to avoid recession, central banks stuck to their inflation mandates and hence raised interest rates significantly so as to bring inflation back to target as soon as possible. But this hampered economic recovery.
Inflation–financial stability trade-off
Yet the recent financial turmoil suggests a further inflation–stability trade-off: an inflation–financial stability trade-off. By raising interest rates, different sectors of the economy are liable to greater financial distress. This distress has contributed to the collapse of Silicon Valley Bank and Signature Bank, and led to a significant injection of funds by large US banks into First Republic. The fear is of a contagion within the financial sector, which then spills into other sectors of the economy.
The debate about central bank mandates and the weight attached to inflation stability relative to other objectives is therefore centre stage of macroeconomic policy debates.
Articles
- Inflation targeting and the 2 per cent goal
Financial Times, Editorial Board (16/12/22)
- Breaking the shackles of inflation targets
The Business Standard, Daniel Moss, Bloomberg (16/3/23)
- Evaluating Monetary Policy with Inflation Bands and Horizons
Federal Reserve Bank of San Francisco, letter, Troy Davig and Andrew Foerster (21/2/23)
- Need to rethink long-term inflation target: MPC member Ashima Goyal
The Economic Times (India) (15/3/23)
- Inflation Targeting Pros and Cons
Economicshelp, Tejvan Pettinger (16/11/17)
- Central banks walk tightrope in juggling mandates
Reuters, Mike Dolan (15/3/23)
- Silicon Valley Bank: why did it collapse and is this the start of a banking crisis?
The Guardian, Jonathan Barrett (13/3/23)
- Silicon Valley Bank: Regulators take over as failure raises fears
BBC News (11/3/23)
- HSBC swoops in to rescue UK arm of Silicon Valley Bank
BBC News, Michael Race (13/3/19)
- Silicon Valley Bank said it was too small to need regulation. Now it’s ‘too big to fail’
The Guardian, Rebecca Burns and Julia Rock (17/3/23)
- Multi-billion dollar rescue deal for First Republic Bank
BBC News, Natalie Sherman (16/3/19)
- Chancellor ‘welcomes’ decision to give Credit Suisse £44.5bn lifeline as shares bounce back
Sky News, Samuel Obsborne (16/3/23)
Questions
- Explain the argument that the delegation of monetary policy can help to keep the average rate of inflation lower.
- How might the monetary policy responses of central banks to an inflation shock create the possibility of an inflation–output stabilisation trade-off?
- What do you understand by a Taylor rule? Could this help to alleviate the inflation-output stabilisation trade-off?
- Some economists argue that there is less of a trade-off between inflation and output stability with demand-pull inflation because of a so-called ‘divine coincidence’ in monetary policy. Why might this be the case?
- What do you understand by the term ‘financial distress’? What metrics could be used to capture this for different sectors of the economy?
- Explain how financial contagion can spread both within and between different sectors of the economy.
Aggregate demand has been booming as the world bounces back from the pandemic. At the same time, aggregate supply is severely constrained. These supply constraints are making potential national income smaller – at least temporarily. The result is that many countries are heading for recession.
At the same time, supply constraints are causing prices to rise, especially energy and food prices. This cost-push inflation is made worse by the rises in aggregate demand.
The result is ‘stagflation’ – a recession, or stagnation, accompanied by high inflation. In the UK, the latest Bank of England Monetary Policy Report forecast that by the end of 2022, CPI inflation would be 13.1% and that in 2023, real GDP would fall by 1.5%.
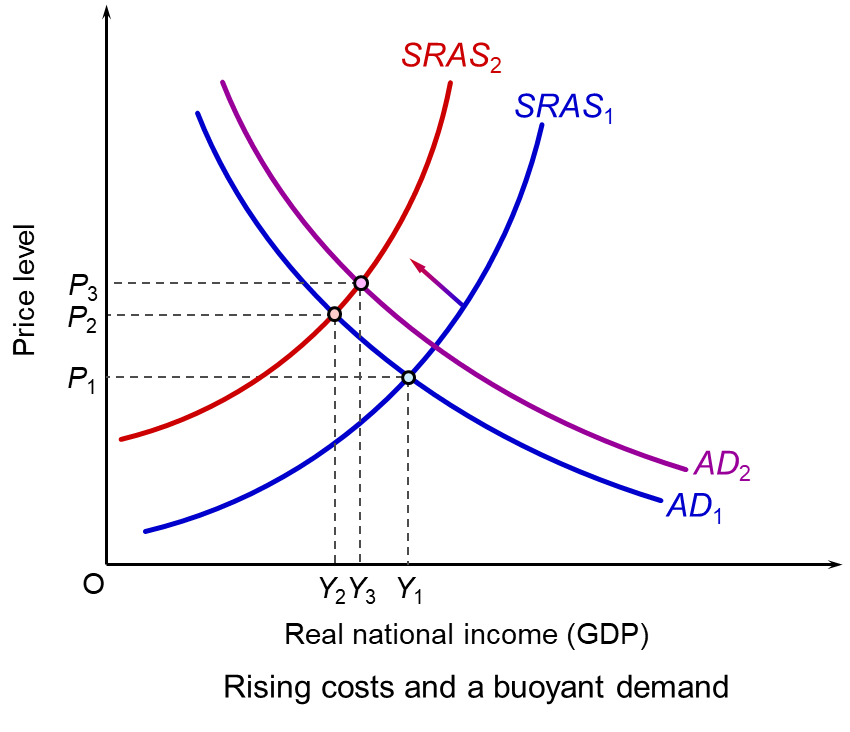 This effect of an adverse supply shock accompanied by relatively buoyant aggregate demand (at least initially) can be illustrated with an aggregate demand and supply diagram. The supply shock is illustrated by an upward shift to the left of the short-run aggregate supply curve (SRAS). (If the shock is a direct rise in prices, then it can be seen as a vertical upward shift. If it is a fall in the total amount supplied, then it can be seen as a horizontal leftward shift.) In the diagram, aggregate supply shifts from SRAS1 to SRAS2. The price level rises from P1 to P2. If costs go on rising or supply goes on falling then the curve will go on shifting upwards to the left.
If the government responds by increasing benefits or reducing taxes, then, other things being
equal, aggregate demand will rise. In the diagram, the AD curve will shift to the right, e.g. from AD1 to AD2. Real GDP only falls to Y3 not Y2. However, the price level rises further: from P2 to P3.
Why has aggregate supply fallen?
There are several factors that have contributed to the fall in aggregate supply/rise in costs.
- Stretched supply chains, which had been adversely affected by Covid. Congestion at container ports has led to delays, with warehouses and shops being short of stock.
- Labour shortages, with many people not returning to the labour force after being laid off or furloughed, or only returning part time, leaving firms needing more people. The problem has been particularly acute in the UK, with many EU citizens having returned to the EU after Brexit and the UK having to rely increasingly on staff from outside the EU.
 The war in Ukraine. This has had a major impact on the supply of natural gas and oil. The war has also led to a fall in grain and other food supplies from Ukraine, as ports have been blockaded and there have been disruptions to planting and harvesting.
- Climate change is causing more severe weather events, such as droughts in Europe and western USA. The droughts of 2022 will compound the problem of food shortages and food price inflation.
- In the UK, Brexit costs, such as increased administrative burdens and difficulties in both exporting and importing, have dampened production and hence adversely impacted on aggregate supply.
- Increased industrial action. As the cost of living soars, unions are demanding pay increases to match the rise in the cost of living. Pay rises further increase firms’ costs – and the bigger the pay rises, the bigger the rise in costs.
The problem with a fall in aggregate supply is that it reduces real GDP. People as a whole are poorer. To use a common analogy, the national ‘pie’ has shrunk. Giving everyone a bigger knife and fork (i.e. a rise in nominal aggregate demand) will not make people better off. It just compounds the problem of rising prices, as the diagram shows.
In the short term, with GDP shrinking, there is a major issue of distribution. If the poor are to be given help so that they are not made even poorer, then other people will have been made worse off. In other words, their nominal incomes must rise more slowly than prices.
Monetary policy
 Central banks generally have a mandate of keeping inflation close to 2% over the medium term. Their levers are changes in interest rates, underpinned by changes in the money supply – in extreme times by quantitative easing (creating money by buying assets with newly created money) or quantitative tightening (withdrawing money from the economy by selling assets). Central banks, faced by soaring inflation, have been raising interest rates. The Fed has recently raised the Federal Funds rate by 0.75 percentage points (75 basis points) and the Bank of England and the European Central Bank by 0.5 percentage points (50 basis points).
Raising interest rates reduces inflation by dampening aggregate demand. In the diagram, the AD curve shifts to the left (or shifts to the right less quickly). This will dampen inflation, as falling real demand will force firms to cut prices. But it will also force them to cut output and employment, thereby worsening the recession.
Central banks recognise this dilemma, but also recognise that if inflation is not brought rapidly under control, it could spiral upwards, with wages and prices chasing each other in a wage–price spiral, which only gets worse as inflationary expectations rise. The short-term pain of falling real income is a price worth paying for getting inflation under control.
Fiscal policy
In the short term, there is little that fiscal policy can do to raise real GDP. The focus, as it was during the pandemic, must therefore be in providing relief to those most in need.
In the UK, the energy price cap set by Ofgem will see likely energy bills for the typical household quadruple in just a year, from a little over £1000 per annum at January 2021 prices to over £4200 in predicted January 2023 prices. These higher prices partly reflect rising wholesale energy costs and partly the need for energy companies, in a process known as ‘backwardation’, to recoup hedging costs they have incurred so as not to be forced out of business.
 Relief for consumers can be in various forms. For example, the government could pay subsidies to energy suppliers to cap prices at a lower level, perhaps just for the poorest households. Or it could pay grants to help people with their bills. Again, these could be targeted to the poorest families, or paid on a sliding scale according to income. Or VAT on gas and electricity could be scrapped.
Generally the more people are entitled to help, the more expensive it is for the government and hence the less generous the help per family is likely to be.
Then there is the question of whether such measures should be accompanied by a rise in broadly-based tax, such as income tax, or whether the government should borrow more, which would be likely to push up interest rates and increase the cost of servicing government debt.
One topic of debate in the Conservative leadership contest is whether taxes should be cut to help people struggling with the cost of living. Whilst such a policy, if carefully targeted to investment, might increase aggregate supply over the longer term, in the short term it will increase aggregate demand and will add to inflationary pressures.
Targeting tax cuts to the poor is difficult. Cutting income tax rates has the opposite effect. The rich pay more income tax than the poor and will benefit most from a cut in rates. An alternative is to raise personal allowances. This will provide a bigger percentage help to income taxpayers on lower incomes, but provides no help at all for the poorest people who currently pay no income tax.
Conclusion
The supply shocks are making countries poorer. The focus in the short term, therefore, needs to be on income distribution and how to help those suffering the most.
To end on a note of optimism: the energy shocks are causing governments to invest in alternative sources, such as wind, solar and nuclear. When these come on line, it is expected that energy prices will fall.
As far as overall inflation is concerned, although the Bank of England is forecasting CPI inflation of 13.1% by Q4 2022, it is also forecasting that this will have fallen to 5.5% by Q4 2023 and to just 0.8% by Q3 2024. Fingers crossed.
 US hikes interest rates as fears grow of global oil shock over Iran War
