 The television streaming market is currently attracting considerable attention from policy makers. This follows Warner Bros. accepting Netflix’s offer to buy part of the company for $72bn. To understand how this deal came about and why there is policy concern, we need to go back a few years.
The media and entertainment conglomerate Warner Bros. Discovery (WBD) was created in 2022 when AT&T sold Warner Bros to Discovery.1 However, in June 2025 the company announced that it would split the business into two parts. One would be (a) the studio for TV and movie production, where for example the Harry Potter franchises were made, and (b) the TV streaming business, home to for example the hit TV series Succession. The other, the more traditional and declining TV networks, including channels such as CNN, Discovery and TNT Sports, would form a new company called Discovery Global. David Zaslav, WBD President and Chief Executive stated that:
We are empowering these iconic brands with the sharper focus and strategic flexibility they need to compete most effectively in today’s evolving media landscape.2
Shortly afterwards, rival media and entertainment conglomerate, Paramount Skydance, made a series of bids to purchase the entire WBD business. But these were rejected by the WBD board. Despite this, in October 2025 WBD made public that it was open to a sale and had received unsolicited interest from several companies. It was believed that this included offers from Comcast and Netflix.
Recent developments
 In December 2025, Netflix announced that it had agreed a deal with WBD to buy its studio and streaming service business, including its back catalogue of shows. The deal is planned to be put to WBD shareholders in the next few months.3 Netflix has over 300m subscribers across the globe and streams popular shows, such as Stranger Things and Squid Games.
Despite this accepted offer, Paramount has subsequently pursued a hostile takeover of WBD by going straight to its shareholders. In addition, Paramount launched a lawsuit to get further information on how Netflix was chosen as the buyer and to provide WBD shareholders with information on the value of the TV network business that WBD was selling. This, however, was quickly thrown out of the courts.
Over time, Netflix and Paramount have tinkered with their bids to make them more attractive to WBD. Whilst Paramount’s bid was all cash, originally Netflix was offering a mixture of cash and shares. However, in January, it switched this to an all-cash offer. In February, Paramount made clear that if WBD instead accepted its offer, it would pay the $2.8bn termination fee that would be owed to Netflix.4 Furthermore, from early 2027 Paramount would pay WBD shareholders payments of $650m per quarter, known as ticking fees, if combining WBD and Paramount faced regulatory delay.
In mid-February 2026, it emerged that, following a waiver from Netflix, WBD had reopened talks with Paramount. Paramount was given a week to make its offer. Then, under the agreed deal, Netflix would have the right to adjust its bid. This is an attempt by WBD to end the hostile bidding war Paramount is pursuing and to provide clarity for its shareholders. WBD has reiterated that it will:
continue to recommend and remain fully committed to our transaction with Netflix. [However], we welcome the opportunity to engage with you and expeditiously determine whether Paramount Skydance can deliver an actionable, binding proposal that provides superior value.5
The insertion of the ticking fees by Paramount is in response to the substantial attention competition authorities across the globe are paying to the acquisition of WBD. The deal is being investigated by the US Department of Justice and, in early February, Netflix was questioned by the US Senate Antitrust Sub-committee. During this hearing, one of the Senators expressed his anger with the country’s competition laws and raised concerns that the deal would result in Netflix getting:
more power over consumers and leaving fewer alternatives and streaming platforms.6
While Paramount did not attend this hearing, it is believed that it has raised concerns about the Netflix-WBD deal to regulators. Netflix co-CEO, Ted Sarandos, has also met with Donald Trump to discuss the deal. However, Trump subsequently stated that the deal ‘could be a problem’.7
The EU and UK markets
 Furthermore, whilst all the companies involved are American, both the mergers with Netflix and Paramount are being investigated by the European Commission as markets in Europe would be affected.
In the UK, a group of politicians and former policymakers, have written to the Competition and Markets Authority urging it to conduct a full investigation of the Netflix-WBD merger. The letter argues that the merger could have:
damaging consequences for consumers, the UK’s world-leading creative industries and the UK cinema industry.
and that:
At a time when the British consumer can ill-afford more price increases, Netflix would possess an unprecedented ability to raise prices to access television and films.8
 The letter comes at a time when pressure is being placed on the CMA to adopt a generally more business-friendly approach.
The impact of the merger on the UK market is particularly complicated since Warner Bros.’ streaming service, HBO Max, is only due to launch in the UK in March 2026. This is still the plan, with WBD’s head of global streaming, Jean-Briac Perette acknowledging that:
We are likely the last scaled global streamer to come to market. We’ve tried to learn from the rest. We’re a complementary and distinct service to the more volume-driven or basic cable-like streamers in the market. More is not better. Better is better.9
An alternative route to regulatory approval
An easier route to regulatory approval may well be instrumental in allowing Netflix or Paramount to win the battle for WBD. Netflix stresses that the deal will create economic growth and jobs. Netflix’s Sarandos highlighted that:
This is not a typical media merger where you end up with what’s called the Noah’s Ark problem — two of everything. We are buying a company that has assets that we do not, and we will keep investing in those.10
The problem of economic power
In contrast, critics argue that either of the deals would create a new company with too much power. However, given the nature of the firms involved, the competition issues will be fundamentally different between the two deals.
 The Paramount deal would primarily reduce the number of studios in the market. This could provide the new merged studio with more bargaining power over distributors, advertisers and creators. Ultimately, this could negatively impact on the final product that consumers watch in the cinema and on television.
The Netflix deal on the other hand would impact directly on the streaming market. In the USA, 80% of consumers have both Netflix and HBO Max.11 After the merger, consumers would have less choice of competing services and Netflix-HBO Max combined may well have an incentive to raise its subscription prices.
In the UK, there are currently three leading streaming services: Netflix, Amazon Prime and Disney+, each with around 23% of the market.12 The merger with WBD could allow Netflix to become the clear market leader.
Concerns about YouTube
When examining streaming markets in all countries, an important factor will be whether to include YouTube in the market. Netflix certainly argues that it is a key competitor, at the hearing Sarandos stated that:
we are competing for the same content, we are competing for the same viewers, we are competing often for the same ad dollars. YouTube is not just cat videos anymore. YouTube is TV.13
If YouTube is included, in the USA it would be the market leader with 13%, ahead of Netflix on 9%. However, the competition authorities may conclude that YouTube’s product and business model is sufficiently different and so not include it in the streaming market.14
The issue of cinemas
 A second concern in the Netflix deal will be the Warner Bros.’ studio content that Netflix would own. The merged business may have an incentive to discontinue, raise the price or reduce the quality of the studio output that it supplies to cinemas. Thus, the competition authorities’ investigations will also pay close attention to the impact on the cinema market.
In line with these arguments, the Hollywood screenwriters’ union, the Writers Guild of America, has indicated that the Netflix-WMD deal should be stopped and filmmakers are clearly concerned about Netflix prioritising streaming.15
The competition authorities may well consider imposing remedies before they are willing to allow either deal to go ahead. With this in mind, it is interesting that Netflix has already made clear that it will continue the 45-day exclusive window that Warner Bros. provides cinemas to show its films.
It will be fascinating to see how the competing bids play out and how the competition regulators view them.
* * *
This post has been updated in a Postscript, following a further bid from Paramount that was not matched by Netflix.
References
- AT&T agrees deal to combine WarnerMedia with Discovery
The Guardian, Mark Sweney (16/5/21)
- HBO and CNN owner to split streaming and cable businesses
BBC News, Adam Hancock (10/6/25)
- Netflix’s co-CEO went to an antitrust hearing and a culture war broke out
NBC News, Saba Hamedy (3/2/26)
- Warner Bros gives Paramount seven days to make ‘best and final’ offer
The Guardian, Mark Sweney (17/2/26)
- ibid.
- NBC News, op. cit.
- Trump says $72bn Netflix-Warner Bros deal ‘could be a problem’
BBC News, Osmond Chia (8/12/25)
- UK politicians call for competition review of Netflix bid for Warner Bros
Financial Times (26/1/26)
- Warner streaming boss defends HBO Max UK launch ahead of Netflix takeover
Financial Times (9/2/26)
- NBC News, op. cit.
- Netflix and Warner Bros struggle to defend merger
BBC News, Danielle Kaye (3/2/26)
- Netflix, Disney+, Prime: Streaming platform market share report UK 2025
InsiderMedia, Jennifer O’Keeffe (2/12/25)
- BBC News, Danielle Kaye op. cit.
- Paramount sweetens Warner Bros bid with offer to pay Netflix break-up cost, other fees
Reuters, Harshita Mary Varghese and Aditya Soni (11/2/26)
- In a takeover of Warner Bros., Netflix makes a play for 21st century Hollywood’s throne
NBC News, Daniel Arkin (5/12/25)
Articles
Questions
- What are the similarities and differences between Netflix’ and YouTube’s business models? How close substitutes do you think they are?
- Do you think cinemas are a closer or more distant substitute to Netflix than YouTube?
- Which deal do you think raises the most competition concerns? What might be a possible remedy that could alleviate these concerns?
 The approach towards mergers remains the most controversial area of competition policy. Some argue that policy makers in both the UK and EU have been too easily persuaded by the arguments put forward by firms and so have allowed too many mergers to proceed. Others claim that the opposite is true and that merger policy has prohibited mergers that should have been allowed to proceed. This, then, has a negative impact on investment, innovation, productivity and growth.
In recent years there has been more specific criticism of merger policy in the UK. The government has indicated that it wants the Competition and Markets Authority (CMA) to be less interventionist and take a more pro-growth approach.
In February 2025, in response to this criticism, the CMA launched its new ‘4 Ps’ approach to merger policy: Pace, Predictability, Proportionality and Process. Various changes to the investigation process have been proposed in the past 12 months using this framework.
Pace. The time taken by the CMA to initially assess a merger before deciding whether a Phase 1 investigation is necessary (i.e. the pre-notification procedure) was reduced from 65 to 40 working days. Also, the target to complete straightforward Phase 1 investigations was reduced from 35 to 25 days.
Predictability. The proposed merger guidelines, published in October 2025, provide more detail on (a) what criteria will be used to measure market shares when applying the ‘share of supply test’ (this is where the combined UK market share of two merging businesses is at least 25%, provided one business has a UK turnover of at least £10 million), and (b) the factors that are likely to lead to the competition authorities concluding that one business has gained ‘material influence over another’. Businesses had complained that there was too much uncertainty about the way the share of supply test and material influence were applied. The CMA is also considering greater alignment with other international regulators over decision making rather than its previous policy of acting independently. All these measures should increase the predictability of the investigation process.
 Proportionality. Proportionality refers to the objective of addressing any competition issues in merger cases in a way that places the minimum burden on the businesses involved. To improve proportionality, the CMA has indicated that in future cases it will be more willing to use behavioural remedies – requiring firms to take or desist from certain actions. New draft guidelines identify more situations where the use of behavioural remedies may be appropriate. However, they also show that the CMA still views structural remedies (e.g. preventing the merger or requiring firms to demerge or to sell certain assets) as more effective in many situations. Another important measure to improve proportionality is the introduction of a new ‘wait and see’ approach to global mergers. The CMA will now wait to see if the actions taken by other competition authorities in global cases address any concerns in the UK market before deciding whether to launch a review.
Process. To improve the process, the CMA has announced plans to engage with businesses at a much earlier point in the process. For example, it has pledged to share its provisional thinking in the early stages of an investigation by implementing new ‘teach-in’ sessions and having more regular update meetings. Much earlier meetings that focus on possible remedies will also take place. This may make it possible for the CMA to assess the suitability of more complex remedies during a Phase 1 investigation rather than having to wait for a longer and more costly Phase 2 review. Phase 2 reviews will also no longer be managed by panels of independent experts. This role will now be carried out by the internal CMA board.
Some critics argue that the CMA has not fully considered the potential benefits of mergers in many cases. For example, a merger could (a) have procompetitive effects, known as rivalry enhancing efficiencies (REEs) and/or (b) benefits for consumers outside of the relevant market, known as relevant customer benefits (RCBs). In response to this criticism, the CMA is currently reassessing its approach to including evidence on REEs and RCBs.
The CMA is still currently consulting with interested parties about many of these proposed changes. It will be interesting to see what final decisions are made in the next couple of years.
Articles
- CMA consults on proposed changes to its merger remedies approach
CMA Press Release (15/10/25)
- New CMA proposals to drive growth, investment and business confidence
CMA Blog, Sarah Cardell (CMA Chief Executive) (13/2/25)
- Promoting competition and protecting consumers to drive growth and improve household prosperity
CMA Speech, Sarah Cardell (20/11/25)
- Steering the course: how the CMA is responding to the Government’s pro-growth agenda
Macfarlanes (21/2/25)
- 4Ps and 3 themes – An overview of the CMA’s merger remedies review
Hogan Lovells, Angus Coulter, Alice Wallace-Wright, Karman Gordon, and Denise Hotham-Kellner (1/4/25)
- CMA publishes updated guidance on UK merger procedure
Ashurst, Christopher Eberhardt, Emile Abdul-Wahab and Finlay Sadler-Wilson (11/11/25)
- Government ousts UK competition watchdog chair
BBC News, Simon Jack and Charlotte Edwards (21/1/25)
- UK competition watchdog drops Microsoft-OpenAI probe
BBC News, Imran Rahman-Jones (5/3/25)
- Does the government really know what it wants from the CMA?
The Guardian, Nils Pratley (13/2/25)
- This article is more than 9 months old ‘We must avoid a chilling effect’: the CMA chief on the UK’s pro-growth shift
The Guardian, John Collingridge (18/2/25)
- The CMA should be nudged on antitrust, not bullied
The Financial Times, John Gapper (6/2/25)
CMA documentation
Questions
- Of all the mergers considered by the CMA in 2024/25, find out what percentage were formally investigated. How many were blocked from taking place? Do you believe that this indicates that merger policy is too weak or too strong?
- What three criteria must be met for a business arrangement to be classed as a ‘relevant merger situation’ by the CMA?
- Identify some different methods that one business could use to gain material influence over the way another company operates.
- Outline the ‘turnover test’, the ‘share of supply test’ and the ‘hybrid test’.
- Discuss the potential advantages of using behavioural remedies as opposed to structural remedies in merger cases. Why has the CMA still preferred the use of structural remedies in most situations?
 In my previous blog post on this site, I examined how AI-powered pricing tools can act as a ‘double-edged sword’: offering efficiency gains, while also creating opportunities for collusion. I referred to one of the early examples of this, which was the case involving Trod Ltd and GB Eye, where two online poster and frame sellers on Amazon used pricing algorithms to monitor and adjust their prices. However, in this instance there was also an explicit agreement between the firms. As some commentators put it, it was ‘old wine in new bottles‘, meaning a fairly conventional cartel that was simply facilitated through digital tools.
Since then, algorithms have increasingly become part of everyday life and are now embedded in routine business practice.
Some of the effects may have a positive effect on competition. For example, algorithms can help to lower barriers to entry. In some markets, incumbents benefit from long-standing experience, while new firms face significant learning costs and are at a disadvantage. By reducing these learning costs and supporting entry, algorithms could contribute to making collusion harder to sustain.
On the other hand, algorithms could increase the likelihood of collusion. For example, individual algorithms used by competing firms may respond to market conditions in predictable ways, making it easier for firms to collude tacitly over time.
Algorithms can also improve the ability of firms to monitor each other’s prices. This is particularly relevant for multi-product firms. Traditionally, we might expect these markets to be less prone to collusion because co-ordinating across many products is complex. AI can overcome this complexity. In the Sainsbury’s/Asda merger case, for example, the Competition and Markets Authority suggested that the main barrier to reaching and monitoring a pricing agreement was the complexity of pricing across such a wide range of products. However, the CMA also suggested that technological advances could increase its ability to do so in the future.
The ‘hub-and-spoke’ model
 One of the other growing concerns is the ability of AI pricing algorithms to facilitate collusion by acting as a ‘hub’ in a ‘hub-and-spoke’ arrangement. In this type of collusion, competing firms (the ‘spokes’) need not communicate directly with one another. Instead, the ‘hub’ helps them to co-ordinate their actions.
While there have been only limited examples of an AI pricing algorithm acting as a hub in practice, what once seemed to be a largely theoretical concern has now become a live enforcement issue.
A very recent example is the RealPage case in the United States. The Department of Justice (DOJ) filed an antitrust lawsuit against RealPage Inc. in August 2024, alleging that RealPage, acting as the ‘hub’, facilitated collusion between landlords (the ‘spokes’).
RealPage provided pricing software to numerous landlords, including the largest landlord in the USA, which manages around 950 000 rental units across the country. These landlords would normally compete independently in setting rental prices, discounts and lease terms to win consumers. However, by feeding competitively sensitive information that would not usually be shared between rivals into RealPage’s system, the software generated pricing recommendations that, according to the DOJ, led to co-ordinated rent increases across competing apartment complexes.
I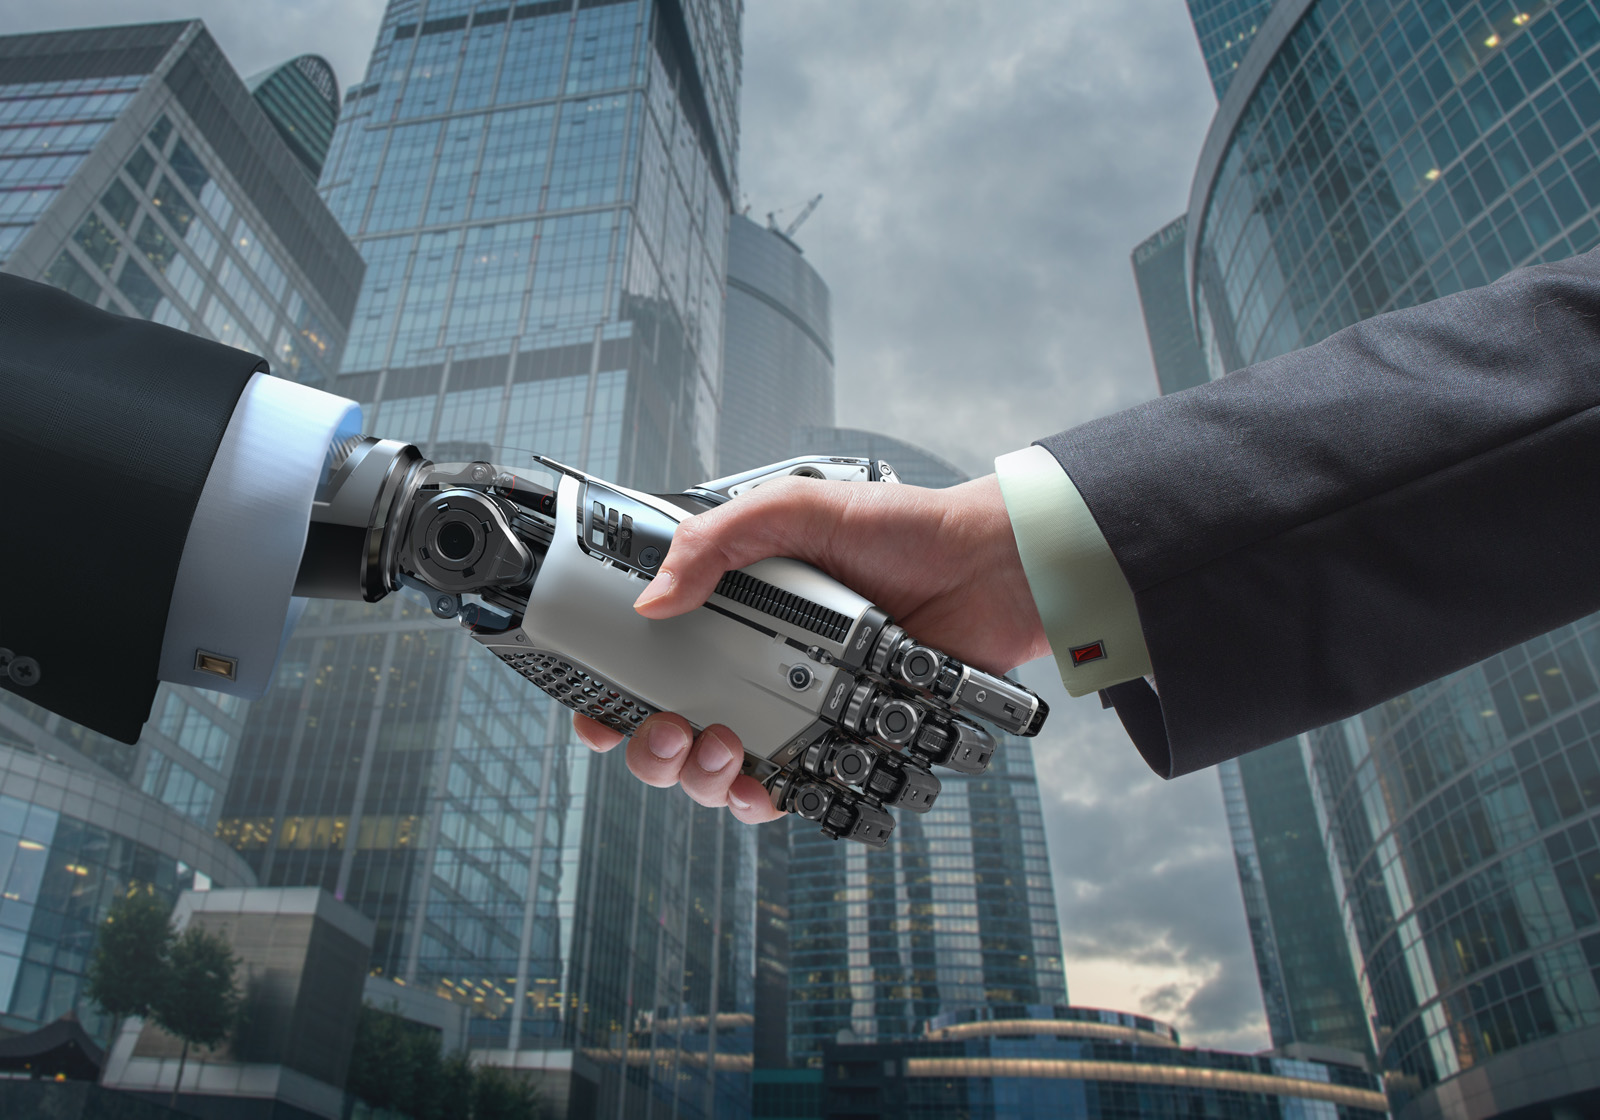 n the RealPage case, the authorities reported that they had access to internal documents and statements from the parties involved, which helped support their allegations. These included references within RealPage to helping landlords ‘avoid the race to the bottom’ and comments from a landlord describing the software as ‘classic price fixing’.
Evidence in these cases really matters because the standard of proof required to establish a hub-and-spoke arrangement is much higher than for traditional cases of explicit collusion. This is because it can be difficult to distinguish between legitimate and anti-competitive communication between retailers and suppliers. Also, proving ‘anti-competitive intent’ is inherently challenging.
Other competition authorities around the world are also turning their attention to these issues. For example, the European Commission recently announced that a number of investigations into algorithmic pricing are underway, signalling a clear shift toward more active scrutiny. As technology continues to advance, it is clear that algorithmic pricing will remain an area where both firms and authorities must move and adapt quickly.
Articles
Questions
- In what ways does the RealPage case differ from the earlier Trod Ltd and GB Eye Ltd case? Consider the roles played by the firms, the nature of the alleged co-ordination, and the extent to which pricing algorithms were used to facilitate the conduct.
- How might the use of pricing algorithms affect the likelihood of firms colluding, either explicitly or tacitly? Consider ways that algorithms may make collusion easier to sustain but also ways in which they may reduce its likelihood.
- Should firms be held liable for anti-competitive outcomes produced by algorithms that ‘self-learn’, even if they did not intend those outcomes? Explain why or why not.
 Following the controversary over the sale of tickets for popular live events such as Taylor Swift’s Eras tour and the Oasis Live ’25 Tour, the government launched a consultation exercise in January 2025 on the resale of tickets. Titled, ‘putting fans first’, the exercise sought the views of individuals and organisations on a range of policy proposals. One of these was the implementation of a cap on the resale price of tickets.
The government is not only considering whether to implement a cap but also the level at which it might be set. The following question was included in the consultation exercise.
What is the maximum uplift that you think should be applied if ticket resales were to be subject to a price cap? Please state the reason for your selection.
• no uplift at all
• 10% or less
• between 10 and 20%
• between 20 and 30%
• other – please state
Some platforms such as Twickets and Ticketswap already cap resale prices on their platforms at between 5 and 10 per cent above the face value of the ticket. They are, therefore, less likely to be affected by any new price regulation unless the ‘no uplift at all’ option is chosen. On other platforms, such as Viagogo and Stubhub, resellers are free to list tickets at whatever price they choose. This is often referred to as the uncapped market, and tickets for the Oasis tour with a face value of £150 were listed on these websites for £14 000. The implementation of a price cap is likely to have a big impact on this part of the resale market. The chief executive of StubHub stated in June 2025 that the business would probably have to exit the UK if a cap was introduced.
 Although many fans dislike the uncapped secondary ticketing market, most economists take a more positive view. They see them as a way of facilitating mutually beneficial trade and helping to reallocate tickets to those with the highest willingness to pay. This reduces levels of allocative inefficiency/deadweight welfare loss in the market.
Economists also tend to argue against the use of price controls in competitive markets because of their negative impact on supply. If price controls reduce the available returns to sellers, they have an incentive to do something else with their time/resources i.e. switch to supplying other goods and services in markets not subject to price controls. This reduces supply in the regulated market and so could have a negative impact on consumer surplus.
What are the issues with the secondary market?
 Given the benefits outlined by economists of having an uncapped secondary ticketing, why is the government considering the implementation of a price cap? One potential issue of having an uncapped secondary ticketing market is that developments in technology make it easier for professional resellers to buy very large quantities of tickets. This makes it increasingly difficult for fans who want to attend the event from being able to purchase a ticket.
Reports also suggest that professional resellers use illegal methods to both mass purchase and resell tickets. For example, to overcome any limits on sales imposed by the sellers in the primary market, some use automated software, fake IDs and multiple credit cards. Two people convicted of fraudulent trading in 2024 were found to have bought 47 000 tickets over a 212-year period, using 127 names and 187 different e-mail addresses.
Some resellers have also acted in ways that do not comply with consumer law when advertising tickets for sale. For example, not providing information such as the ticket number and other details about where the seat is located i.e. the block/area and row.
These rent seeking activities by professional resellers could outweigh the positive impact of uncapped secondary market on allocative efficiency.
Implementing a resale price cap would reduce the incentives for professional resellers to purchase large quantities of tickets and engage in these rent-seeking activities. However, in the consultation document the government recognises that the implementation of a resale price cap would be a ‘significant and complex intervention’.
An important implementation issue
To calculate the resale price cap for any live event, the original price of the ticket in the primary market needs to be known. This raises an interesting question – should the cap apply to the initial face value of the ticket or the total price the customer pays?
The face value of the ticket may only represent a proportion of the actual cost of buying a ticket because of the widespread use of drip pricing. This is the practice of applying additional fees as the consumer proceeds through the online purchasing process. These fees can sometimes add around 25 per cent and more to the price of a ticket. In the consultation document, the government suggested that the cap should apply to the face value of the ticket plus all compulsory fees.
One issue raised in the response to the consultation by the Competition and Markets Authority is that these fees are not always made clear by sellers in the primary market in a clear and transparent way. Therefore, for the policy to be effective, primary market sellers would have to make information on both ticket prices and any fees clearly and easily available. Recent changes to the law that prohibit drip pricing might help to address this issue.
The potential impact of a resale price cap on fraud
 To avoid the price cap, there is a danger that increasing numbers of buyers and sellers stop using capped secondary ticket platforms, where activity is easier to observe/regulate, and switch to other non-specialist platforms where detection of illegal behaviour and enforcement of consumer law is more difficult. Examples of non-specialist platforms where sales might increasingly take place include Facebook Marketplace, Instagram Shop, X (formerly Twitter) and internet forums. With lower levels of consumer protection and the greater difficulty of detecting illegal behaviour, sales via these non-specialist platforms are more vulnerable to scams and fraud.
When referring to the impact of a resale price cap, the chief executive of StubHub argued that:
It will have a massive negative impact on consumers. It’s not like the demand is going to go away, it’s just going to move somewhere else, and that somewhere else is going to be the black market [where] consumers aren’t protected.
To test the hypothesis that price controls lead to greater incidences of fraud, one study used polling data to compare ticket fraud rates in the UK with Victoria, Australia and Ireland. In 2009, the state government of Victoria made it illegal for tickets to be resold for more than 10 per cent of their face, while the Irish government introduced the Sale of Ticket Act in 2021 that prohibited the resale of tickets above their original price. The study found that the proportion of respondents who reported being victims of ticket fraud over the previous two years was around four times higher in Victoria and Ireland than the UK. The most common sales channel where consumers experienced ticket fraud in all three countries were social media platforms.
Another example of the potential impact of the price cap in Ireland on fraud relates to the first ever regular-season NFL game that is being played in Dublin on 28 September 2025 between the Pittsburgh Steelers and the Minnesota Vikings. The online bank, Revolut, reported an 80 per cent increase in the number of ticket scams when tickets for this game went on sale.
In response to the consultation exercise, the Competition and Markets Authority backed the implementation of a resale price. It will be interesting to see if the government goes through with the measure in the next few months.
Consultation
Articles
Blogs on this site
Questions
- Why might event organisers set ticket prices below the market clearing rate? Illustrate the impact of setting prices below market clearing rates on consumer, producer and total surplus in the primary market for tickets.
- Using a demand and supply diagram, explain how the uncapped secondary ticket market could reduce deadweight welfare loss. Discuss any assumptions you have made about the allocation of tickets among potential buyers in the primary market (i.e. sorting).
- Is it possible for professional resellers to continue making a profit if tickets are sold at market clearing rates in the primary market? Explain your answer.
- Under what circumstances would a maximum price set below the market clearing rate in a competitive market have a negative impact on consumer surplus? Draw a diagram to illustrate your answer.
- Using examples, explain what is meant by ‘rent seeking’ in economic theory.
Outline some of the recent updates to the law on pricing information that businesses must show customers.
- What policies, other than a resale price cap, could the government introduce to try to address some of the issues with the ticketing market for live events?
 In a blog in October 2024, we looked at global uncertainty and how it can be captured in a World Uncertainty Index. The blog stated that ‘We continue to live through incredibly turbulent times. In the past decade or so we have experienced a global financial crisis, a global health emergency, seen the UK’s departure from the European Union, and witnessed increasing levels of geopolitical tension and conflict’.
Since then, Donald Trump has been elected for a second term and has introduced sweeping tariffs. What is more, the tariffs announced on so-called ‘Liberation Day‘ have not remained fixed, but have fluctuated with negotiations and threatened retaliation. The resulting uncertainty makes it very hard for businesses to plan and many have been unwilling to commit to investment decisions. The uncertainty has been compounded by geopolitical events, such as the continuing war in Ukraine, the war in Gaza and the June 13 Israeli attack on Iran.
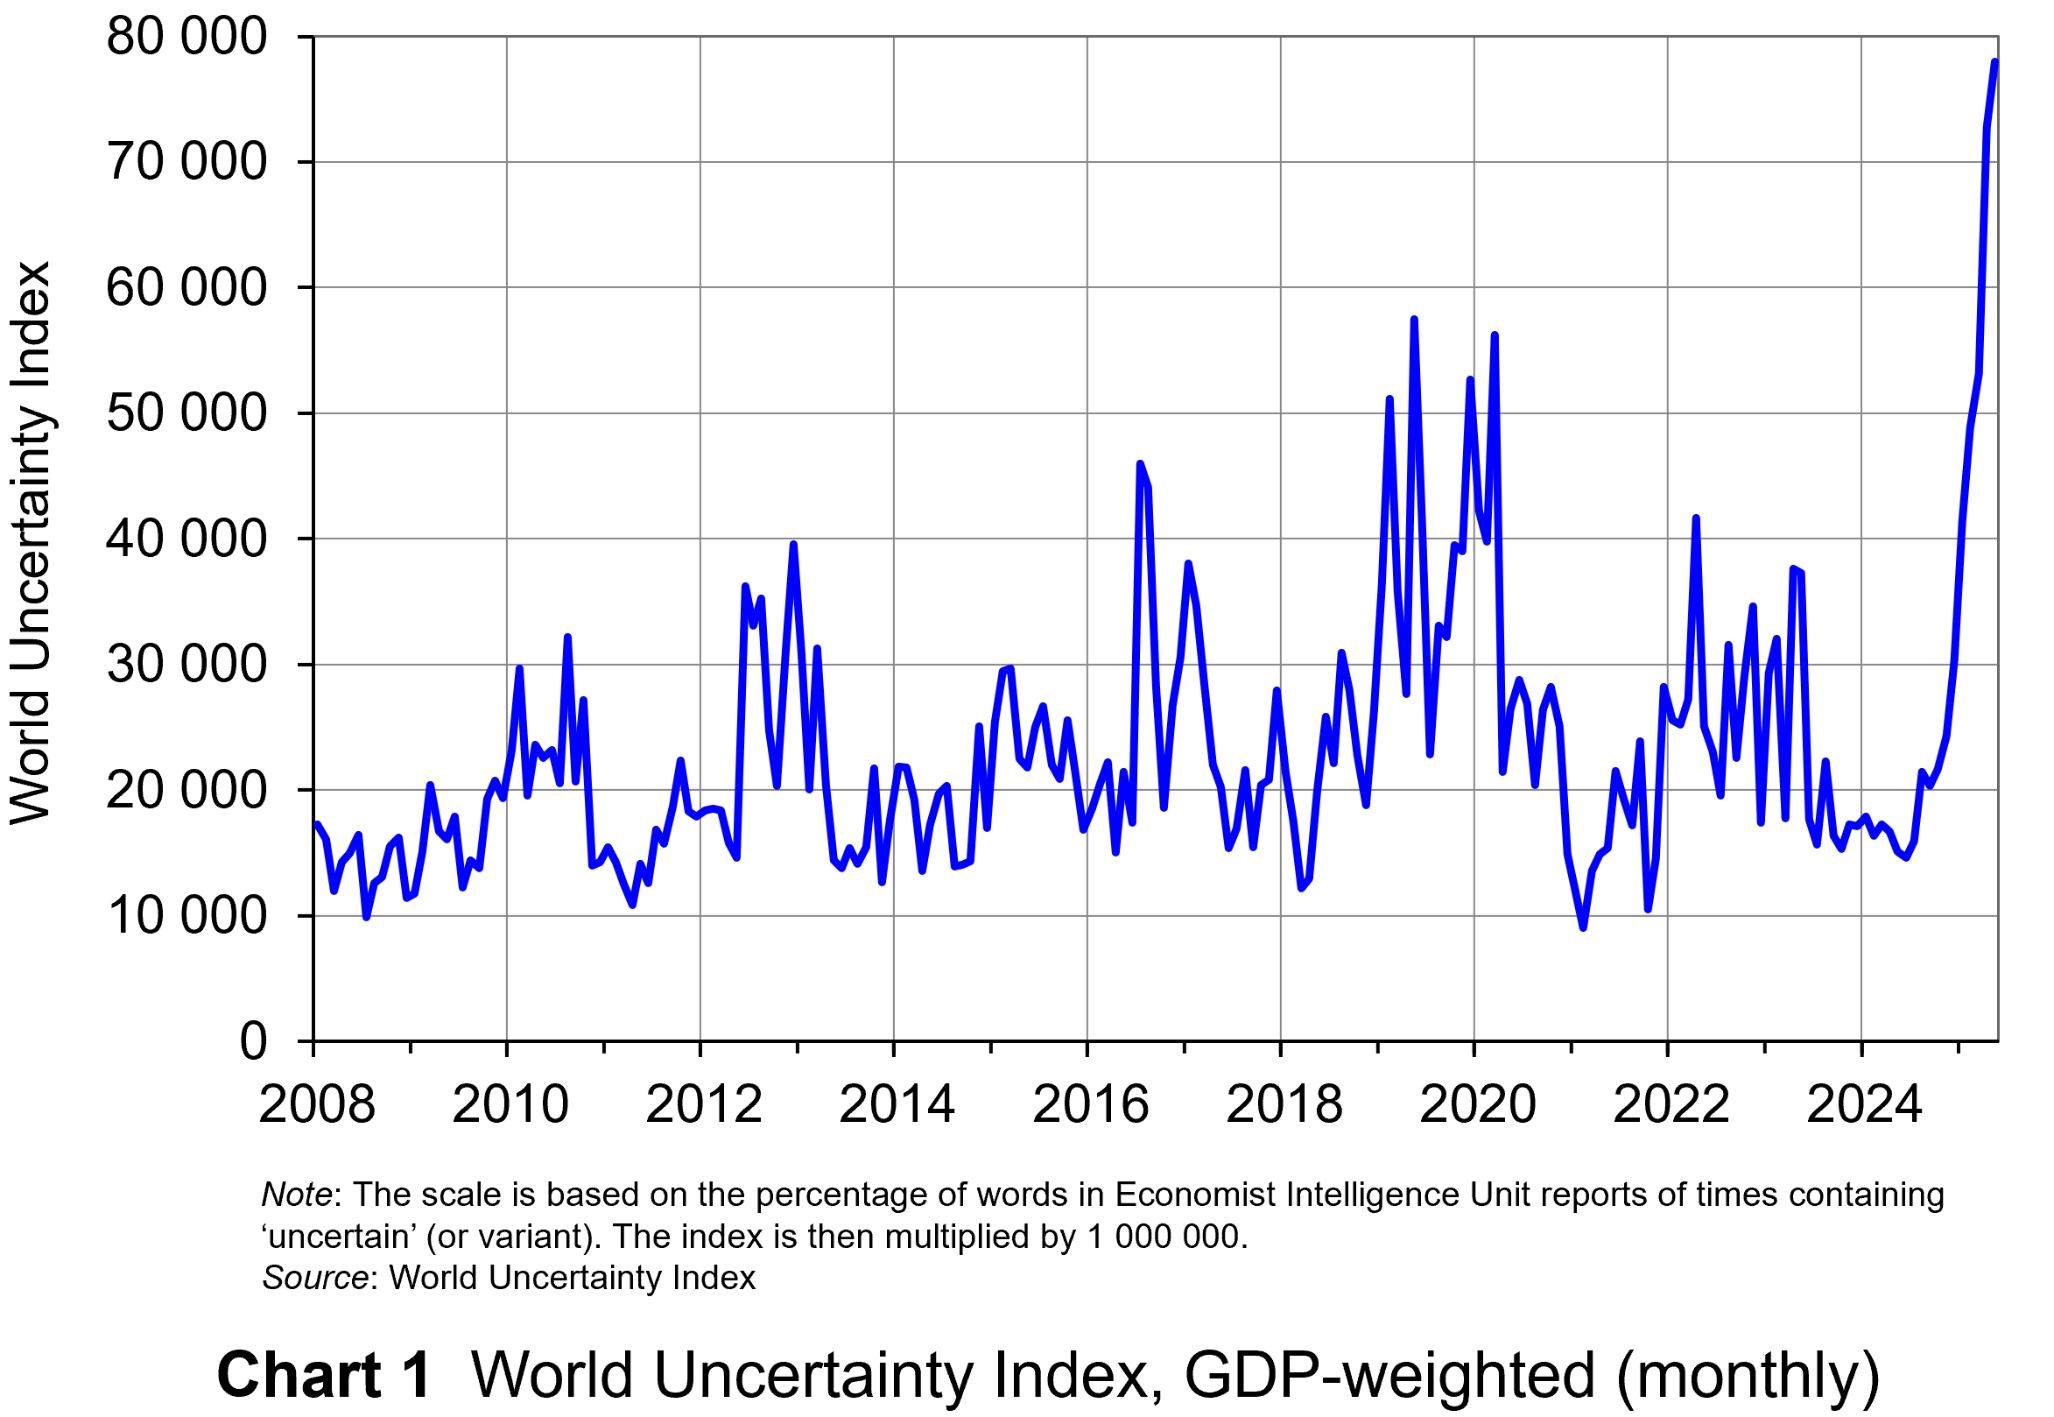 The World Uncertainty Index (WUI) tracks uncertainty around the world by applying a form of text mining known as ‘term frequency’ to the country reports produced by the Economist Intelligence Unit (EIU). The words searched for are ‘uncertain’, ‘uncertainty’ and ‘uncertainties’ and the number of times they occur as percentage of the total words is recorded. To produce the WUI this figure is then multiplied by 1m. A higher WUI number indicates a greater level of uncertainty.
The monthly global average WUI is shown in Chart 1 (click here for a PowerPoint). It is based on 71 countries. Since 2008 the WUI has averaged a little over 23 000: i.e. 2.3 per cent of the text in EIU reports contains the word ‘uncertainty’ or a close variant. In May 2025, it was almost 79 000 – the highest since the index was first complied in 2008. The previous highest was in March 2020, at the start of the COVID-19 outbreak, when the index rose to just over 56 000.
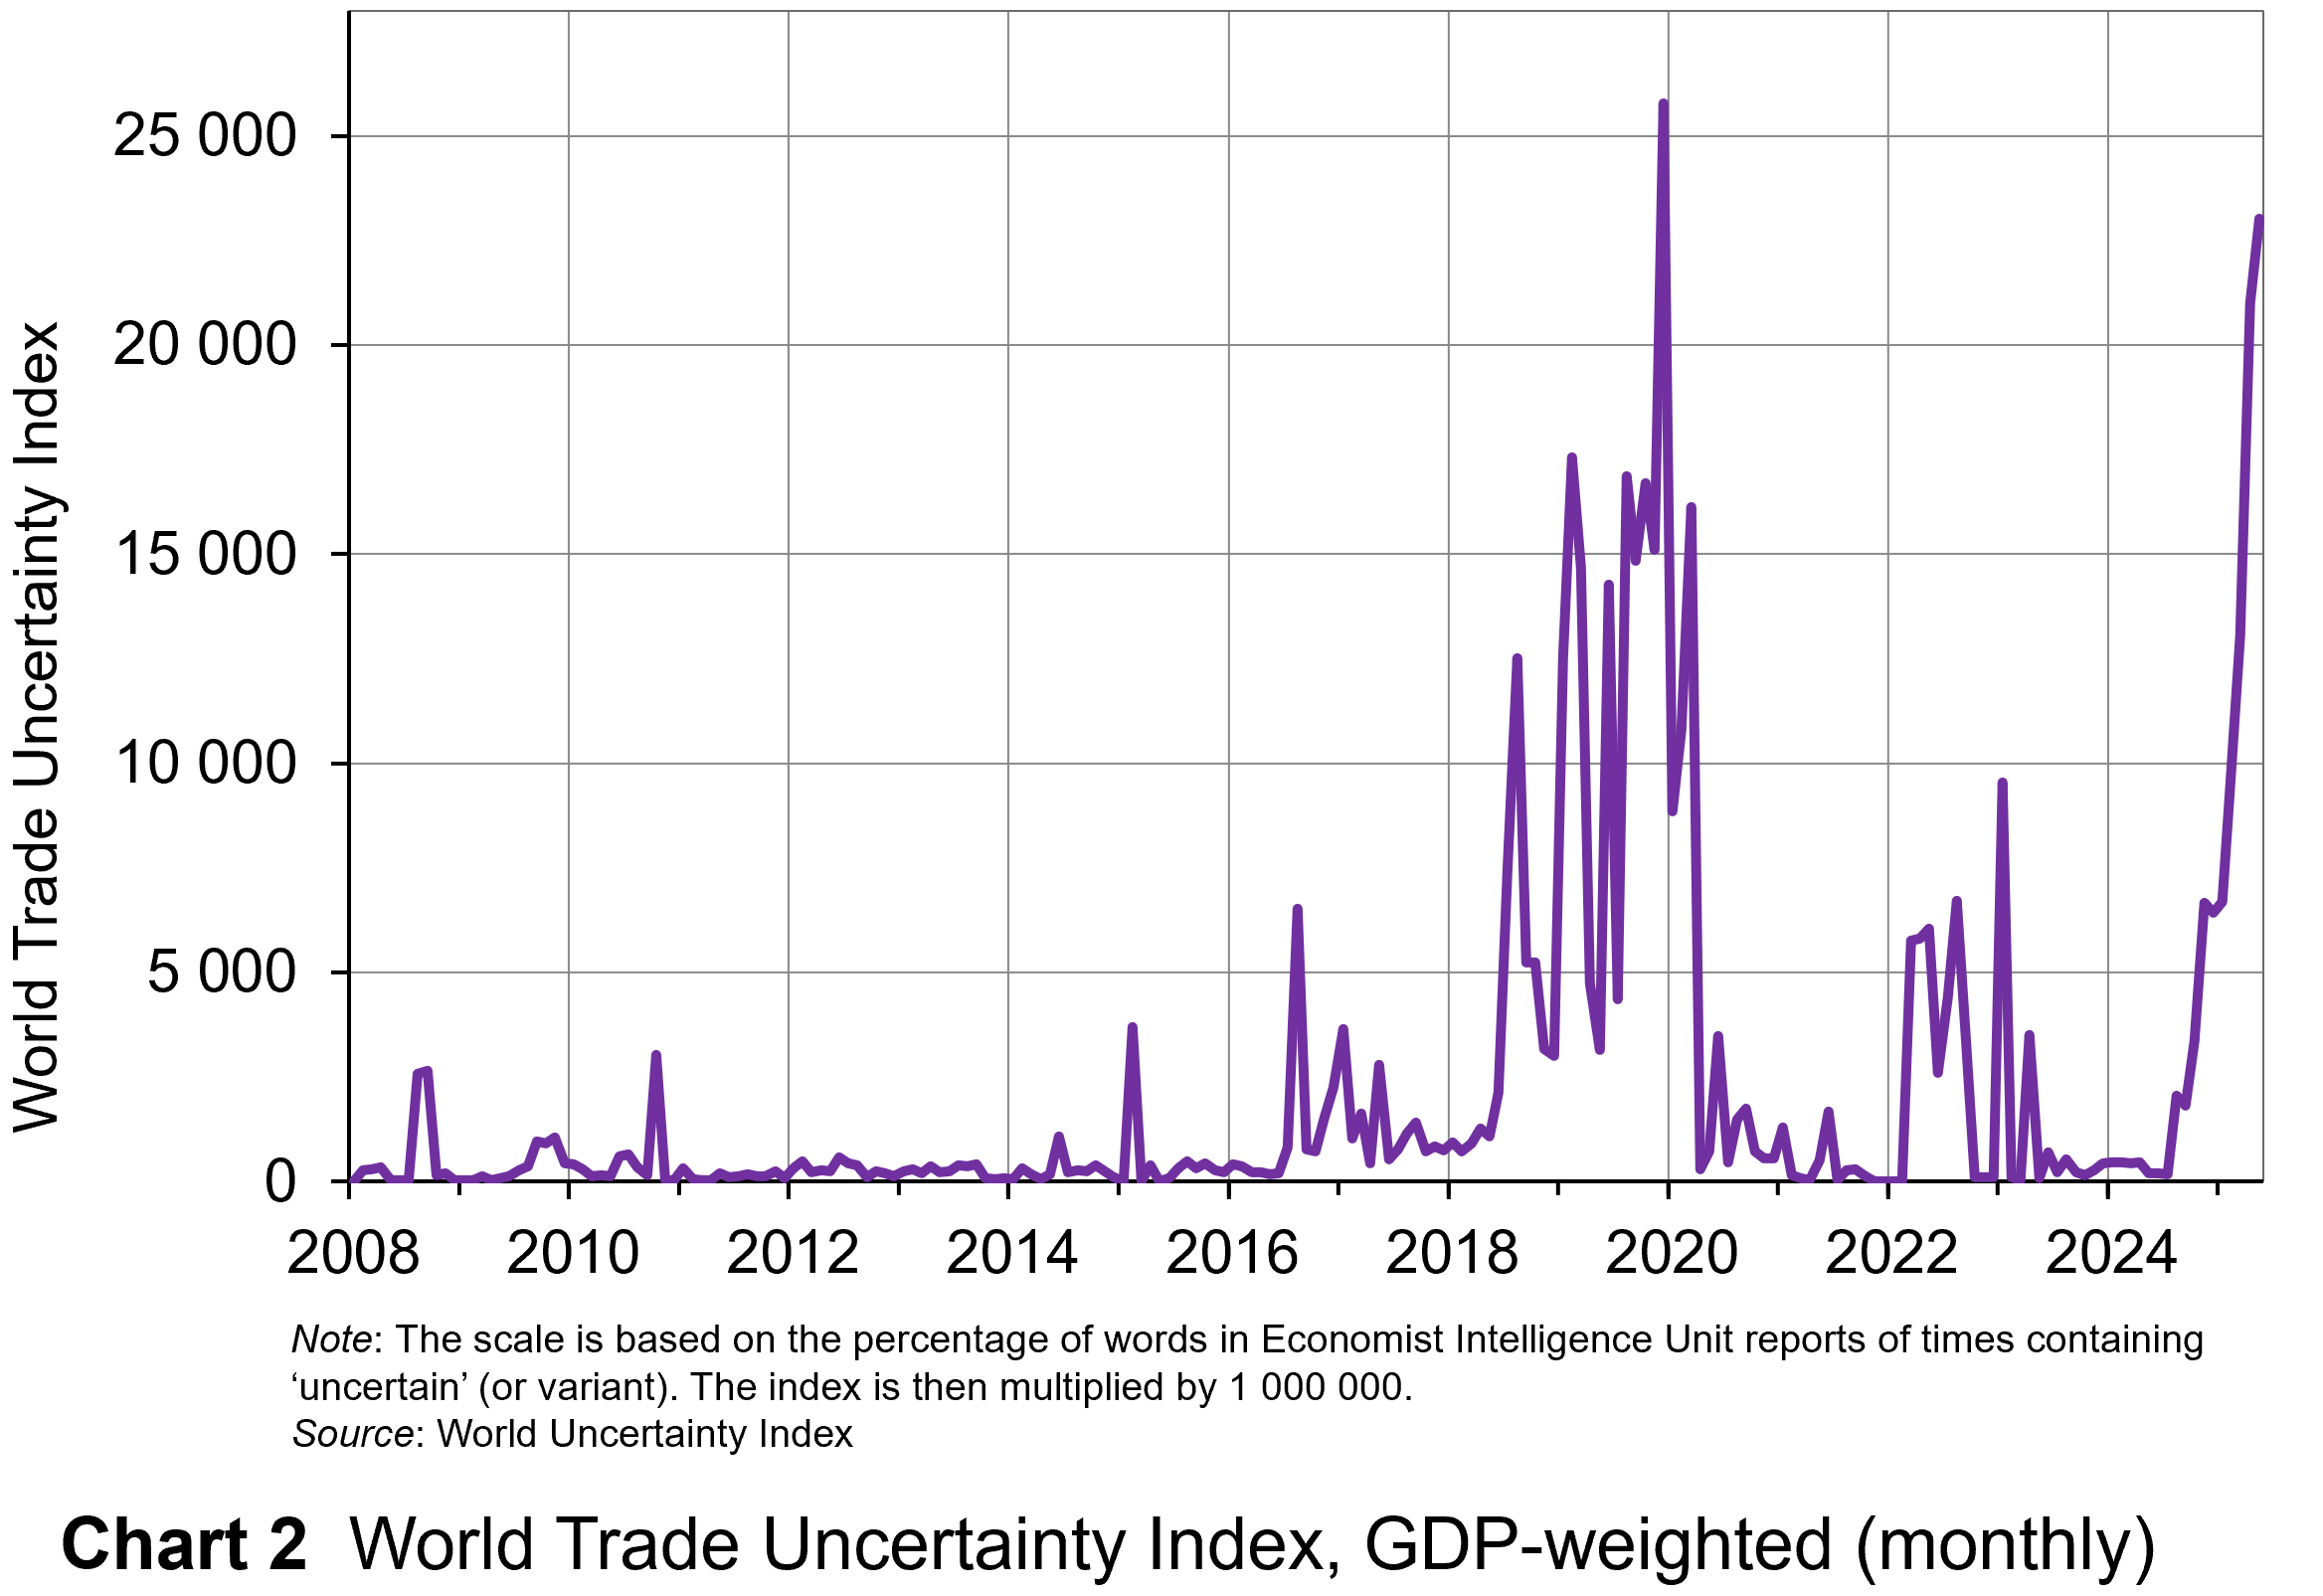 The second chart shows the World Trade Uncertainty Index (WTUI), published on the same site as the WUI (click here for a PowerPoint). The method adopted in its construction therefore mirrors that for the WUI but counts the number of times in EIU country reports ‘uncertainty’ is mentioned within proximity to a word related to trade, such as ‘protectionism’, ‘NAFTA’, ‘tariff’, ‘trade’, ‘UNCTAD’ or ‘WTO.’
The chart shows that in May 2025, the WTUI had risen to just over 23 000 – the second highest since December 2019, when President Trump imposed a new round of tariffs on Chinese imports and announced that he would restore steel tariffs on Brazil and Argentina. Since 2008, the WTUI has averaged just 2228.
It remains to be seen whether more stability in trade relations and geopolitics will allow WUI and WUTI to decline once more, or whether greater instability will simply lead to greater uncertainty, with damaging consequences for investment and also for consumption and employment.
Articles
- IMF World Economic Outlook: economic uncertainty is now higher than it ever was during COVID
The Conversation, Sergi Basco (23/4/25)
- Economic uncertainty hits new high
McKinsey, Sven Smit et al. (29/5/25)
- Trade tensions and rising uncertainty drag global economy towards recession
UNCTAD News (25/4/25)
- IMF Warns Global Economic Uncertainty Surpasses Pandemic Levels
The Global Treasurer (24/4/25)
- Britons ‘hoarding cash amid economic uncertainty and fear of outages’
The Guardian, Phillip Inman (10/6/25)
- America’s Brexit Phase
Foreign Affairs, Jonathan Haskel and Matthew J. Slaughter (10/6/25)
- Goldman Sachs’ CEO on the ‘Big, Beautiful Bill,’ Trump’s Tariffs and Economic Volatility
Politico, Sam Sutton (13/6/25)
- The Countries Where Economic Uncertainty Is Rising Fastest
24/7 Wall St., Evan Comen (9/6/25)
- Trump’s tariffs have finally kicked in, so what happens next?
The Conversation, Maha Rafi Atal (8/8/25)
Uncertainty Indices
Questions
- Explain what is meant by ‘text mining’. What are its strengths and weaknesses in assessing business, consumer and trade uncertainty?
- Explain how the UK Monthly EPU Index is derived.
- Why has uncertainty increased so dramatically since the start of 2025?
- Compare indices based on text mining with confidence indices.
- Plot consumer and business/industry confidence indicators for the past 24 months, using EC data. Do they correspond with the WUI?
- How may uncertainty affect consumers’ decisions?
