 The latest preliminary GDP estimates for 2014 Q1 suggest that the economy’s output (real GDP) expanded by 0.8 per cent following on the back of a 0.7 per cent increase in 2013 Q4. Growth was observed in three of the four main industrial sectors: 0.9% in services, 0.8% in production and 0.3% in construction. In contrast, output decreased by 0.7% in agriculture. The total output of the economy is now just 0.6 per cent below its 2008 Q1 peak with the output of the service sector now 2.0 per cent higher.
Data on growth need to be set in the context of the inherent volatility of economies and in this case in the context of 2008/9 recession. Then, output fall by some 7.2 per cent. UK output peaked in 2008 Q1 (£392.786 billion at 2010 prices). There then followed 6 quarters during which output declined.
Output declined again in 2010 Q4 (-0.2% growth), in 2011 Q4 (-0.1% growth), in 2012 Q2 (-0.4%) and in 2012 Q4 (-0.2%). A double-dip recession was only narrowly avoided with growth recorded at zero on 2012 Q1. The latest ONS numbers show the economy grew by 0.8 per cent in 2013 Q2 (to £381.318 billion at 2010 prices), by 0.8 per cent in 2013 Q3 (to £384.533 billion at 2010 prices), by 0.7 per cent in 2013 Q4 (to £387.138 billion at 2010 prices) and by 0.8 per cent in 2014 Q1 (to £390.235 billion at 2010 prices). Compared with 2013 Q1, the output of the UK economy in 2014 Q1 is 3.1 per cent higher.
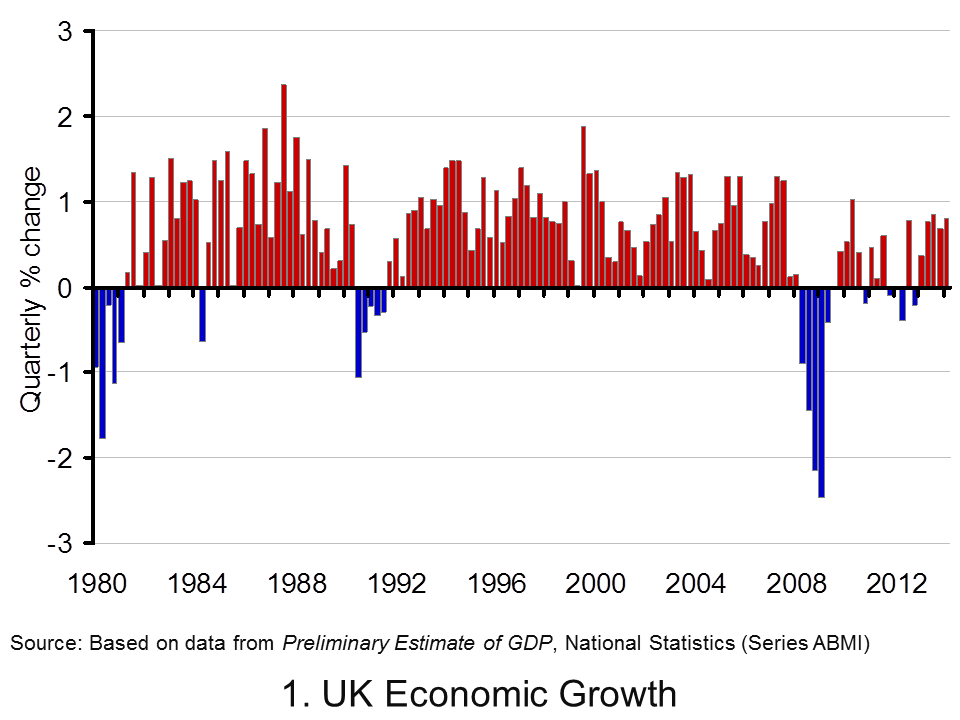 Chart 1 helps to put the recent growth numbers into an historical context. It shows the quarterly change in real GDP since the 1980s. We can see the 5-quarter recession that commenced in 1980 Q1 when output shrunk by 4.6 per cent, the 5-quarter recession that commenced in 1990 Q3 when output shrank by 2.4 per cent and the 6-quarter recession that commenced in 2008 Q2 when output shrank by 7.2 per cent. (Click here to download the chart to PowerPoint.)
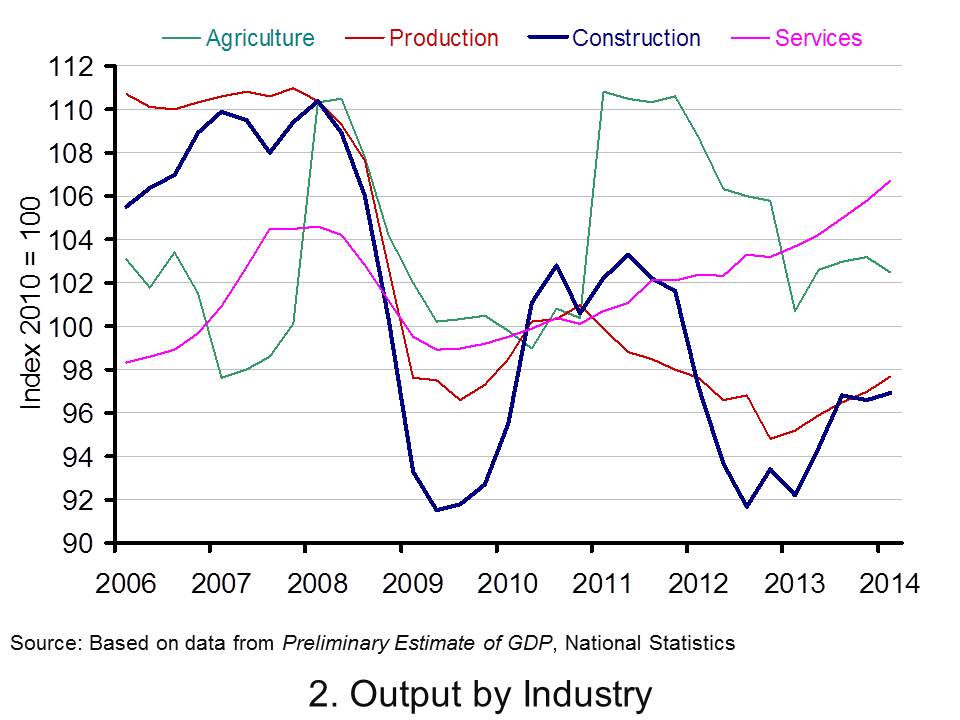 Chart 2 scratches a little below the surface by looking at output by the 4 principal industrial types. The interesting finding is that the output of the service sector has now risen above its 2008 Q1 peak. In 2014 Q1, service sector output was 2.0 per cent higher than 2008 Q1. The fact that total output remains 0.6 per cent lower can be explained by the lop-sided industrial recovery. Output in agriculture, forestry and fisheries remains 7.1 per cent lower, production (including manufacturing) 11.5 per cent lower and construction 12.2 per cent lower. (Click here to dowload the chart to Powerpoint.)
Data
Preliminary Estimate of GDP – Time Series Dataset Q1 2014 Office for National StatisticsGross Domestic Product Preliminary Estimate, Q1 2014 Office for National Statistics
Articles
UK GDP ‘close to pre-crisis level’ says NIESR BBC News (9/5/14)
UK ‘great recession’ almost over, says thinktank Guardian, Katie Allen (9/5/14)
UK economy tops its pre-crash high point, says NIESR Telegraph, Szu Ping Chan (9/5/14)
UK economy grew by 0.8% in first three months of 2014 Guardian, Katie Allen and Angela Monaghan (29/4/14)
Manufacturing is GDP star performer BBC News, Robert Peston (29/4/14).
Questions
- What is the difference between nominal and real GDP? Which of these helps to track changes in economic output?
- Looking at Chart 1 above, summarise the key patterns in real GDP since the 1980s.
- What is a recession? What is a double-dip recession?
- What are some of the problems with the traditional definition of a recession?
- Can a recession occur if nominal GDP is actually rising? Explain your answer.
- What factors lead to economic growth being so variable?
- What factors might explain the very different patterns seen since the late 2000s in the volume of output of the 4 main industrial sectors?
- Produce a short briefing paper exploring the prospects for economic growth in the UK over the next 12 to 18 months.
- Explain the arguments for and against using GDP as a measure of a country’s economic well-being.
- Analyse the role that the financial system might play in contributing to or alleviating the business cycle.
 On my commute to work on the 6th May, I happened to listen to a programme on BBC radio 4, which provided some fascinating discussion on a variety of economic issues. Technological change is constant and unstoppable and the consequences of it are likely to be both good and bad.
In this programme some top economists, including Joseph Stiglitz offer their analysis of the impact of technology and how the future might look, by considering a range of factors, such as youth unemployment, the productivity of labour, education, pensions and inequality. The benefits of new technology can be seen as endless, but the impact on inequality and how the benefits of technology are being distributed is a concern for many people. The best introduction to the programme and its content is simply to reproduce the description provided by BBC radio 4.
The baby boom generation came of age when it was accepted knowledge that innovation and productivity would always lead to higher standards of living. The generations which followed assumed this truth would continue into the future indefinitely. With the crash of 2008 the upward mobility the middle classes assumed was their right evaporated, and it is unlikely to return.
Martin Wolf, chief economics commentator of the Financial Times, asks how the work force of the future will be changed by the advancements of technologies. How should governments respond to a jobs market which is hollowing out opportunities for traditional educated professions and how will rewards for innovation and income for labour be distributed without creating a society plagued by endemic inequality?
We will speak with optimists and pessimists on both sides of the argument to find out how the repercussions of these changes will affect the way we all live now and well into the future.
It is well worth listening to and provides some interesting insights as to what the future might look like, as the inevitable technological change continues. The link for the programme is below.
 The future is not what it used to be BBC Radio 4 (6/5/14)
Questions
- What are the expected costs and benefits of technological change?
- Which factors are discussed as being the main obstacles to upwards mobility? Why have these become more prevalent in recent decades?
- Using a diagram, explain how technology can improve economic growth. To what extent is the multiplier effect important here?
- How is technology expected to affect the labour market? Use a diagram to help your explanation and make sure you consider both sides of the argument.
- What is meant by the idea that the benefits of new technology are likely to be felt in the long run?
- How important is education in creating equal opportunities?
- What is meant by secular stagnation? Is it seen as being a problem?
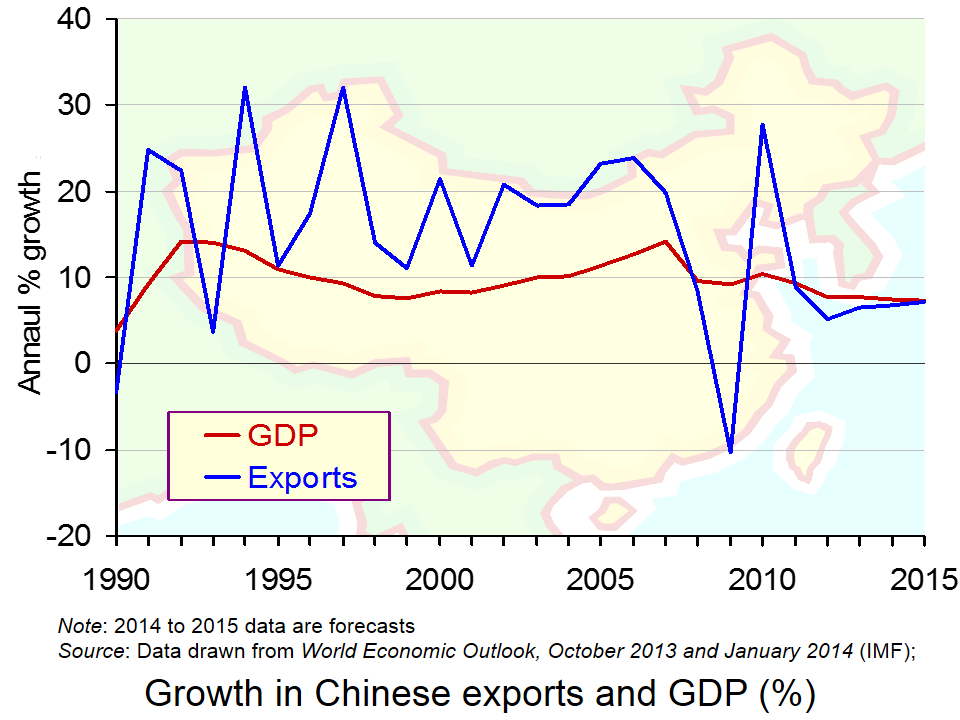 The growth of China over the past decade has been quite phenomenal, with figures recorded in double-digits. However, in the aftermath of the recession, growth has declined to around 7% – much higher than Western economies are used to, but significantly below the ‘norm’ for China. (Click here for a PowerPoint of the chart.)
The growth target for this year is 7.5%, but there appear to be some concerns about China’s ability to reach this figure and this has been emphasised by a recent Chinese policy.
A mini-stimulus package has been put in place, with the objective of meeting the 7.5% growth target. Government expenditure is a key component of aggregate demand and when other components of AD are lower than expected, boosting ‘G’ can be a solution. However, it’s not something that the Chinese government has had to do in recent years and the fact that this stimulus package has been put in place has brought doubts over China’s economic performance to the forefront , but has confirmed its commitment to growth. Mizuho economist, Shen Jianguang, said:
It’s very obvious that the leaders feel the need to stabilise growth…Overall, the 7.5 per cent growth target means that the government still cares a lot about economic growth.
Data suggest that growth in China is relatively weak and there are concerns that the growth target will be missed, hence the stimulus package. In the aftermath of the 2008 financial crisis, there was a large stimulus package in place in China. This latest investment by the government is in no way comparable to the size of the 2008 package, but instead will be on a smaller and more specific scale. Mark Williams of Capital Economics said:
It’s a bit of a rerun of what we saw last year – something less than a stimulus package and more of piecemeal measures to ensure they reach their growth target.
It is the construction of public housing and railways that will be the main areas of investment this time round. A sum of $120–180bn per year will be available for railway construction and $161bn for social housing, and tax breaks are being extended for small businesses.
The 2008 stimulus package saw debt increase to some 200% of GDP, which did cause growing concerns about the reliance on debt. However, this latest package will be financed through the issue of bonds, which is much more similar to how market economies finance spending.
The fact that the government has had to intervene with such a stimulus package is, however, causing growing concerns about the level of debt and the future of this fast growing economy, though the new method of financing is certainly seen as progress.
It should be noted that a decline in growth for China is not only concerning for China itself, but is also likely to have adverse consequences other countries. In the increasingly interdependent world that we live in, Western countries rely on foreign consumers purchasing their exports, and in recent years it has been Chinese consumers that have been a key component of demand. However, a decline in growth may also create some benefits – resources may not be used up as quickly and prices of raw materials and oil in particular may remain lower.
It is certainly too early for alarm bells, but the future of China’s growth is less certain than it was a decade ago. The following articles consider this issue.
China’s new mini-stimulus offers signs of worry and progress BBC News, Linda Yueh (3/4/14)
China puts railways and houses at hear of new stimulus measures The Guardian (3/4/14)
China unveils mini stimulus to to boost slowing economy The Telegraph (3/4/14)
China stimulus puts new focus on growth target Wall Street Journal, Bob Davis and Michael Arnold (3/4/14)
China embarks on ‘mini’ stimulus programme to kick-start economy Independent, Russell Lynch (3/4/14)
China takes first step to steady economic growth Reuters (2/4/14)
China unveils fresh stimulus The Autstralian (3/4/14)
China’s reformers can triumph again, if they follow the right route The Guardian, Joseph Stiglitz (2/4/14)
Questions
- How has Chinese growth reached double-digits? Which factors are responsible for such high growth?
- The BBC News article suggests that the stimulus package is cause for concerns but also shows progress. How can it do both?
- Using a diagram, illustrate how a stimulus package can boost economic growth.
- What are the advantages and disadvantages of high rates of growth for (a) China and (b) Western economies?
- Why does the method of financing growth matter?
- Railway and housing construction have been targeted to receive additional finance. Why do you think these sectors have been targeted?
 While much of the UK is struggling to recover from recession, the London economy is growing strongly. This is reflected in strong investment, a growth in jobs and rapidly rising house prices.
There are considerable external economies of scale for businesses locating in London. There is a pool of trained labour and complementary companies providing inputs and services are located in close proximity. Firms create positive externalities to the benefit of other firms in the same industry or allied industries.
London is a magnet for entrepreneurs and highly qualified people. Innovative ideas and business opportunities flow from both business dealings and social interactions. As Boris Johnson says in the podcast, “It’s like a cyclotron on bright people… People who meet each other and spark off each other, and that’s when you get the explosion of innovation.”
 Then there is a regional multiplier effect. As the London economy grows, so people move to London, thereby increasing consumption and stimulating further production and further employment. Firms may choose to relocate to London to take advantage of its buoyant economy. There is also an accelerator effect as a booming London encourages increased investment in the capital, further stimulating economic growth.
But the movement of labour and capital to London can dampen recovery in other parts of the economy and create a growing divide between London and other parts of the UK, such as the north of England.
The podcast examines ‘agglomeration‘ in London and how company success breeds success of other companies. It also looks at some of the downsides.
Podcast
Boris Johnson: London is cyclotron on bright people BBC Today Programme, Evan Davis (3/3/14)
Articles
London will always win over the rest of the UK The Telegraph, Alwyn Turner (2/3/14)
Evan Davis’s Mind The Gap – the view from Manchester The Guardian, Helen Pidd (4/3/14)
London incubating a new economy London Evening Standard, Phil Cooper (Founder of Kippsy.com) (10/2/14)
Reports and data
London Analysis, Small and Large Firms in London, 2001 to 2012 ONS (8/8/13)
Regional Labour Market Statistics, February 2014 ONS (19/2/14)
London Indicators from Labour Market Statistics (11 Excel worksheets) ONS (19/2/14)
Annual Business Survey, 2011 Regional Results ONS (25/7/13)
Economies of agglomeration Wikipedia
Questions
- Distinguish between internal and external economies of scale.
- Why is London such an attractive location for companies?
- Are there any external diseconomies of scale from locating in London?
- In what ways does the expansion of London (a) help and (b) hinder growth in the rest of the UK?
- Examine the labour statistics (in the links above) for London and the rest of the UK and describe and explain the differences.
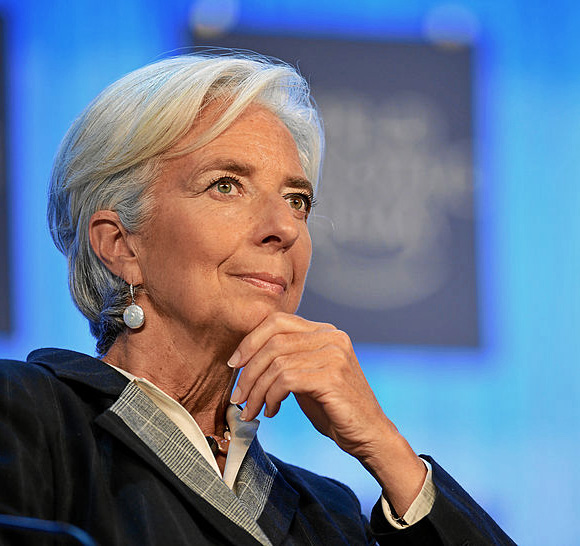
 Christine Lagarde, managing director of the IMF, has warned of the danger of deflation in the eurozone. She also spoke of the risks of a slowdown in the developing world as the Fed tapers off its quantitative easing programme – a programme that has provided a boost to many emerging economies.
Speaking at the World Economic Forum, in the Swiss Alps, she did acknowledge signs of recovery across the world, but generally her speech focused on the risks to economic growth.
Some of these risks are old, such as a lack of fundamental bank reform and a re-emergence of risky behaviour by banks. Banks have taken steps towards recapitalisation, and the Basel III rules are beginning to provide greater capital buffers. But many economists believe that the reforms do not go far enough and that banks are once again beginning to behave too recklessly.
 Some of the risks are new, or old ones resurfacing in a new form. In particular, the eurozone, with inflation of just 0.8%, is dangerously close to falling into a deflationary spiral, with people holding back on spending as they wait for prices to fall.
Another new risk concerns the global impact of the Fed tapering off its quantitative easing programme (see Tapering off? Not yet). This programme has provided a considerable boost, not just to the US economy, but to many emerging economies. Much of the new money flowed into these economies as investors sought better returns. Currencies such as the Indian rupee, the Brazilian real and the Turkish lira are now coming under pressure. The Argentinean peso has already been hit by speculation and fell by 11% on 24/1/14, its biggest one-day fall since 2002. Although a fall in emerging countries’ currencies will help boost demand for their exports, it will drive up prices in these countries and put pressure on central banks to raise interest rates.
Christine Lagarde was one of several speakers at a session titled, Global Economic Outlook 2014. You can see the complete session by following the link below.
Articles
Lagarde warns of risks to global economic recovery TVNZ (27/1/14)
Lagarde Cautions Davos on Global Deflation Risk Bloomberg News, Ian Katz (26/1/14)
Davos 2014: Eurozone inflation ‘way below target’ BBC News (25/1/14)
IMF fears global markets threat as US cuts back on cash stimulus The Guardian, Larry Elliott and Jill Treanor (25/1/14)
Davos 2014: looking back on a forum that was meant to look ahead The Guardian, Larry Elliott (26/1/14)
Speeches at the WEF
Global Economic Outlook 2014 World Economic Forum (25/1/14)
Questions
- Why is deflation undesirable?
- What are the solutions to deflation? Why is it difficult to combat deflation?
- What are the arguments for the USA tapering off its quantitative easing programme (a) more quickly; (b) less quickly?
- How is tapering off in the USA likely to affect the exchange rates of the US dollar against other currencies? Why will the percentage effect be different from one currency to another?
- What are Japan’s three policy arrows (search previous posts on this site)? Should the eurozone follow these three policies?
 The latest preliminary GDP estimates for 2014 Q1 suggest that the economy’s output (real GDP) expanded by 0.8 per cent following on the back of a 0.7 per cent increase in 2013 Q4. Growth was observed in three of the four main industrial sectors: 0.9% in services, 0.8% in production and 0.3% in construction. In contrast, output decreased by 0.7% in agriculture. The total output of the economy is now just 0.6 per cent below its 2008 Q1 peak with the output of the service sector now 2.0 per cent higher.