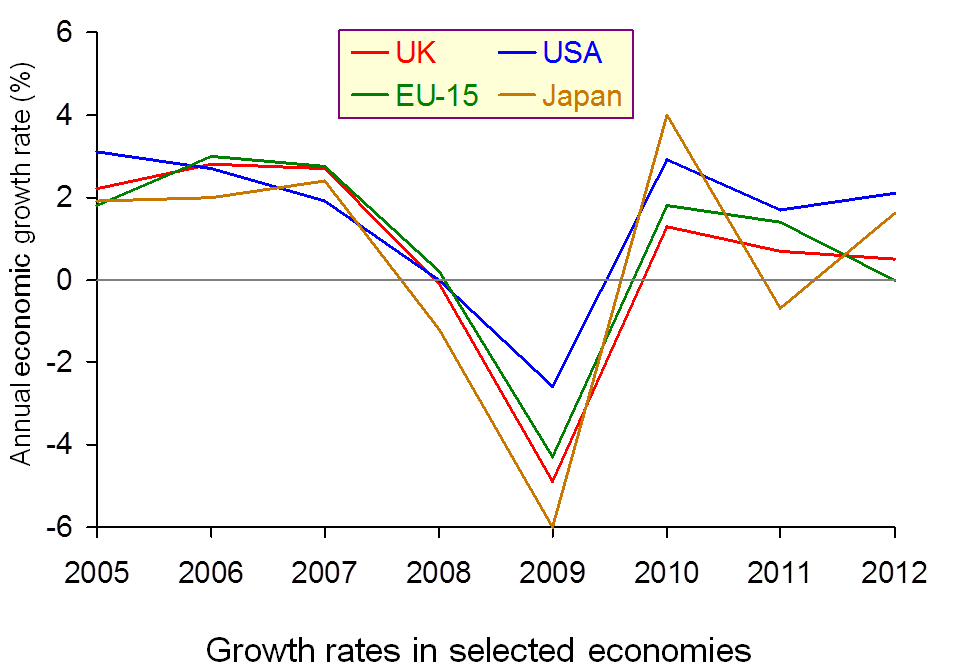
 Here’s an excellent article (the first link below) for giving an overview of macroeconomic thinking and policy since the start of the financial crisis in 2007. It looks at how a Keynesian consensus emerged in 2008–9, culminating in policies of fiscal and monetary stimulus being adopted in most major economies.
It also looks at how this consensus broke down from 2010 with the subsequent problem of rising public-sector deficits and debt, and was replaced by a new, although less widespread, consensus of fiscal restraint.
The article is not just about economic theory and policy, but also about the process and politics of how consensus and ‘dissensus’ emerge. It looks at the spread of ideas as a process of ‘contagion’ and how dissent may reflect the view of different defined groups, such as political parties or schools of economic thought.
Consensus, Dissensus and Economic Ideas: The Rise and Fall of Keynesianism During the Economic Crisis, Henry Farrell (George Washington University) and John Quiggin (University of Queensland) (9/3/12)
Keynesianism in the Great Recession Out of the Crooked Timber, Henry Farrell (9/3/12)
Economics in the Crisis (see also) The Conscience of a Liberal, Paul Krugman (5/3/12)
Questions
- What were the features of the Keynesian consensus in 2008–9?
- To what extent can the consensus of that period be described as the result of ‘contagion’?
- Why did consensus break down in 2010?
- How do economic experts play a political role in economic crises?
- To what extent does a lack of consensus benefit politicians?
- Why may the appearance of a consensus be more important in driving policy than actual consensus?
 Unemployment figures for the UK have been going in the wrong direction for some time. With consumer expenditure, investment and hence aggregate demand remaining low, job creation has been severely lacking. However, 2 pieces of news have emerged in the last couple of days, which as David Cameron said was ‘a massive confidence boost for the UK economy’. Tesco and Nissan have both announced the creation of thousands of new jobs.
Over the next 2 years, Tesco has said that it will create 20,000 new jobs through store improvement and the opening of new stores. Whilst it is not clear how many will be full-time, part-time or apprenticeship placements, it still represents net job creation. This huge investment represents what many are calling a ‘fight-back’ from Tesco, who issued its first profit warning in 20 years, following weak Christmas trading. That announcement slashed their shares by over £5bn and is perhaps partly responsible for this planned investment.
Despite this good news, criticisms have emerged that the major supermarkets are simply inflating the job creation figures and that the actual number of new jobs will be significantly less than the 20,000 suggested. This follows allegations made towards Asda, who claimed to have created 30,000 jobs. However, evidence from records at Companies House suggests that new job creation by the company was closer to 7,000. Whatever the true figure, it still means new jobs, which can only help UK unemployment data.
In addition to this, Nissan has also announced that it will be creating 2,000 new jobs, as it begins production on a new model at its Sunderland factory. The jobs will be created as part of a £125m investment, including a £9.3m grant from the government. This is especially good news, given the area where many of these jobs will emerge. The North East is a region that has been hit particularly hard by the recession and the grant from the government has come from its regional growth fund. Nissan has said that even in hard economic times, it is possible to sell cars, as long as they are competitively priced. Neither of the plans discussed above will create jobs immediately, but perhaps the key is that it creates confidence, which is a rarity in the UK with the current economic situation. The following articles consider these job creation plans and their wider implications.
Tesco plans to create 20,000 UK jobs over 2 years BBC News (5/3/12)
Tesco to create 20,000 jobs in UK fight-back Telegraph, Jamie Dunkley (6/3/12)
Tesco’s UK boss defends ‘new jobs’ claims Sky News (5/3/12)
Tesco to freshen up with 20,000 new staff Financial Times, Andrea Felsted (5/3/12)
Now Tesco creates 20,000 jobs – with pay Independent (9/5/11)
Nissan to build new car in Sunderland BBC News (6/3/12)
Nissan pledges 2,000 new jobs at North East plant Sky News, Gerard Tubb (6/3/12)
Nissan Invitation compact car set to create 2,000 jobs Telegraph, Roland Gribben and David Millward (6/3/12)
Nissan to create 2,000 new jobs by building compact car in Sunderland Guardian, Dan Milmo(6/3/12)
Questions
- Explain the process by which net job creation should provide a boost to the economy.
- Will these new jobs have any impact on the government’s budget deficit?
- Why is there concern that the supermarkets are inflating the employment creation figures?
- What type of unemployment has been created by the recession? Why have certain areas, such as the North East been affected so badly by the recession and austerity measures?
- Which factors could have led to Tesco’s weaker trading figures towards then end of 2011? Why did this lead to a £5bn loss in the value of the group’s shares?
- Nissan has said that cars can be sold as long as they are competitively priced. To what extent do you think price is the main competitive weapon in the market for cars and in the supermarket industry?
 In December 2011, the ECB provided some €489bn to banks in the form of three-year loans at low interest rates (1%) through open-market operations (see Will new ECB repo operations support the eurozone bond market?).
These ‘Longer-term refinancing operations’ or ‘LTROs’ are designed to ease the burden on European banks which have been struggling to persuade markets that they are dealing with their large amounts of toxic debt, some of which is sovereign debt. Indeed, some of the ECB loans have been used to purchase Italian and Spanish bonds, thereby reducing the likelihood that these countries will default on their debts – at least for the timebeing.
On 29 February 2012, the ECB offered another round of LTROs. Some 800 banks borrowed €530bn under the scheme, bringing the total to a little over €1tr. Initially, much of the money has been put back on overnight deposit with the ECB. The hope, however, is that the loans will be used to support increased credit throughout the eurozone and to fund further purchases of sovereign debt.
But will the increased narrow money supply in the eurozone through these open-market operations result in increased broad money and increased spending and growth? The answer to that depends a great deal on confidence: confidence of banks to lend to firms and consumers; confidence of firms and consumers to borrow. The hope is that the extra money supply will not simply see a corresponding reduction in the velocity of circulation.
The following articles consider the likely effects of these longer-term repos on the real economy.
Articles
ECB hands €529bn in emergency loans to European banks Guardian, Heather Stewart (29/2/12)
Q&A: The ECB’s bank funding programme The Telegraph, Angela Monaghan (29/2/12)
Fighting Debt with Debt Forbes, Bob McTeer (5/3/12)
Is ECB’s €1trn cash boost just the tip of the iceberg? Investment Week, Kyle Caldwell, Dan Jones (5/3/12)
Banks deposit record €821bn at ECB Financial Times, Mary Watkins (5/3/12)
Europe economy may see slim gain from supersize funding: poll Reuters, Sumanta Dey (5/3/12)
Who is the ECB helping? BBC News, Stephanie Flanders (29/2/12)
ECB information on OMOs
Open Market Operations ECB
Questions
- Explain how longer-term refinancing operations work.
- What will determine how much of these ECB loans will be lent to companies?
- Explain what is meant by (a) the velocity of circulation; (b) the money multiplier. Why will the size of these two determine the likely success of the ECB’s LTRO programme?
- Why may the ECB’s actions boost market sentiment? Why might they have the opposite effect?
- Explain what is meant by the “continued de-leveraging by banks”. How does this impact on the money multiplier?
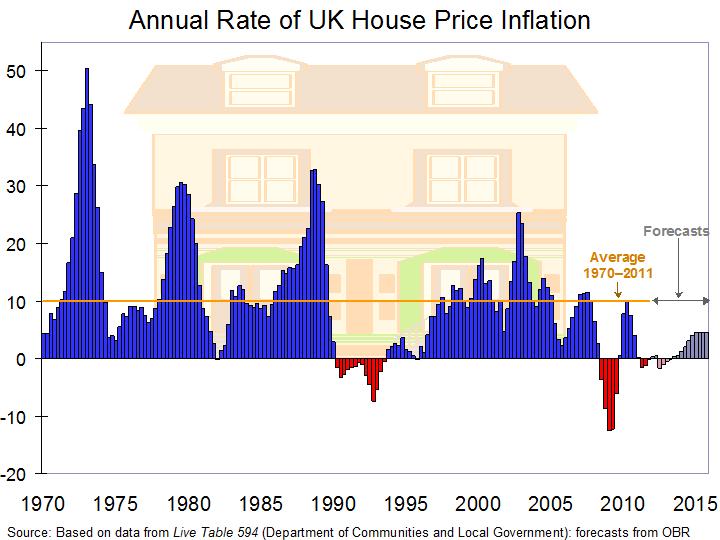 The housing market has long been seen as a crucial element in stimulating the British economy. For this reason various incentives had been introduced to encourage people to buy properties. (Click here for a PowerPoint of the chart.)
One such strategy was the stamp duty holiday. Stamp Duty Land Tax is paid by the purchaser of a property against a purchase price and the cost of it will rise through each price band. The stamp duty holiday meant that first-time buyers were free from the 1% stamp duty on homes that cost under £250,000. However, this holiday is due to end from March 2012, as according to the government, the holiday has been ineffective. Indeed, in the Autumn statement documents, the government said:
‘The government is publishing analysis showing that the stamp duty land tax relief for first-time buyers has been ineffective in increasing the number of first time buyers entering the market.’
The government has said that instead it will focus on other strategies that provide better value for money. Such schemes include a mortgage guarantee scheme and the FirstBuy scheme launched last year, both of which aim to help those struggling to finance the purchase of their first properties.
According to the Land Registry, property prices have fallen by over 1% over the past year, so fewer properties will face the stamp duty land tax, but this data does little to instill confidence in the housing market being the stimulus that the economy needs. By stimulating the housing market, construction jobs should be created and this in turn should create a much needed multiplier effect helping to boost other sectors within the economy. The following articles consider this latest development.
Stamp duty rush boosts January valuations Mortgage Strategy, Tessa Norman (11/2/12)
New deals for buyers as stamp duty holiday ends BBC News, Susannah Streeter (11/2/12)
Autumn Statement: Stamp duty concession to end BBC News (29/11/11)
First-time buyers boost mortgage market activity FT Adviser, Michael Trudeau (9/2/12)
When shared ownership turns sour Guardian, Rupert Jones (10/2/12)
Questions
- Why does the housing market play such a crucial role in the economy?
- What is the multiplier effect? How will new jobs in the construction industry help other sectors in the economy?
- Why has the stamp duty holiday been ‘ineffective’ in stimulating the housing market?
- How have the other schemes introduced by the government created incentives in the housing market?
- Why have January valuations improved? Use a demand and supply diagram to illustrate your explanation.
 In the third quarter of 2011, the UK economy grew by 0.6% – nothing to shout about, but at least it was positive. Since then there has been growing concern about the state of the recovery with many commentators widely expecting to see much lower growth in the final quarter of last year.
Today, those commentators were proved right, as official figures released show the UK economy shrank by 0.2%. It doesn’t mean we’re in a recession (that requires 2 successive quarters of negative growth), but if growth doesn’t pick up in quarter 1 of 2012, then ‘Double-Dip Recession’ headlines will fill the front page.
Despite the disappointment that the UK economy has shrunk, the figures were not wholly unexpected, especially given the data released a week or so before, which showed unemployment had risen. Furthermore, with the crisis in the eurozone and many other countries still struggling to mount an economic recovery, there have been few external stimuli for the UK.
Although the fall in growth was larger than expected (0.2% as opposed to the predicted 0.1%), the UK economy is expected to grow throughout 2012. However, the IMF has reduced its forecast annual growth rate from 1.6% to 0.6%. The economic climate for 2012 remains uncertain and much will depend on developments in the eurozone. Further problems could spell trouble, but if there is an improvement in the fortunes of Europe, confidence could return to the markets and economic recovery could be faster. Ian McCafferty, the Chief Economic Adviser of the CBI said:
While the acute fears seen at the end of last year over global demand may be subsiding, 2012 will prove to be a difficult year for UK manufacturing, as the crisis in the eurozone – our biggest export market – has yet to reach any definitive resolution.
Whether or not we do move into a double-dip recession is uncertain and following this latest data, many commentators say it is a 50:50 change; and even then it hinges on many factors. However, even if quarter 1 of 2012 sees negative growth and hence a return to recession for the UK, Chris Williamson from Markit said that ‘there are growing indications that any downturn is likely to be ‘mild and short-lived’. The following articles consider the state of the UK economy.
Unemployment to soar as UK heads back into recession The Telegraph, Philip Aldrick (25/1/12)
UK economy shrinks by 0.2% in last 3 months of 2011 BBC News (25/1/12)
UK GDP: what the economists say Guardian (25/1/12)
UK recession threat: can we dodge the double dip? Citywire, Chris Marshall (25/1/12)
Double-dip recession fears as UK economy shrinks 0.2 percent Independent, Peter Cripps (25/1/12)
PM says ‘no complacency’ on economy Financial Times, Norma Cohen and Elizabeth Rigby (25/1/12)
The UK economy is shrinking. Time to listen to gloom-mongers? Guardian, Phillip Inman (25/1/12)
UK economy shrinks in Q4, raising recession fears The Associated Press (25/1/12)
FTSE CLOSE: Stocks slide as 0.2% GDP fall sparks recession fears; banks among the biggest fallers This is Money (25/1/12)
Sorrell: ‘UK will avoid double-dip recession’ Sky News, Tom Rayner (25/1/12)
Recovery in rehab BBC News, Stephanie Flanders (25/1/12)
Questions
- How is a recession defined? What are the typical characteristics of a recession? (Think about the macroeconomic objectives).
- Which particular sectors of the UK economy were the most severely affected in Q4 of 2011?
- Examine the main causes of the UK’s decline in national output.
- Which of the causes identified in question 3 do you think is the key factor keeping UK national output from growing? Explain your answer.
- Why is there a growing presence of companies from emerging markets in the top 100?
- Why are many commentators suggesting that even if the UK goes into a recession, it is likely to be ‘mild and short-lived’?
- What has happened to stock markets following the release of this latest economic data?
- Evaluate the options open to the Coalition government in stimulating the UK economy. To what extent would your policy solution damage the Coalition’s aim of cutting the UK’s structural budget deficit?