Diesel prices: an update
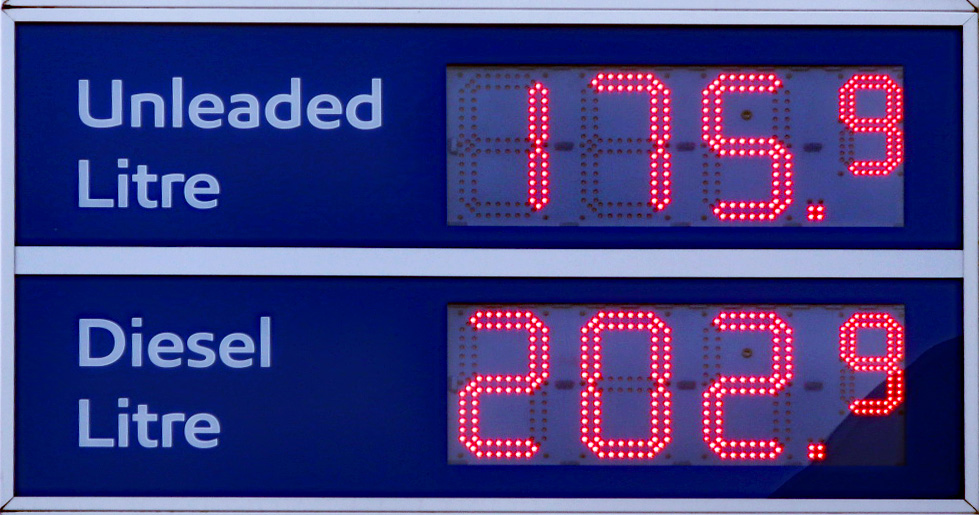
As we saw in a recent post, Why have diesel prices risen more than petrol prices?, diesel prices have soared since the outbreak of the Iran war at the end of February this year. In the UK, they rose from around 142p just before the US/Israeli attack on Iran to over 200p by the start of October – a rise of around 42%. The rise has been aggravated by threats of Houthi attacks on oil tankers in the Red Sea, Ukrainian attacks on Russian refineries leading to a Russian diesel export ban, a Chinese diesel export ban, refinery shortages in several countries and buoyant industrial, transport and agricultural demand.
 The hope was that the gradual reopening of the Strait of Hormuz would ease oil prices. But despite oil flows increasing from the Gulf, prices have not eased. And with the November mid-term elections approaching in the USA, the Trump administration has been threatening to cut off US diesel exports and divert diesel supplies to the domestic market, thereby reducing diesel prices in the USA. The threats were to put pressure on European countries to tap into their own emergency stocks to ease global diesel prices. By the beginning of October, diesel futures were at record prices.
Then on Friday 2 October, the Group of Seven (G7) nations gave in to pressure from the USA (one of the G7). Co-ordinated by the International Energy Agency (IEA), the G7 announced the release over the next four months of 100 million barrels from reserves, partly of diesel and partly of crude oil. The release would be front loaded to put immediate downward pressure on diesel prices. President Trump stated that a major proportion would be from European stockpiles.
 The IEA had already organised the release of 400 million barrels from stockpiles back in March. However, not all were released because, at the time, the USA was flooding the market with its own diesel to keep the market price down. By the beginning of October, 75 million barrels had yet to be released, but were still considered ‘available’. The new G7 announcement did not make clear whether the 100 million barrels would be in addition to the March agreement or would involve only an additional 25 million barrels.
This promise of an increase in supply had an immediate effect, with US diesel futures falling by around 4.5% and European diesel futures by around 6.5%. The question, though, is how long any reduction in diesel prices would last. The world consumes roughly 840 million to 900 million barrels of diesel per month. Unless the conflicts and other causes of the underlying shortage of diesel are resolved, the extra diesel released from stockpiles will provide only a temporary relief from high prices.
Articles
 UK diesel prices top £2 a litre for first time, RAC says
- G7 to release millions of barrels of oil and diesel after Trump threat
- Will diesel prices go down? Trump says Europe to draw on reserves
- G7 countries agree on release of diesel and oil stocks after US pressure
- IEA says 325 million barrels of emergency oil released, with 75 million still to come
- Europe to release ‘massive amount of diesel’ after Trump’s supply threat
- Diesel price set to fall after Europe releases supplies
- Exclusive: Trump’s Diesel Price Dilemma Isn’t About Supply — Expert Says It’s Because ‘Fuel is in the Wrong Place’
BBC News, Lucy Hooker and Archie Mitchell (2/10/26)
BBC News, Archie Mitchell and Lucy Hooker (3/10/26)
USA Today, Miles J Herszenhorn (2/10/26)
Reuters, Kate Abnett and Jarrett Renshaw (2/10/26)
Euronews, Simon Ormiston (3/10/26)
Independent, Athena Stavrou (3/10/26)
Daily Business, Terry Murden (3/10/26)
Trading View (3/10/26)
Videos
- Diesel export tensions rise: What’s behind the dispute
- Why diesel is at the heart of geopolitics
- G7 to release 100 million barrels of diesel and crude oil to stop soaring prices
- G7 to release 100 million barrels of oil reserves as diesel prices surge
CNBC on YouTube, Steve Sedgwick (2/10/26)
Sky News, Ed Conway (2/10/26)
5 News on YouTube, Catherine Jones (2/10/26)
Global News on YouTube (2/10/26)
Questions
- What will determine the size of the effect of the G7’s decision to release stocks of diesel and crude oil?
- How do expectations affect diesel prices – both spot and future prices?
- Why would a diesel export ban by the Trump administration have only a minimal effect on diesel prices in much of the USA?
- What determines the price elasticity of demand for diesel in (a) the short run; (b) over a few years?