 What lies ahead for economic growth in 2013 and beyond? And what policies should governments adopt to aid recovery? These are questions examined in four very different articles from The Guardian.
The first is by Nouriel Roubini, Professor of Economics at New York University’s Stern School of Business. He was one of the few economists to predict the collapse of the housing market in the USA in 2007 and the credit crunch and global recession that followed. He argues that continuing attempts by banks, governments and individuals to reduce debt and leverage will mean that the advanced economies will struggle to achieve an average rate of economic growth of 1%. He also identifies a number of other risks to the global economy.
 In contrast to Roubini, who predicts that ‘stagnation and outright recession – exacerbated by front-loaded fiscal austerity, a strong euro and an ongoing credit crunch – remain Europe’s norm’, Christine Lagarde, head of the IMF and former French Finance Minister, predicts that the eurozone will return to growth. ‘It’s clearly the case’, she says, ‘that investors are returning to the eurozone, and resuming confidence in that market.’ Her views are echoed by world leaders meeting at the World Economic Forum in Davos, Switzerland, who are generally optimistic about prospects for economic recovery in the eurozone.
The third article, by Aditya Chakrabortty, economics leader writer for The Guardian, looks at the policies advocated at the end of World War II by the Polish economist, Michael Kalecki and argues that such policies are relevant today. Rather than responding to high deficits and debt by adopting tough fiscal austerity measures, governments should adopt expansionary fiscal policy, targeted at expanding infrastructure and increasing capacity in the economy. That would have an expansionary effect on both aggregate demand and aggregate supply. Sticking with austerity will result in continuing recession and the ‘the transfer of wealth and power into ever fewer hands.’
 But while in the UK and the eurozone austerity policies are taking hold, the new government in Japan is adopting a sharply expansionary mix of fiscal and monetary policies – much as Kalecki would have advocated. The Bank of Japan will engage in large-scale quantitative easing, which will become an open-ended commitment in 2014, and is raising its inflation target from 1% to 2%. Meanwhile the Japanese government has decided to raise government spending on infrastructure and other government projects.
So – a range of analyses and policies for you to think about!
Risks lie ahead for the global economy The Guardian, Nouriel Roubini (21/1/13)
Eurozone showing signs of recovery, says IMF chief The Guardian, Graeme Wearden (14/1/13)
Austerity? Call it class war – and heed this 1944 warning from a Polish economist The Guardian, Aditya Chakrabortty (14/1/13)
Bank of Japan bows to pressure with ‘epoch-making’ financial stimulus The Guardian, Phillip Inman (22/1/13)
Questions
- What are the dangers facing the global economy in 2013?
- Make out a case for sticking with fiscal austerity measures.
- Make out a case for adopting expansionary fiscal policies alongside even more expansionary monetary policies.
- Is is possible for banks to increase their capital-asset and liquidity ratios, while at the same time increasing lending to business and individuals? Explain.
- What are the implications of attempts to reduce public-sector deficits and debt on the distribution of income? Would it be possible to devise austerity policies that did not have the effect you have identified?
- What will be the effect of the Japanese policies on the exchange rate of the yen with other currencies? Will this be beneficial for the Japanese economy?
 Japan’s general election on 16 December was won by the centre-right Liberal Democratic Party (LDP), led by Shinzo Abe. It gained a two-thirds majority in the lower house. It returns to power after losing to the Democratic Party in 2009. Previously it had been in office for most of the time since 1955.
The LDP has promised to revive the flagging Japanese economy, which has been suffering from years of little or no growth and returned to recession last quarter. Economic confidence has been damaged by a dispute with China about the sovereignty over some small islands in the East China Sea. The economy, whose exports make up some 13% of GDP, has suffered from the global slowdown and a high yen. The yen has appreciated against the dollar by around 40% since 2007.
The economy has also suffered from the shutdown of all its nuclear reactors following the earthquake and tsunami last year. Nuclear power accounted for over 30% of the country’s electricity generation.
 Mr Abe promises to revive the economy through fiscal and monetary policies. He plans a fiscal stimulus package in early 2013, with increased government expenditure on infrastructure and other public-works. He also wants the Bank of Japan to increase its inflation target from 1% to 3% and to achieve this through various forms of monetary easing.
The initial reactions of markets to the election result were favourable. The stock market rose and the yen fell.
However, as the following articles discuss, there are dangers associated with Mr Abe’s policies. The expansionary fiscal policy will lead to a rise in the country’s general-government debt, which, at some 240% of GDP, is by far the largest in the developed world. This could lead to a loss of confidence in Japanese debt and a fall in the price of bonds on the secondary markets and a rise in government borrowing costs. Also, a depreciation of the yen, while welcomed by exporters, would increase the price of imports, including food and raw materials.
Changing of guard in Japan as PM concedes vote CNN, Yoko Wakatsuki, Brian Walker, and Hilary Whiteman (17/12/12)
LDP Win Clears Pipes for Japan Fiscal Spigot Bloomberg Businessweek, Toru Fujioka (17/12/12)
Economic implications of Japan’s election Huffington Post (16/12/12)
Japan economy contracts again Taipei Times (11/12/12)
Japan elections: Shares rise and yen weakens on Abe win BBC News (17/12/12)
Shinzo Abe’s challenges in reviving Japan’s economy BBC News, Puneet Pal Singh (17/12/12)
Can Shinzo Abe Save Japan? Slate, Matthew Yglesias (30/11/12)
Deflation only natural when politicians refuse to fix oversupplied Japan Japan Times, Teruhiko Mano (17/12/12)
New Year messages from Japan BBC News, Stephanie Flanders (18/12/12)
Japan – Muddling On Or Growing Stronger? Seeking Alpha, Anthony Harrington (12/12/12)
Japanese government unveils £138bn stimulus package The Guardian (11/1/13)
Questions
- Using macroeconomic data from sources such as sites 6, 7 and 9 in the Economics Network’s Economic Data freely available online, describe Japan’s macroeconomic situation over the past 10 years.
- Why has the Japanese yen appreciated so much in recent years?
- What forms could monetary easing take in Japan?
- Why might it prove difficult to stimulate the Japanese economy through fiscal and monetary policies?
- What undesirable side-effects might result from expansionary fiscal and monetary policies?
- What structural weaknesses are there in the Japanese economy that have hindered economic growth? What policies might the new Japanese government pursue in tackling these structural weaknesses?
 The Autumn Statement, delivered annually by the Chancellor of the Exchequer in late November or early December, is rather like a second Budget. In his statement, the Chancellor presents new forecasts for the UK economy by the Office for Budget Responsibility (OBR) and announces various policy changes in the light of the forecasts.
So what does this OBR say? Its headline reads, “Government borrowing revised higher as weaker economy hits revenues” and this is followed by the statement:
The OBR has revised up its forecasts for public-sector borrowing over the next five years, as a weaker outlook for the economy reduces tax revenues. As a result, the Government no longer seems likely to achieve its target of reducing public-sector net debt in 2015–16.
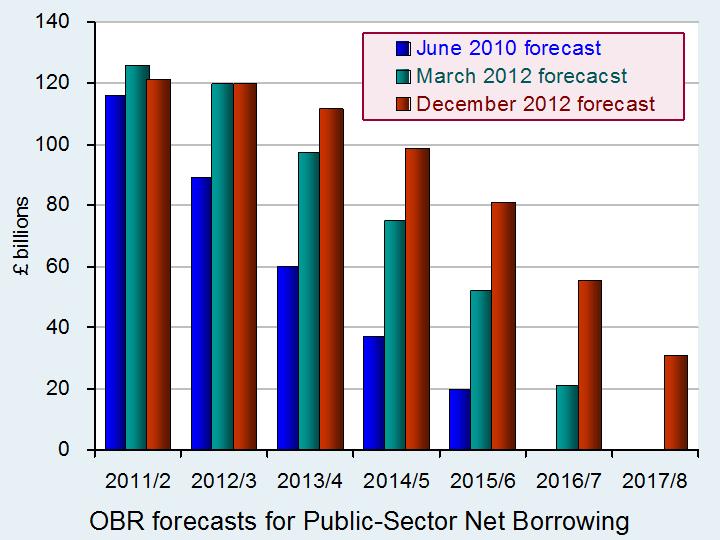 The chart shows OBR forecasts for public-sector net borrowing made in June 2010 (its first forecast after the OBR was formed by the Coalition government), in March 2012 and in December 2012. The current forecast clearly shows borrowing set to decline more slowly than in the earlier forecasts. Click here for a PowerPoint of the chart. (Note that the effects of transferring the pension assets of the Royal Mail to the Treasury and the effects of not paying interest to the Bank of England on government bonds purchased under quantitative easing programmes have not been included in order to make the three forecasts consistent.)
So with a weaker economy and slower recovery than previously forecast, what are George Osborne’s options? He and his colleagues, along with various economists, argue for sticking to Plan A. This means continuing with austerity measures in order to get the public-sector deficit down. But with government borrowing having fallen more slowly than forecast, this means further government expenditure cuts, such as reductions in benefits, cuts in grants to local authorities and reductions in pensions relief. Even so, achieving his two targets – (1) eliminating the cyclically adjusted current (as opposed to capital) budget deficit by 2015/16 (the so-called ‘fiscal mandate’), and (2) public-sector debt falling as a proportion of GDP by 2015/16 – will both be missed. They were extended by a year in the Budget last March. They have now been extended by a further year to 2017/18.
The opposition and many other economists argue that Plan A has failed. Austerity has prevented the economy from growing and has thus meant a slower reduction in the deficit as tax revenues have not grown nearly as much as hoped for. A more expansionary policy would allow the deficit to be reduced more quickly, especially if extra government expenditure were focused on infrastructure and other capital spending.
 It could be argued that George Osborne’s Autumn Statement moves some way in this direction – a Plan A+. He is making deeper cuts in welfare and government departmental spending in order to divert monies into capital spending. For example, there will be £1bn of extra expenditure on roads; £1bn extra on schools; £270m on FE colleges; and £600m extra for scientific research. Also, by extending the period of austerity to 2017/18, this has meant that he has not had to make even deeper cuts. What is more, he is increasing income tax allowances and cutting the rate of corporation tax by 1% more than originally planned and scrapping the planned 3p per litre rise in road fuel duty. He hopes to make up any lost tax revenue from these measures by HMRC clamping down on tax evasion.
But by sticking to his broad austerity strategy, and with many parts of the global economy having weakened, it looks as if the UK economy is in for several more years of sluggish growth. Winter is going to be long.
Webcasts and Podcasts
 Autumn Statement: George Osborne scraps 3p fuel duty rise BBC News, Carole Walker (5/12/12)
Autumn Statement: OBR says deficit ‘shrinking more slowly’ BBC News, Robert Chote (5/12/12)
Autumn Statement: Headlines from George Osborne’s speech BBC News, Andrew Neil (5/12/12)
Autumn Statement: Flanders, Robinson and Peston reactio BBC News, Stephanie Flanders, Nick Robinson and Robert Peston (5/12/12)
Boosting the British Budget CNN, Jim Boulden (5/12/12)
Autumn statement 2012: key points – video analysis The Guardian, Larry Elliott, Jill Treanor, Patrick Collinson and Damian Carrington (5/12/12)
Articles
Autumn Statement 2012: the full speech The Telegraph (5/12/12)
Autumn Statement: Benefit squeeze as economy slows BBC News (5/12/12)
Autumn Statement: At-a-glance summary of key points BBC News (5/12/12/)
Austerity to last until 2018, admits George Osborne Independent, Oliver Wright
Autumn statement: George Osborne reveals benefits cut Channel 4 News (5/12/12/)
Autumn Statement 2012: Cut welfare, create jobs – a very Tory statement The Telegraph, Damian Reece (5/12/12)
Autumn statement 2012: economy weaker than expected, Osborne says The Guardian, Heather Stewart (5/12/12)
Analysis: Even the ‘autumn’ bit seemed optimistic BBC News, Chris Mason (5/12/12)
George Osborne’s autumn statement 2012: reaction The Guardian, Julia Kollewe (5/12/12)
Candid Osborne avoids political risk Financial Times, Janan Ganesh (5/12/12)
Autumn statement: Why George Osborne’s Budget won’t be a game changer The Telegraph, Allister Heath (4/12/12/)
Autumn statement 2012: expert verdict The Guardian, Richard Murphy, Dominic Raab, Ann Pettifor, Gavin Kelly, Prateek Buch and Mark Serwotka (5/12/12/)
The alternative autumn statement Channel 4 News (5/12/12)
Autumn Statement 2012: man cannot live by deficit reduction alone The Telegraph, Roger Bootle (5/12/12)
Autumn statement: cuts are just a sideshow The Guardian, John Redwood (5/12/12)
What does the Autumn Statement mean for business? Economia, David Mellor (5/12/12)
Autumn Statement Reaction: UK AAA ‘safe for today’ Investment Week (5/12/12)
Autumn Statement: A wintry statement of reality BBC News, Stephanie Flanders (4/12/12)
What has changed? BBC News, Stephanie Flanders (6/12/12)
UK warned on debt ‘credibility’ over AAA rating BBC News (5/12/12)
Data
Autumn statement 2012 in charts The Guardian, Simon Rogers (5/12/12/)
Who suffers most from Britain’s austerity? How the figures stack up The Guardian, Tom Clark (5/12/12)
Economic and fiscal outlook charts and tables – December 2012 OBR (5/12/12)
Economic and fiscal outlook supplementary economy tables – December 2012 OBR (5/12/12)
Forecasts for the UK economy HM-Treasury
OBR, Treasury and IFS links
Economic and fiscal outlook – December 2012 OBR (5/12/12)
Autumn Statement 2012 HM Treasury (5/12/12)
Autumn Statement 2012 IFS
Questions
- Distinguish between ‘stocks’ and ‘flows’. Define (a) public-sector net borrowing (PSNB) and (b) the public-sector net debt (PSND) and explain whether each one is a stock or a flow.
- Summarise the measures announced by George Osborne in his Autumn Statement.
- What are his arguments for not adopting a more expansionary fiscal policy?
- Assess his arguments.
- What is meant by the ‘output gap’? What are the OBR’s forecasts about the output gap and what are the implications?
- How has quantitative easing affected PSNB and PSND?
- Distinguish between the cyclical and structural deficit. What implications does this distinction have for fiscal policy?
 At the start of 2013, the USA faces a ‘fiscal cliff’. By this is meant that, without agreement by Congress on new fiscal measures, the USA will be forced into tax rises and expenditure cuts of around $650 billion (over 4% of GDP). This would probably push the economy straight back into recession. This in turn would have a serious dampening effect on the global economy.
But why would fiscal policy be automatically tightened? The first reason is that tax cuts given under the George W. Bush administration during 2001–3 (largely to the rich) are due to expire. Also a temporary cut in payroll taxes and an increase in tax credits given by President Obama are also due to end. These tax increases would form the bulk of the tightening. The average US household would pay an extra $3500 in taxes, reducing after-tax income by around 6%.
The second reason is that various government expenditure programmes are scheduled to be reduced. These reductions in expenditure amount to around $110 billion.
 It is likely, however, that Congress will agree to delay or limit the tax increases or expenditure cuts; politicians on both sides want to avoid sending the economy back into recession. But what the agreement will be is not at all clear at this stage.
Republicans are taking a tougher line than Democrats on cutting the budget deficit; they are calling for considerably less restraint in implementing the government expenditure cuts. On the other hand, they are likely to be less willing to raise taxes.
But unless something is done, the consequences for 2013 could be dire. The fiscal cliff edge rapidly approaches.
Articles
Nearly 90 percent of Americans would see taxes rise if ‘fiscal cliff’ hits Washington Post, Lori Montgomery (1/10/12)
Fiscal cliff a serious threat, but unlikely CNN Money, Chris Isidore (1/10/12)
“Fiscal cliff” fears may impede faster job growth Chicago Tribute, Lucia Mutikani (1/10/12)
Avert Fiscal Cliff With Entitlement Cuts, Tax Increases Bloomberg (2/10/12)
‘Fiscal cliff’ to hit 90% of US families Financial Times, James Politi (1/10/12)
Investors don’t want the US to fall off the fiscal cliff The Telegraph, Tom Stevenson (22/9/12)
Gauging the fiscal cliff BBC News, Stephanie Flanders (27/9/12)
The US fiscal cliff – and the fiscal chasm BBC News, Stephanie Flanders (2/10/12)
US fiscal cliff threat fails to galvanise policymakers Guardian Economics blog, Mohamed el-Erian (1/10/12)
Multiplying Europe’s fiscal suicide (technical) The Telegraph, Ambrose Evans-Pritchard (1/10/12)
Q&A: The US fiscal cliff BBC News (7/11/12)
US election: Four more years… of what? BBC News, Stephanie Flanders (7/11/12)
Background
United States fiscal cliff Wikipedia
Questions
- Explain what is meant by the ‘fiscal cliff’ and what is its magnitude.
- What would be the multiplier implications of the USA ‘falling off the cliff’ both for the USA and for the rest of the world?
- What factors determine the size of the government expenditure and tax multipliers? What would be the problems of (a) underestimating and (b) overestimating the size of these multipliers?
- How can a fiscal stimulus be reconciled with a policy of reducing the size of the budget deficit as a proportion of GDP over the longer term?
- In what ways can the actions of Democrats and Republicans be seen as game playing? What are the possible payoffs and risks to both sides?
- Is relying on export growth to bring the world economy out of recession a zero sum game?
- Explain which is likely to be more effective in stimulating short- and medium-term economic growth in the USA: fiscal policy or monetary policy.
 New data released on 25/7/12 by the Office for National Statistics showed that the UK economy shrank by a further 0.7% in the second quarter of 2012. This makes it the third quarter in a row in which GDP has fallen – and it is the steepest fall of the three. Faced with this, should the government simply maintain the status quo, or does it need to take new action?
The construction sector declined the most steeply, with construction output 5.2% down on the previous quarter, which in turn was 4.9% down on the quarter previous to that. The output of the production industries as a whole fell by 1.3% and the service sector fell by 0.1%. (For a PowerPoint of the following chart, click here.)
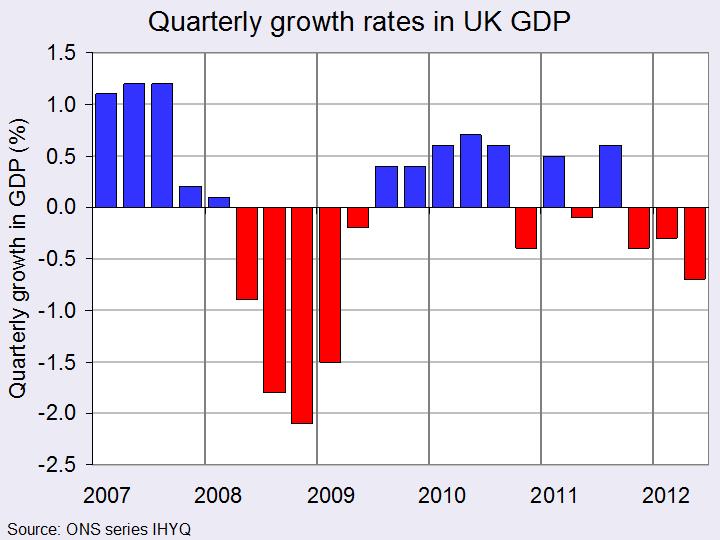
The immediate cause of the decline in GDP has been a decline in real aggregate demand, but the reasons for this are several. Consumer demand has fallen because of the squeeze on real wages, partly the result of low nominal pre-tax wage increases and partly the result of inflation and tax rises; the government’s austerity programme is holding back a growth in government expenditure; export growth has been constrained by a slowing down in the global economy and especially in the eurozone, the UK’s major trading partner; and investment is being held back by the pessimism of investors about recovery in the economy and difficulties in raising finance.
So what can be done about it?
Monetary policy is already being used to stimulate demand, but to little effect (see Pushing on a string. Despite record low interest rates and a large increase in narrow money through quantitative easing, broad money is falling as bank lending remains low. This is caused partly by a reluctance of banks to lend as they seek to increase their capital and liquidity ratios, and partly by a reluctance of people to borrow as individuals seek to reduce their debts and as firms are pessimistic about investing. But perhaps even more quantitative easing might go some way to stimulating lending.
Fiscal policy might seem the obvious alternative. The problem here is that the government is committed to reducing the public-sector deficit and is worried that if it eases up on this commitment, this would play badly with credit rating agencies. Indeed, on 27/7/12, Standard & Poor’s, one of the three global credit rating agencies, confirmed the UK’s triple A rating, but stated that “We could lower the ratings in particular if the pace and extent of fiscal consolidation slows beyond what we currently expect.” Nevertheless, critics of the government maintain that this is a risk worth taking.
The following articles look at the causes of the current double-dip recession, the deepest and most prolonged for over 100 years. They also look at what options are open to the government to get the economy growing again.
Articles
Britain shrinks again The Economist (25/7/12)
Shock 0.7% fall in UK GDP deepens double-dip recession Guardian, Larry Elliott (25/7/12)
UK GDP figures: expert panel verdict Guardian, Frances O’Grady, Will Hutton, Sheila Lawlor, Vicky Pryce and John Cridland (25/7/12)
GDP shock fall: UK growth in 2012 ‘inconceivable’, warn economists The Telegraph, Angela Monaghan (25/7/12)
UK recession deepens after 0.7% fall in GDP BBC News (25/7/12)
UK economy: Why is it shrinking? BBC News (25/7/12)
UK GDP: A nasty surprise and a puzzle BBC News, Stephanie Flanders (25/7/12)
Tough choices for Mr Osborne BBC News, Stephanie Flanders (26/7/12)
David Cameron in pledge to control UK’s debt Independent, Andrew Woodcock and James Tapsfield (26/7/12)
David Cameron defends economic policies BBC News (26/7/12)
The GDP number is awful – and it’s the product of the Government’s amateur policies, not the euro crisis The Telegraph, Thomas Pascoe (25/7/12)
UK recession: have we heard it all before? Guardian, Duncan Weldon (25/7/12)
US economic growth slows in second quarter BBC News (27/7/12)
GDP data trigger debate on economy Financial Times, Norma Cohen and Sarah O’Connor (25/7/12)
Does weak UK growth warrant more QE? Financial Times (25/7/12)
The recession: Osborne’s mess Guardian editorial (25/7/12)
Data
Gross Domestic Product, Preliminary Estimate, Q2 2012 ONS (25/7/12)
Preliminary Estimate of GDP – Time Series Dataset 2012 Q2 ONS (25/7/12)
Questions
- What are the causes of the deepening of the current recession in the UK?
- Search for data on other G7 countries and compare the UK’s performance with that of the other six countries (see, for example, the OECD’s StatExtracts.
- Compare the approach of George Osborne with that of Neville Chamberlain in 1932, during the Great Depression.
- Does weak UK growth warrant more quantitative easing by the Bank of England?
- To what extent can fiscal policy be used to stimulate the economy without deepening the public-sector deficit in the short term?
- What is meant by ‘crowding out’? If fiscal policy were used to stimulate demand, to what extent would this cause crowding out?