 Should the object of monetary policy be simply one of keeping inflation within a target range? In a speech given on 9 October, the Governor of the Bank of England, Sir Mervyn King, questioned whether the interest-rate setting policy of the Monetary Policy Committee (MPC) has been too narrow.
He considered whether interest rates should have been higher before the financial crisis and crash of 2007–9. This could have helped to reduce the asset price bubble and discouraged people from taking out excessive loans.
But then there is the question of the exchange rate. Would higher interest rates have pushed the exchange rate even higher, with damaging effects on exports? Today the trade weighted exchange rate is some 20% lower than before the crash. The government hopes that this will encourage a growth in exports and help to fuel recovery in demand. But as Dr King said, “The strategy of reducing domestic spending and relying more on external demand is facing a real problem because not everyone can do it at the same time.”
 Then there is the question of economic growth. Should a target rate of growth be part of the MPC’s target? Should the MPC adopt a form of Taylor rule which targets a weighted average of the inflation rate and the rate of economic growth?
Certainly monetary policy today in the UK and many other countries is very different from five years ago. With interest rates being close to zero, there is little scope for further reductions; after all, nominal rates cannot fall below zero, otherwise people would be paid for borrowing money! So the focus has shifted to the supply of money. Several attempts have been made to control the money supply through programmes of quantitative easing. Indeed many economists expect further rounds of quantitative easing in the coming months unless there is a substantial pick up in aggregate demand.
So what should be the targets of monetary policy? The following articles look at Dr King’s speech and at various alternatives to a simple inflation target.
Articles
Mervyn King says must face up to monetary policy’s limits’ Reuters, David Milliken and Sven Egenter (9/10/12)
Bank of England’s Mervyn King defends low interest rates pre-crisis The Telegraph, Emma Rowley (9/10/12)
Banks should have had a leverage cap before crash, says Mervyn King The Guardian, Heather Stewart and Phillip Inman (9/10/12)
King Says BOE Must Keep Targeting Inflation as Tool Revamp Looms Bloomberg, Scott Hamilton and Svenja O’Donnell (9/10/12)
After 20 years, time to change Merv’s medicine? Channel 4 News blogs, Faisal Silam (9/10/12)
King signals inflation not primary focus Financial Times, Norma Cohen and Sarah O’Connor (9/10/12)
Should Bank start the helicopter? BBC News, Stephanie Flanders (12/10/12)
Speech
Twenty years of inflation targeting Bank of England speeches, Mervyn King (9/10/12)
Questions
- What are the arguments for using monetary policy to target a particular rate of inflation?
- Would it ever be a good idea to adjust the targeted rate of inflation up or down and if so when and why?
- Explain how a Taylor rule would work and in what ways it is superior or inferior to pursuing a simple inflation target.
- Are attempts to control the money supply through quantitative easing (or tightening) consistent or inconsistent with pursuing an inflation target? Explain.
- What are the arguments for and against abandoning targeting in monetary policy and replacing it with discretionary policy that takes a number of different macroeconomic indicators into account?
 Youth unemployment has been one of the main headlines for some months, with data showing a record number of young people out of work.
As part of the government’s £1bn Youth Contract that aims to help young people back into work and help those unable to find employment, Nick Clegg has announced wage subsidies to firms hiring 18-24 year olds will be paid earlier.
Some of the costs of unemployment are obvious. For the individual who is unemployed, it means a lack of income and hence inability to buy goods and services. This then has wider implications for the economy. If people are unable to purchase goods and services, this contributes to a lower level of aggregate demand, which in times of recession, is hardly ideal.
Unemployment also means an inefficient use of resources, meaning the economy is operating below full capacity. Fewer people in work also implies lower tax revenues for the government, at the same time as higher unemployment benefit payments, contributing towards a growing budget deficit. This point is of particular concern, when it is young workers claiming benefits, as it could mean a life of dependency.
 There are also some longer-term consequences, in particular for those who have been out of work for some time. They lose their skills, making it harder to find a job and this can pose costs to employers and further costs to the government through re-training. As such, government initiatives to tackle youth unemployment have never been more important.
The wage subsidies that were announced back in November will now be paid when young people have been out of work for six months, instead of nine. This initiative aims to help reduce youth unemployment in areas where it is at its worst. Twenty local authorities have been identified as priorities for the government and will benefit from this scheme. As Nick Clegg said to CBI summit:
“Three months can make all the difference. When you feel like your banging your head against a brick wall, when you live in an area where opportunities are already few and far between, another 12 weeks of rejection letters, of being cut off, of sitting at home waiting, worrying, that can seriously knock the stuffing out of you, making it extremely difficult to pick yourself up …
So jobcentres will be able to make use of the subsidy before people are referred to the Work Programme, capitalising on their links with local employers, and they’ll also intensify support, so more training, more regular coaching, spending more time with young people to knock a CV into shape or prep ahead of an interview.”
There are critics of the scheme, who argue that it is too little, too late and that it will simply displace older workers, thereby creating worse unemployment for another group. Until the economy begins to grow and confidence returns to the markets, unemployment is likely to remain a frequent headline. The following articles consider the wage subsidy and the state of unemployment in the UK.
Wage subsidy could mean more jobs Independent Online, Business Report, Pierre Heistein (14/6/12)
Wage subsidies scheme moved forward The Press Association (27/6/12)
Wage subsidy plan for young workers brought forward BBC News (27/6/12)
Wage subsidies scheme moved forward Independent, Alan Jones (27/6/12)
Nick Clegg announces extra help for jobless in 20 troublespots Guardian, Juliette Jowit (27/6/12)
Young people’s prospects have ‘nose-dived’ says report BBC News, Judith Burns (25/6/12)
Economic gap between young and old significantly worse since 2008 – study Guardian, James Ball and Helene Mulholland (25/6/12)
Questions
- Why is unemployment such a big concern for the UK economy? What is so important about youth unemployment?
- Which factors have contributed towards such high youth unemployment?
- How will the wage subsidy encourage firms to take on more young people? Think about how a rational firm behaves when choosing between 2 workers.
- Why does the wage subsidy cause concern for organisations supporting the employment of older workers?
- To what extent do you agree with the Guardian article that says that young people have borne the brunt of the recession and subsequent government cuts?
- What other things have been undertaken in a bid to reduce unemployment and stimulate the economy?
- Think about the costs of unemployment. Categorise them into costs to (a) the individual, (b) friends and family, (c) the government and (d) the economy.
 Will we soon live in a world without cash? More and more payments are being made electronically: whether by credit card or debit card, or by direct debit or bank transfer, or by cash loaded cards. For many people cash is now largely used only for small transactions.
But even here, things are changing. Direct transfers via mobile phone apps are increasingly being used for small transactions. Mobile phone companies, banks and others are busy developing such apps and more and more are being released onto the market.
And it’s not just in developed countries. Many developing countries are finding that mobile phones are an ideal way of transferring money for a whole range of transactions. For example, in Kenya, under 20% have a formal bank account, only 1% have a landline and yet more than 70% have a mobile phone, and this percentage is still rising. In 2007, a system known as M-Pesa (see also) was launched:
The user can create a free account and deposit money into it for free with registered agents at retail outlets. They may be gas stations, supermarkets, banks or micro-finance providers or small and medium-sized businesses. No minimum account balance is required.
The user can then transfer up to $440 from the account to someone else — including someone who doesn’t have a cellphone. The recipient provides identification and picks up the cash from another registered agent.
Users can deposit and withdraw cash, pay water and electricity bills, pay their children’s school fees, get paid by their employers or buy extra airtime for their phone.
Other developing countries are introducing similar systems. The second webcast link below gives an example from South Africa.
So how long will it be before cash disappears as a medium of exchange? Or will people continue to prefer to carry cash around with them – especially given the convenience of having cash machines readily available which do not charge for use.
Webcasts
 Life in a cashless society BBC News Magazine, David Wolman (14/6/12)
FNB Introduces Cashless Payment App ABNDigital on YouTube (14/5/12) (see also FNB launches new geo-payment system IT News, Africa
PayPal leads mobile payments push Reuters (4/6/12)
Are We Moving Towards a Cashless Society? TheAlyonaShow on YouTube (14/3/12)
Articles
More than 70 per cent of Canadians ready to go “cashless” CNW (13/6/12)
Is a cashless society on the way? Westfair Online, Janice Kirkel (18/5/12)
Mobile money misery BBC News, Rory Cellan-Jones (16/5/12)
Cellphones transform Kenyan commerce CBC News (27/10/10)
Chart
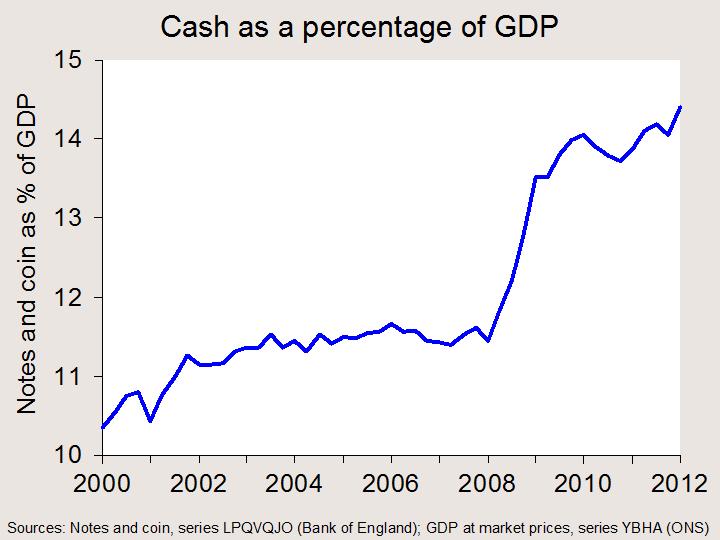
For a PowerPoint of the above chart, click here.
Questions
- What are the advantages and disadvantages of using cash?
- To what extent can mobile phone technology replace cash? What are the advantages and disadvantages of such technology?
- To what extent can mobile phone technology fulfil the various functions of money?
- Private-sector holdings of cash have been rising as a proportion of (nominal) GDP – see above chart. Is this consistent with a decreased use of cash? Explain.
- Why may mobile phone transactions be particularly useful in developing countries?
- What proportion of your own expenditure is conducted by cash? Has this changed over the past couple of years? If so, explain why.
 This has been a week of gloomy prognostications. On Wednesday 16 May, the Bank of England published its quarterly Inflation Report – and it makes worrying reading.
The forecast of UK economic growth for 2012 has been reduced from 1.2% in the previous report to 0.8%. But the rate of inflation is forecast to remain above the 2% target well into next year. However, at the two-year horizon, inflation is now forecast to be 1.6% – below the target, thus giving the MPC scope for further quantitative easing.
In the introduction to the report, the Governor, Mervyn King, writes:
Over the past year or so, two factors have hampered the recovery and rebalancing by more than expected. First, higher-than-expected world commodity and energy prices have squeezed real take-home pay, dampening consumption growth. Second, credit conditions, far from easing, have in some cases become tighter. The direct and indirect exposures of UK banks to the euro-area periphery have affected funding costs as the challenges of tackling the indebtedness and lack of competitiveness in those countries have intensified.
And at the news conference launching the report, he said:
We have been through a big global financial crisis, the biggest downturn in world output since the 1930s, the biggest banking crisis in this country’s history, the biggest fiscal deficit in our peace time history and our biggest trading partner – the euro area – is tearing itself apart without any obvious solution.
The idea that we could reasonably hope to sail serenely through this with growth close to the long run average and inflation at 2% strikes me as wholly unrealistic. We’re bound to be buffeted by this and affected by it.
 The following articles look at the Bank of England’s predictions and at the challenges facing the UK economy as the crisis in the eurozone deepens and as inflation in the UK remains stubbornly above target. They also look at the issue of the extent to which capacity has been lost as a result of the continuing weakness of the UK economy. As The Economist article states:
Business surveys suggest only a small proportion of firms are operating below capacity. That finding looks odd given the economy’s output is still 4% below its level at the start of 2008, and is much farther below the level it would have reached if GDP growth had continued at its long-term rate. The picture painted by surveys could be right if a chunk of the economy’s potential has been written off for good. But Sir Mervyn King, the bank’s governor, doubts this. There is “no obvious reason” why the economy could not rejoin its pre-crisis path, though it might take a decade or two to get there, he said on May 16th.
We look in more detail at the question of lost capacity in Part 2.
Articles
Bank of England cuts growth forecasts: Sir Mervyn King’s speech in full The Telegraph (16/5/12)
Bank of England sees inflation up and growth falling Independent, Ben Chu (17/5/12)
Hard going The Economist (19/5/12)
Bank of England optimism dented again Financial Times, Chris Giles (16/5/12)
Eurozone is ‘tearing itself apart’, says Mervyn King. True, but the UK’s problems are as intractable as ever The Telegraph, Philip Aldrick (16/5/12)
Inflation Report
Inflation Report: portal page Bank of England
Inflation Report: May 2012 Bank of England (16/5/12)
Additional Data
Statistical annex to European Economy. Spring 2012 European Commission, Economic and Financial AffairsAnnual macro-economic database European Commission, Economic and Financial Affairs (11/5/12) (see particularly section 6.5)
Forecasts for the UK economy HM Treasury
Questions
- What explanations are given for the rate of CPI inflation remaining persistently above the 2% target?
- Why have the prospects for economic growth worsened since the publication of the February Inflation Report?
- How might it be possible to have a narrowing (negative) output gap and yet a stagnant economy?
- Why may capacity have been lost since the financial crisis of 2008?
- Why has M4 declined despite the programme of quantitative easing? (See M4 in record fall despite QE.)
- What scope is there for monetary policy in achieving faster economic growth without pushing inflation above the 2% target?
 The Bank of England was granted independence to set interest rates back in 1997. In setting rates its looks to meet the government’s annual inflation rate target of 2 per cent (with a range of tolerance of up to 1 percentage point).
The economic benefits of delegating interest rate decisions to a body like the Monetary Policy Committee (MPC) are often taken for granted. But, in David Blanchflower’s article in the Independent Newspaper on 14 May, the former MPC member questions whether, at least in recent years, better decisions would have been made by the Treasury and the Chancellor of the Exchequer. In other words, could politicians have made more appropriate monetary policy choices?
Central bank independence has become increasingly popular. Many governments have taken steps to depoliticise monetary policy choices and to hand over important powers, such as setting interest rates, to central bankers. One of the main advantages, it is argued, is that politicians are no longer able to manipulate monetary policy choices in order to try and affect their popularity and their chances of being re-elected. The policy announcements of central bankers are said to be more credible because they do not have the incentive to deviate from their announced policy. For instance, the low inflation announcements of elected policy-makers lack credibility because politicians have an incentive to inflate the economy and so boost growth and employment prior to the election.
The incentive for a pre-election dash for growth means that the general public are reluctant to bargain for low wage increases in case policy is loosened or is looser than it should be given the prevailing economic climate. In this case, it might mean that interest rates are lower than they would otherwise be in the run up to the election. In order to protect their spending power households bargain for higher wage increases than they would if the policy announcements could be trusted. In contrast, the low inflation announcements of central bankers have credibility and so inflation will be lower. In terms of economic jargon, central bank independence will reduce inflation bias as well as promoting economic stability.
Blanchflower questions whether the path of interest rates in the UK between 1997 and 2007 would have been materially different should the Treasury have been setting interest rates rather than the MPC. But, he believes that:
Interest rates would probably have been higher in 2007 as the housing boom was ranging and house price to earnings ratios approached unsustainable levels. Alistair Darling has made it clear he would have cut rates earlier in 2008, if it had been left to him….
Blanchflower argues that part of the reason that the Treasury might have made better choices in the more recent past is the narrow remit of the Bank of England to target inflation. He argues:
Now is the time to consider switching to a dual mandate that would include growth, which would give much needed flexibility.
Blanchflower calls into question the idea that targeting inflation alone can bring stability. The recent past he argues simply dispels this notion. To help form your own views try having a read of the full article and then answer the questions below.
David Blanchflower Article
The recession deniers have gone strangely quiet this month Independent, David Blanchflower (14/05/12)
Questions
- If economic growth is a good thing, why might we want to reduce the chances of policymakers manipulating policy to attempt a pre-election dash for growth?
- What do you understand by credible economic policy announcements? How might a lack of credibility affect the economy’s rate of inflation?
- What does central bank independence mean for the conduct of monetary policy in the UK? In answering this you might wish to visit the Bank of England website and read about the UK’s monetary policy framework.
- Try summarising David Blanchflower’s argument against the inflation rate remit of the Bank of England.
- What do you consider to be the possible dangers of widening the Bank of England’s remit beyond just targeting the annual rate of CPI inflation?
- Central bank independence is one way in which governments can constrain their discretion over economic policy. In what other ways can they constrain their policy choices?
- Do you think governments should have full discretion over their policy choices or do you think there should be limits?
 Should the object of monetary policy be simply one of keeping inflation within a target range? In a speech given on 9 October, the Governor of the Bank of England, Sir Mervyn King, questioned whether the interest-rate setting policy of the Monetary Policy Committee (MPC) has been too narrow.
 Then there is the question of economic growth. Should a target rate of growth be part of the MPC’s target? Should the MPC adopt a form of Taylor rule which targets a weighted average of the inflation rate and the rate of economic growth?